
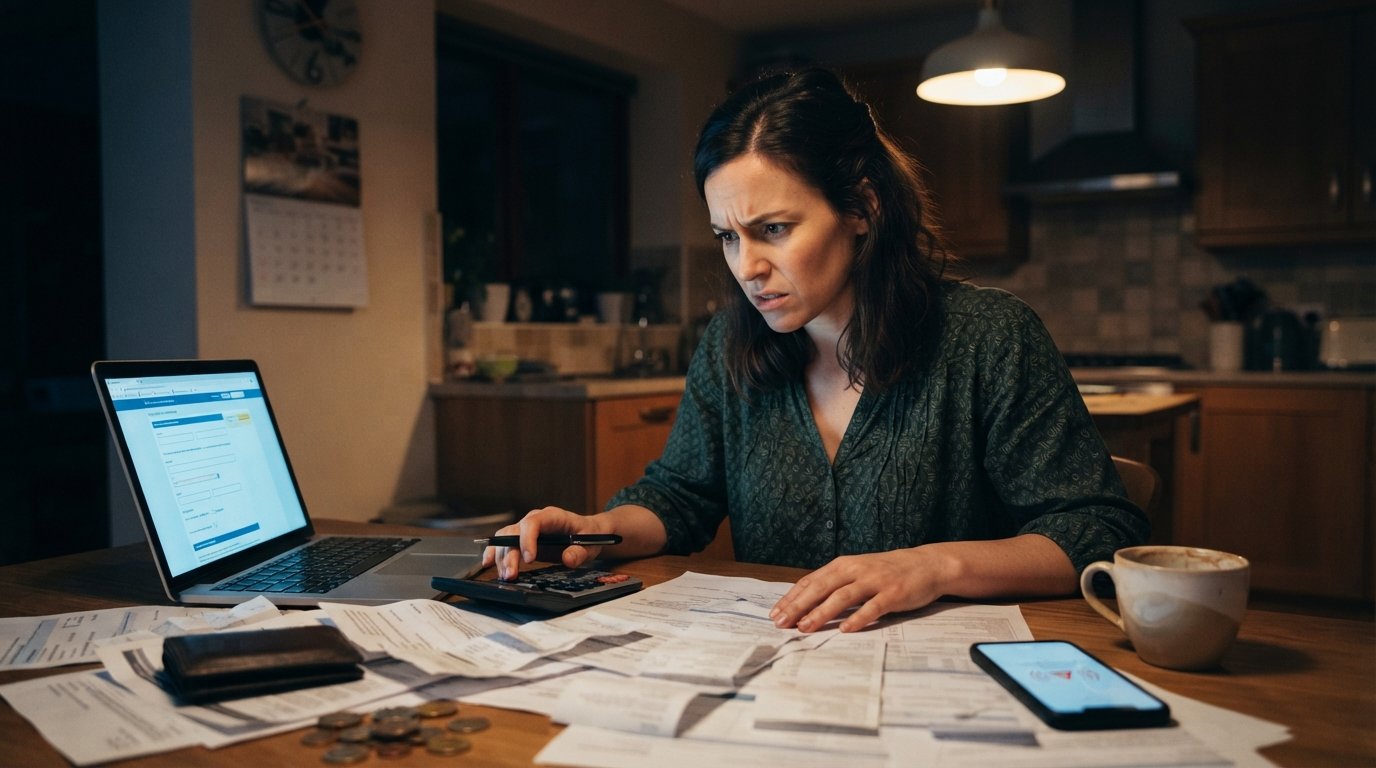
Avoid Payday Loan Application Mistakes Online
Avoid costly payday loan mistakes online with smart application habits. Call us at 8335013363 for guidance on finding the right loan offer.
By Isaac Ellis
Applying for a payday loan online can feel like a race against the clock when an unexpected bill lands on your desk. The promise of fast cash with minimal paperwork is appealing, especially when your car breaks down or a medical expense catches you off guard. But that speed and convenience can also work against you if you rush through the application without understanding the terms, the costs, or the lender you are dealing with. Many borrowers make avoidable errors that lead to denied applications, higher fees, or a cycle of debt that is harder to escape than the original emergency.
The good news is that most of these mistakes follow predictable patterns, and once you know what they are, you can sidestep them entirely. Whether you are working with a loan connection service like LendersCashLoan or comparing offers from a network of third-party lenders, a few smart habits will protect your wallet and your credit. This guide walks you through the most common pitfalls and shows you exactly how to avoid common mistakes when applying for a payday loan online, so you can secure the funds you need without creating a bigger financial problem down the road.
Understand What a Payday Loan Really Is Before You Apply
One of the biggest mistakes people make is treating a payday loan like any other personal loan. A payday loan is a short-term, high-cost form of borrowing designed to be repaid on your next payday. Unlike installment loans that spread payments over months or years, a payday loan typically comes due in full within two to four weeks. That short window is exactly why the fees can be so steep relative to the amount borrowed.
When you apply for a payday loan online, you are often not applying to a single lender. You are submitting a request to a network of third-party lenders who each evaluate your information and may return an offer. This is how connection services work, and it is an important distinction. The platform itself does not lend money or make credit decisions. It simply connects you with lenders who do. Understanding this prevents confusion when you receive multiple offers with different terms, rates, and repayment schedules.
Before you type in your personal details, ask yourself a few grounding questions:
- Is this expense truly urgent, or can it wait until I have saved the cash?
- Will I realistically be able to repay the full amount plus fees by my next payday?
- Have I explored other options like a payment plan with the service provider or a small personal loan?
- Do I understand that short-term loans are not a long-term financial solution?
Answering these honestly will help you decide whether a payday loan is the right tool for your situation or whether a different approach makes more sense. Skipping this step is one of the most common mistakes, and it often leads to borrowing more than you can comfortably repay.
Failing to Compare Offers from Multiple Lenders
When you are stressed about money, it is tempting to accept the first offer that lands in your inbox. That is a mistake. Different lenders in a network can offer very different terms, including interest rates, fees, repayment schedules, and rollover policies. Accepting the first offer without comparing can cost you significantly more than necessary.
Take the time to review each offer side by side. Look beyond the amount you will receive and focus on the total cost of borrowing. A loan with a lower principal but a higher annual percentage rate (APR) can end up costing more than a slightly larger loan with more favorable terms. Similarly, a lender that offers a longer repayment window might charge more in total interest but give you breathing room to repay without defaulting.
If you are using a connection service, you may receive multiple offers after submitting a single request. This is one of the advantages of the model. Rather than visiting lender after lender, you can see several options in one place. Review them carefully, and do not feel pressured to accept any offer that does not feel manageable. A reputable connection service will never force you to accept a loan, and there is no obligation to proceed.
If you want to explore a streamlined way to compare loan offers from a network of lenders, you can start with FreeQuotes.Loans, which helps users in the United States find personalized loan offers for payday loans, personal loans, and installment loans, including options for those with less-than-perfect credit.
Ignoring the Fine Print and Fee Structure
The fine print is where costly surprises live. Payday loans often come with fees that are not immediately obvious, such as origination fees, late payment penalties, and rollover charges. If you do not read the loan agreement carefully, you may find yourself paying far more than you expected.
Key details to look for include the APR, the finance charge, the repayment date, and the consequences of late payment. Some lenders offer a grace period, while others begin charging fees immediately after the due date. Understanding these terms before you sign can save you from a nasty shock later.
Another detail often overlooked is the automatic renewal or rollover clause. Some payday loans automatically renew if you do not repay them on time, which means you incur additional fees and your debt grows. If you are not prepared to repay the full amount by the due date, a rollover can trap you in a cycle of debt that is difficult to break.
Before accepting any offer, confirm the following:
- The exact APR and total finance charge
- The repayment date and whether extensions are available
- Any fees for late payment or returned payments
- Whether the loan renews automatically and how to opt out
- The lender's contact information and customer support hours
If any of these details are unclear, ask the lender directly before you agree to anything. A legitimate lender will provide clear answers. If they dodge your questions or pressure you to sign quickly, that is a red flag.
Providing Inaccurate or Incomplete Information
Accuracy matters when you apply for a payday loan online. Lenders use the information you provide to verify your identity, assess your eligibility, and determine your loan terms. If you enter incorrect details, even by accident, your application may be denied or delayed.
Common errors include misspelling your name, entering the wrong Social Security number, listing an outdated address, or providing a bank account number that does not match your name. These mistakes can trigger additional verification steps or cause the lender to reject your application outright. In some cases, they can even flag your application as potentially fraudulent.
Before you submit, double-check every field. Make sure your income information is accurate and that your bank account is in good standing. Lenders typically require an active checking account and a steady source of income, so if either is missing, your application may not move forward.
It also helps to gather your documents ahead of time. Having your ID, proof of income, and bank details ready will speed up the process and reduce the chance of errors. A few extra minutes of preparation can save you hours of frustration and multiple application attempts.
Applying to Too Many Lenders at Once
It is natural to want options, but applying to dozens of lenders simultaneously can backfire. Each application may trigger a hard credit inquiry, which can temporarily lower your credit score. If you submit multiple applications in a short period, lenders may see you as a high-risk borrower and deny your requests.
Using a connection service solves this problem to some extent because you submit one request and receive offers from multiple lenders. However, you should still be selective. Only proceed with lenders whose offers you are seriously considering. Avoid submitting formal applications to every lender that responds.
If you are unsure which offer to pursue, focus on the total cost of borrowing and the repayment terms. A loan that fits comfortably into your budget is worth more than one with a slightly lower rate but an unrealistic repayment schedule. Remember, the goal is to solve your immediate financial need without creating a new one.
Overlooking Eligibility Requirements
Payday loans are often marketed as easy to get, but they still have eligibility requirements. Most lenders require you to be at least 18 years old, have a valid government-issued ID, have an active checking account, and earn a steady income. Some lenders also require a minimum income level or may not lend to residents of certain states.
If you do not meet these requirements, your application will be denied, and repeated denials can hurt your credit score. Before you apply, review the lender's eligibility criteria and confirm that you qualify. If you have bad credit, do not assume you will be automatically rejected. Many lenders in the payday loan space work with borrowers who have less-than-perfect credit, as long as they meet income and banking requirements.
It is also important to understand that payday loan laws vary by state. Some states cap the maximum loan amount or limit the fees lenders can charge. Others prohibit payday loans entirely. Knowing the rules in your state will help you avoid applying for a loan that is not legally available to you.
Not Having a Repayment Plan
One of the most dangerous mistakes is borrowing without a clear plan to repay. Payday loans are designed to be repaid quickly, and if you miss the due date, the fees and interest can snowball. Before you accept an offer, map out exactly how you will repay the loan.
Consider your income timing. If you are paid biweekly, make sure your loan due date aligns with your pay schedule. If your income is irregular, think carefully about whether you can reliably set aside the repayment amount. If there is any doubt, consider a smaller loan or an installment loan with more flexible repayment terms.
It also helps to build a small buffer into your budget. Unexpected expenses do not stop just because you took out a loan. If you can, set aside a little extra each week so that you are not caught off guard if something else comes up. Communicating with your lender early if you anticipate trouble can also help. Many lenders are willing to work with borrowers who reach out before missing a payment rather than after.
Choosing the Wrong Lender or Platform
Not all lenders are created equal. Some operate responsibly and transparently, while others use predatory practices that trap borrowers in debt. Choosing the wrong lender can turn a temporary financial fix into a long-term problem.
Look for lenders who are upfront about their terms, provide clear contact information, and do not pressure you to accept an offer. Avoid lenders who ask for upfront fees before disbursing funds, promise guaranteed approval, or refuse to provide written terms. These are classic signs of a scam or a predatory lender.
Using a reputable connection service can reduce your risk. Platforms like LendersCashLoan connect you with a network of independent lenders and provide educational resources to help you make informed decisions. They do not make lending decisions or fund loans directly, but they can streamline the process and help you see multiple offers in one place. Always verify that the platform uses secure encryption and has clear privacy and terms policies.
Frequently Asked Questions
Can I get a payday loan with bad credit?
Yes, many lenders in the payday loan space work with borrowers who have less-than-perfect credit. Approval is often based on income, employment, and banking history rather than credit score alone. However, bad credit may result in higher fees or less favorable terms, so compare offers carefully.
How fast can I receive funds?
Funding times vary by lender. Some lenders can deposit funds as soon as the next business day after approval. Others may take longer depending on your bank's processing times. If speed is critical, ask the lender about their disbursement timeline before you accept an offer.
What happens if I cannot repay on time?
If you miss a payment, you may incur late fees, additional interest, or both. Some lenders may offer a grace period or the option to roll over the loan, but these options often come with additional costs. Contact your lender as soon as you realize you may not be able to pay on time to discuss possible solutions.
Are payday loans safe?
Payday loans can be safe when you borrow from a reputable lender and fully understand the terms. The risks come from borrowing more than you can repay, ignoring the fine print, or working with predatory lenders. Always read the agreement, compare offers, and borrow responsibly.
Do I need a bank account to get a payday loan?
Most lenders require an active checking account for direct deposit and repayment. Some may also accept prepaid accounts, but this varies. Check the lender's requirements before applying.
Navigating the payday loan process does not have to be risky. By understanding the product, comparing offers, reading the fine print, and planning your repayment, you can avoid the mistakes that trip up so many borrowers. Take your time, ask questions, and choose the option that fits your budget and your timeline. A little caution today can save you a lot of stress tomorrow.