
Gig Worker Loan Documents: What You Need to Apply Online
Gig workers need platform statements, bank records, and 1099s for an online loan request. Call (833)-501-3363 for guidance on your application.
By Isaac Ellis
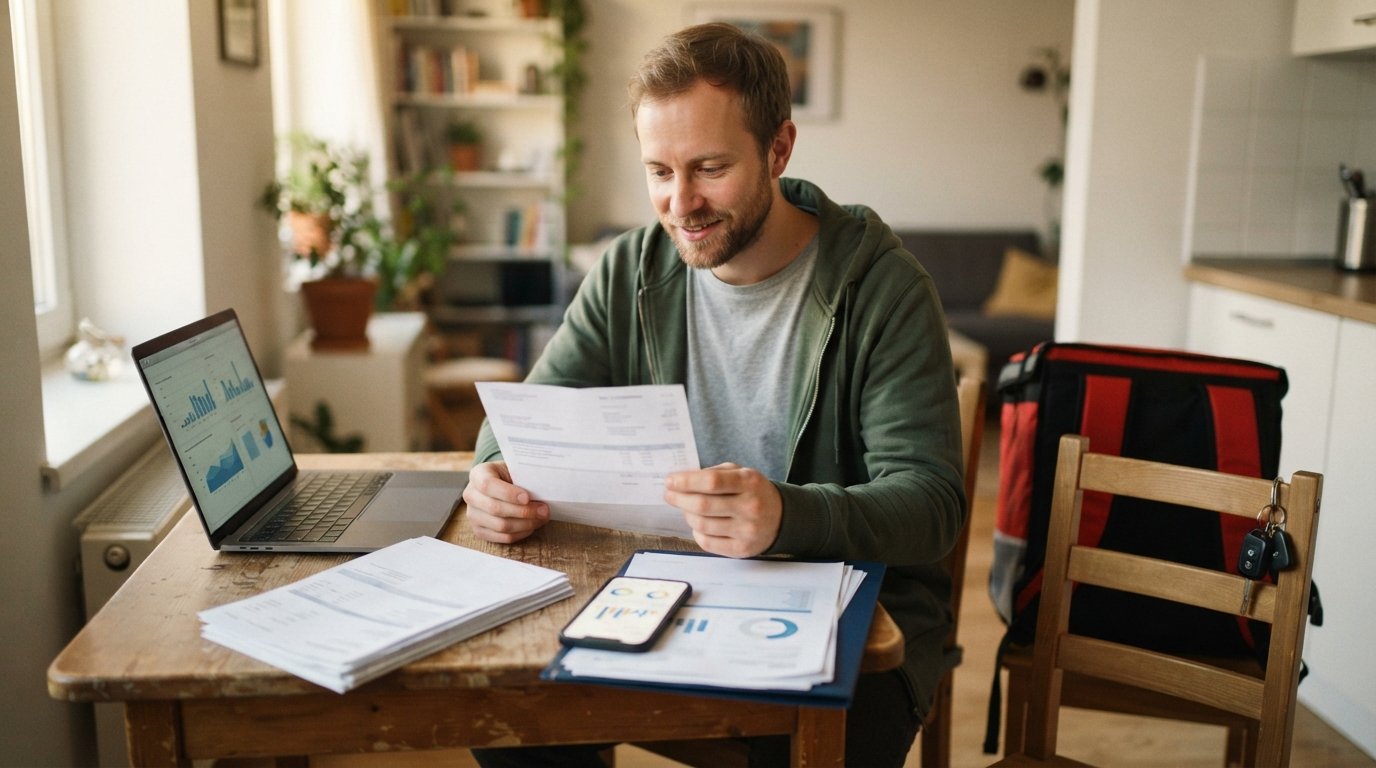
If you drive for a rideshare app, deliver packages, or freelance from your laptop, you already know that steady paychecks are a thing of the past. But when an emergency hits and you need cash fast, the paperwork can feel like a roadblock. The good news is that online lenders have adapted to the gig economy, and there are clear, achievable steps to prove your income without a traditional W-2. Understanding what documents do gig workers need for an online loan request is your first move toward a smoother application and a faster funding decision.
In this guide, we break down the exact paperwork lenders typically ask for, how to present variable earnings in the best light, and how a connection service like LendersCashLoan can route your request to lenders who are comfortable with non-traditional income. We will also cover how to prepare your banking details so that if you are approved, funds can arrive as soon as the next business day.
Why Gig Workers Face Extra Scrutiny (and How to Overcome It)
Traditional lenders rely on pay stubs and W-2 forms because they are standardized and easy to verify. Gig workers, by contrast, often have income that fluctuates week to week and arrives through platforms rather than a single employer. That does not mean you are out of luck, but it does mean you need to be prepared to document your earnings in a way that reassures a lender you can repay what you borrow.
The key is consistency and transparency. Lenders want to see that your gig work is not a one-time experiment but an ongoing source of income. Even if your monthly total varies, a pattern of deposits over several months tells a story of reliability. The documents below help you tell that story clearly.
Core Documents for an Online Loan Request
Most online loan connection services, including LendersCashLoan, ask for a basic set of documents to verify your identity and financial profile. Having these ready before you start can cut your application time down to minutes.
- Government-issued photo ID: A driver's license, state ID, or passport to confirm you are who you say you are.
- Proof of income: This is where gig workers need to get creative. We cover the accepted formats in detail below.
- Bank account information: Routing and account numbers for the account where you want funds deposited and from which payments will be withdrawn.
- Social Security number: Required for a credit check and identity verification.
- Contact information: A valid email address and phone number so lenders can reach you.
These five items form the foundation of nearly every online loan request. The second item, proof of income, is the one that trips up most gig workers. Let us unpack that next.
Accepted Proof of Income for Gig Workers
Lenders understand that gig workers do not receive traditional pay stubs. Instead, they look for alternative documents that show a history of earnings. The three most commonly accepted forms are platform statements, bank deposit records, and 1099 forms.
Platform Statements and Earnings Summaries
If you earn through Uber, Lyft, DoorDash, Upwork, Fiverr, or similar platforms, you can typically download a weekly or monthly earnings statement directly from the app or website. These statements show your gross earnings, any fees deducted, and the net amount paid to you. Lenders may accept these as proof of income, especially if they cover a period of several months.
To strengthen your case, gather statements for at least the last three to six months. If your income varies, a longer history helps demonstrate an average that you can comfortably repay from.
Bank Statements Showing Deposits
Your bank statements are often the most persuasive document because they show actual money landing in your account. Lenders can see the frequency and size of deposits from gig platforms, which gives them a real-world picture of your cash flow. Many online lenders ask for the last two to three months of bank statements.
Make sure the statements clearly show the platform name (for example, "Uber" or "DoorDash") in the transaction description. If deposits appear under a generic processor name, be prepared to explain the connection.
1099 Forms and Tax Returns
If you file taxes as an independent contractor, you receive 1099 forms from each platform that paid you $600 or more during the year. These forms are excellent proof of self-employment income. Your most recent tax return, including Schedule C, provides an even broader view of your earnings and deductions.
Keep in mind that 1099s reflect gross earnings before expenses, while your bank statements show net deposits. Lenders may look at both to get a complete picture. Having both types of documents ready can speed up the verification process.
How to Show Consistent Earnings Despite Week-to-Week Variation
Gig work is inherently variable. One week you might earn $800, the next $400. Lenders know this, but they still need to assess risk. The trick is to present your income in a way that highlights stability rather than volatility.
Start by calculating a rolling average of your monthly earnings over the past three to six months. Use bank statements or platform summaries to add up total deposits and divide by the number of months. This average is the figure you can confidently cite when asked about income. If your average is above the lender's minimum threshold, you are in good shape.
You can also provide a simple one-page summary that lists your platforms, the months covered, and the total earnings from each. This proactive step shows organization and makes the lender's job easier. Some lenders may not require it, but it can set you apart from other applicants.
Finally, be honest about seasonal fluctuations. If your income dips in certain months, explain why (for example, fewer rides during the summer). Lenders appreciate transparency and may factor it into their decision.
Why LendersCashLoan Routes Requests to Lenders Who Understand Gig Income
Not all lenders are created equal when it comes to non-traditional income. Some still cling to outdated underwriting models that require a W-2, while others have embraced the gig economy and built their criteria around it. This is where a connection service like LendersCashLoan adds value.
LendersCashLoan is not a direct lender; it is a digital loan connection service that submits your request to a network of third-party lenders. The platform explicitly welcomes applicants with less-than-perfect credit and non-traditional income, provided they meet basic income criteria. By completing a single online request, you can be matched with lenders who may be more receptive to platform statements and bank deposits as proof of income.
This approach saves you the time and frustration of applying to multiple lenders individually, each with its own paperwork requirements. Instead, you fill out one form, and the service routes your information to lenders whose criteria align with your profile. If you want to compare offers and choose the best fit, you can read our guide on how to choose the best lender offer to make an informed decision.
For those who prefer a direct connection to a network of lenders, ExpressCash offers a similar service, connecting consumers with third-party lenders for short-term loans. Both platforms serve borrowers who need fast access to funds and may have less-than-perfect credit.
Preparing Your Banking Details for Direct Deposit Funding
Once you have your documents in order, the final piece is making sure your banking information is correct and ready. Most online lenders fund loans via direct deposit, which is the fastest way to get cash in your account. A single typo in your account number can delay funding by days, so double-check everything.
You will need your bank's routing number (the nine-digit number at the bottom left of a check) and your account number. If you use an online-only bank, log in to your account and look for the routing and account numbers in the settings or deposit information section. Some lenders may also ask for a voided check or a bank statement to verify ownership of the account.
Ensure that the name on your bank account matches the name on your loan application. Mismatched names are a common reason for funding delays. If you have a joint account, confirm that the lender accepts joint accounts before submitting your request.
Finally, consider the timing. Direct deposits are typically processed on business days, so if you are approved on a Friday afternoon, funds may not arrive until Monday or Tuesday. Plan accordingly if you have an urgent expense.
Documents You Do Not Necessarily Need (But Might Help)
While the core documents above are usually sufficient, some lenders may request additional items depending on your situation. These are not always required, but having them ready can streamline the process if asked.
- Proof of address: A utility bill or lease agreement in your name.
- References: Some lenders ask for personal or professional references, though this is less common for online loans.
- Debt obligations: Information about existing loans or credit card balances to help the lender assess your debt-to-income ratio.
Gathering these in advance shows preparedness and can prevent back-and-forth requests that slow down your application.
Common Mistakes to Avoid When Submitting Your Documents
Even with the right documents, small errors can derail your request. Here are a few pitfalls to watch for.
First, do not submit blurry or incomplete screenshots. Lenders need to read the document clearly, so take a moment to ensure the image is sharp and all pages are included. Second, avoid redacting information that the lender needs, such as your name or the deposit amounts. Redactions can trigger a rejection or a request for new documents. Third, do not provide documents that are outdated; most lenders want to see recent activity, typically within the last 60 to 90 days.
Finally, be consistent. If your bank statements show one name and your ID shows another (for example, a maiden name), provide supporting documentation such as a marriage certificate. Consistency builds trust and speeds up verification.
Frequently Asked Questions
Can I use a screenshot from my gig app as proof of income?
Some lenders accept screenshots, but official platform statements or bank statements are more widely accepted. If you use a screenshot, make sure it clearly shows your name, the platform name, the date range, and the earnings amount. It is safer to download the PDF statement if available.
What if my income is mostly cash?
Cash income is harder to verify, but you can still document it through bank deposits. If you deposit cash regularly, your bank statements will show those deposits. You can also keep a simple ledger of cash earnings, though lenders may give it less weight than bank records.
Do I need a minimum credit score to apply?
LendersCashLoan does not set a minimum credit score, and it welcomes applicants with bad credit. However, individual lenders in the network may have their own criteria. Submitting a request allows you to see offers from lenders who may work with your credit profile.
How long does the online loan request take?
The request form typically takes under five minutes to complete. After submitting, you may receive offers from lenders quickly, sometimes within minutes. Funding times vary by lender but can be as soon as the next business day.
Getting a loan as a gig worker is entirely possible when you know which documents to gather and how to present your income. By preparing your ID, proof of income, and banking details in advance, you can move through the online request process with confidence. And if you are unsure where to start, a connection service like LendersCashLoan can match you with lenders who understand the gig economy and are ready to work with your unique financial picture.