
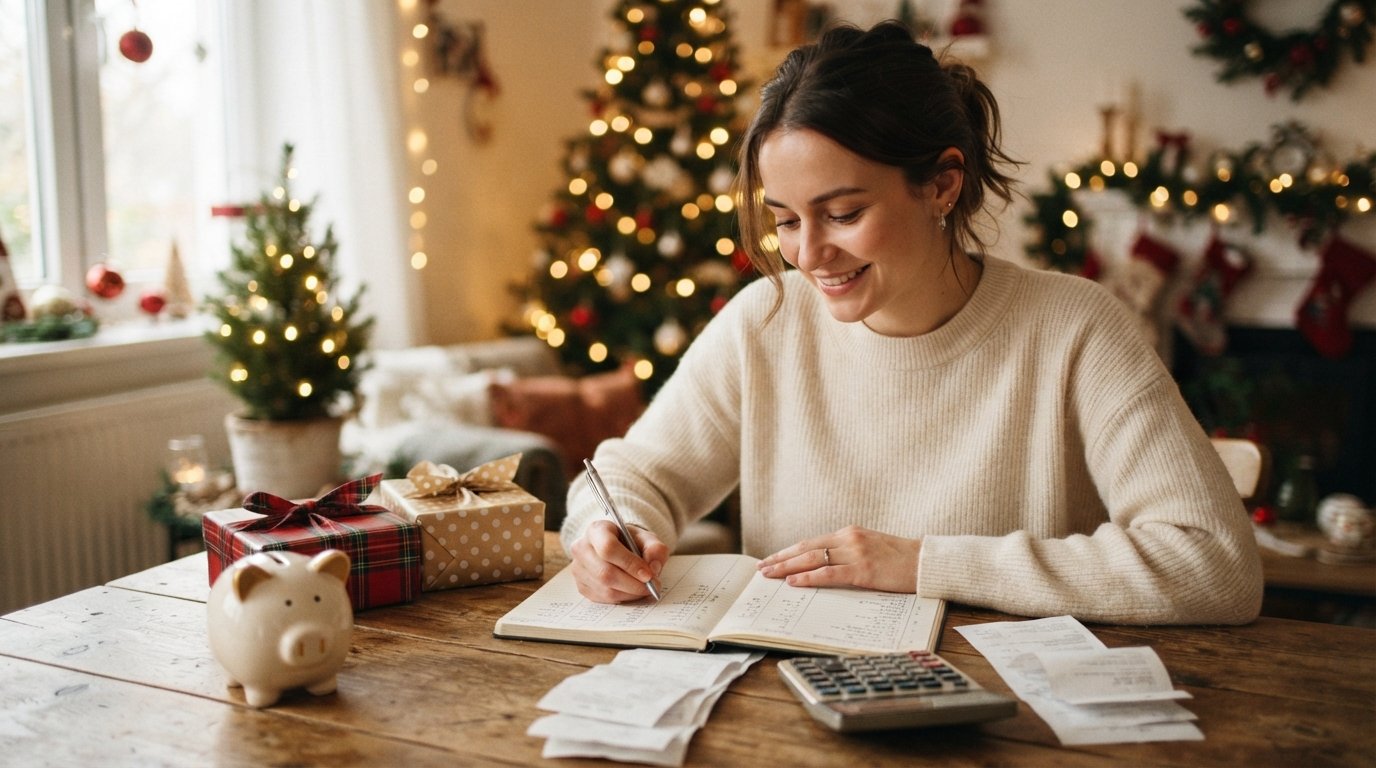
How to Avoid Taking a Loan for a Holiday Shortfall
Learn how to avoid taking a loan for a holiday shortfall with practical tips on forecasting, timing payments, and building a small savings buffer.
By Wesley Owens
The holiday season has a way of turning generous intentions into financial stress. Between gifts, travel, gatherings, and the steady drumbeat of seasonal sales, it is easy to overspend and find yourself facing a shortfall before the decorations even come down. The good news is that you do not have to reach for a loan the moment your budget feels tight. With a bit of foresight and some disciplined strategies, you can bridge the gap without adding debt to your holiday cheer.
This guide walks you through practical ways to avoid taking a loan for a holiday shortfall, from forecasting your expenses early to timing your bill payments and building a small cash cushion. We will also look at when a small installment loan might actually be the more responsible choice, and how to steer clear of the dreaded post-holiday debt stack. Whether you celebrate with a big family feast or a quiet exchange of gifts, these steps can help you keep your finances merry and bright.
Forecast the Shortfall Before the Season Starts
The first step in avoiding a holiday loan is to see the shortfall coming. Too often, people wait until the last minute to tally up their holiday spending, only to realize they have run out of cash. By forecasting your expenses a few months in advance, you give yourself time to adjust, save, or find alternatives.
Start by listing every holiday-related cost you expect: gifts, wrapping paper, cards, postage, travel, food, decorations, and any special events. Be honest and specific. If you usually spend $50 on each niece and nephew, write that down. If you host a dinner, estimate the grocery bill. Then compare that total to the money you realistically have available after covering regular bills and obligations.
The difference is your potential shortfall. Once you have a number, you can take action. For example, if you anticipate a $300 gap, you can set aside $75 per month for four months, or cut back on discretionary spending in other areas. Forecasting turns a vague worry into a concrete problem with a solution.
Consider using a simple spreadsheet or a budgeting app to track your holiday expenses. Many banks also offer spending analysis tools that categorize your transactions, which can help you spot trends from previous years. If you often overspend on gifts, set a per-person limit and stick to it. The goal is not to eliminate joy but to plan for it.
Time Your Payments to Reduce Pressure
Sometimes the shortfall is not about a lack of money overall but about timing. Your bills and your income may not align perfectly with holiday expenses. By strategically timing your payments, you can create breathing room without borrowing.
Look at your recurring bills and see which ones can be shifted. For instance, if your car insurance is due in December, ask your insurer if you can change the due date to January. Many providers allow this once per year at no cost. Similarly, you might adjust the due date of your credit card payments to better match your pay cycle.
Another tactic is to pay certain bills early when you have extra cash. If you get a bonus or a side gig payment in November, use it to knock out a January bill ahead of time. That way, when the holiday expenses hit, you have fewer financial obligations competing for your attention.
Here are a few payment-timing moves that can ease the squeeze:
- Call your utility company and ask to move your due date to a less expensive time of the month.
- Set up automatic payments for fixed bills to avoid late fees and free up mental energy.
- Use any extra income (like a tax refund or bonus) to prepay bills that would otherwise pile up in December.
- Negotiate a payment plan with creditors if you know you will be short, rather than waiting until you miss a payment.
These small adjustments can make a big difference. For example, moving a $150 insurance bill from December to January means you have $150 more available for holiday expenses without borrowing a dime.
Build a Small Savings Goal in the Weeks Before
Even if you start late, you can still build a small holiday fund in the weeks leading up to the season. The key is to start small and be consistent. Setting aside even $10 or $20 per week can add up faster than you think.
Begin by opening a separate savings account specifically for holiday expenses. Many banks offer sub-savings accounts with no fees, and some even pay a little interest. Having a dedicated account makes it easier to track your progress and resist the temptation to dip into it for non-holiday spending.
Next, identify areas where you can cut back temporarily. Maybe you can skip your daily coffee shop run, pack lunches for a month, or pause a subscription service. Redirect those savings into your holiday fund. You might also consider selling unused items around the house, such as old electronics, clothes, or furniture, to generate quick cash.
Another approach is to use the envelope system for holiday cash. Withdraw a set amount of cash each week and put it in an envelope labeled for gifts or food. When the cash is gone, you are done spending. This physical limit can be surprisingly effective at curbing impulse purchases.
Remember, the goal is not to become a scrooge but to avoid the stress of a loan. A small savings buffer gives you the freedom to enjoy the season without worrying about how you will pay for it later.
When a Small Installment Loan Is the More Responsible Choice
Despite your best efforts, sometimes a shortfall is unavoidable. In certain situations, a small installment loan can be a more responsible choice than other alternatives, provided you approach it with caution. The key is to distinguish between using a loan as a planned tool versus a desperate fix.
An installment loan allows you to borrow a fixed amount and repay it in equal monthly installments over a set period. This structure can be easier to manage than a payday loan, which typically comes due in a lump sum on your next payday. If you have a one-time expense that you can repay over a few months, an installment loan may offer more predictability.
However, it is crucial to borrow only what you need and to have a clear repayment plan. Before taking on any loan, ask yourself: can I afford the monthly payment without straining my budget? If the answer is no, then a loan is not the solution. Also, be wary of loans with extremely high interest rates or fees. Always read the terms and conditions, and consider using a loan connection service like Emergency Personal Loans: Fast Cash When You Need It to compare offers from multiple lenders. LendersCashLoan is not a direct lender but connects you with a network of third-party lenders who may offer short-term personal loans. Their service is free and does not obligate you to accept any offer.
When used wisely, a small installment loan can help you cover a temporary gap without derailing your long-term finances. But it should be a last resort, not a first impulse. Exhaust other options first, such as negotiating with creditors, using savings, or cutting expenses.
Avoid Post-Holiday Debt Stacking
One of the biggest dangers of holiday borrowing is the tendency to stack debt. You might take out a loan for gifts, then use a credit card for travel, and then find yourself unable to pay the bills in January. This debt stacking can lead to a cycle of borrowing that is hard to break.
To avoid this, make a commitment to not use credit for holiday expenses unless you can pay it off in full when the statement arrives. If you must use a credit card for convenience, treat it like cash and set aside the money immediately. Better yet, use a debit card or cash to stay within your budget.
If you already have existing debt, be extra cautious about adding more. Consider creating a debt repayment plan that prioritizes high-interest debt first. The snowball method (paying off smallest debts first) or the avalanche method (paying off highest interest first) can help you stay motivated.
Another strategy is to start a post-holiday fund now. Set aside a small amount each month to cover the bills that will come due in January. That way, you will not be caught off guard when the credit card statement arrives. Prevention is always better than cure.
Finally, be honest with yourself and your family about what you can afford. It is okay to scale back. Many people appreciate thoughtful, inexpensive gifts more than extravagant ones. Focus on experiences and time together rather than material spending.
Explore Loan Connection Services as a Backup
If you have exhausted all other options and still face a shortfall, a loan connection service can be a useful resource. These platforms allow you to submit a single request and receive offers from multiple lenders, which can save time and help you find a better rate. However, it is important to understand that these services are not lenders themselves; they connect you with third-party lenders.
One such service is CashLoanFunded, which connects potential borrowers in the United States with a network of third-party lenders. They offer access to short-term loan options such as payday loans, installment loans, and personal loans. The application is simple and can be completed online in minutes. While this can be a helpful tool, remember that short-term loans are not a long-term financial solution. Use them only for genuine emergencies and have a plan to repay them promptly.
Before using any loan connection service, read the terms and conditions carefully. Understand the fees, interest rates, and repayment terms. Make sure you are comfortable with the obligations. And never borrow more than you can afford to repay.
In conclusion, avoiding a holiday loan shortfall is entirely possible with planning, discipline, and a bit of creativity. By forecasting your expenses, timing your payments, building a small savings buffer, and being mindful of debt, you can enjoy the season without the hangover of holiday debt. And if you do need help, use resources like LendersCashLoan responsibly to find the best options for your situation.