
How to Budget for a Loan Payment on a Low Income
Master how to budget for a loan payment on a low income with practical steps and real solutions. Call 8335013363 for personalized guidance.
By Henry Sullivan
Missing a loan payment hurts. It damages your credit score, adds late fees, and creates a cycle of financial stress that can feel impossible to escape. When your income barely covers groceries and rent, setting aside money for a loan payment can feel like trying to squeeze water from a stone. Yet millions of people manage this exact challenge every month, and you can too with the right strategy. The key is not simply earning more money (though that helps). The key is building a realistic, flexible system that accounts for every dollar and protects your ability to repay on time.
This guide walks you through practical, proven methods for how to budget for a loan payment on a low income. You will learn how to calculate what you can truly afford, trim expenses without sacrificing essentials, communicate with lenders when money is tight, and use tools like loan connection services to find better terms. By the end, you will have a clear framework you can apply immediately, regardless of how much you earn.
Start With a Brutally Honest Income and Expense Audit
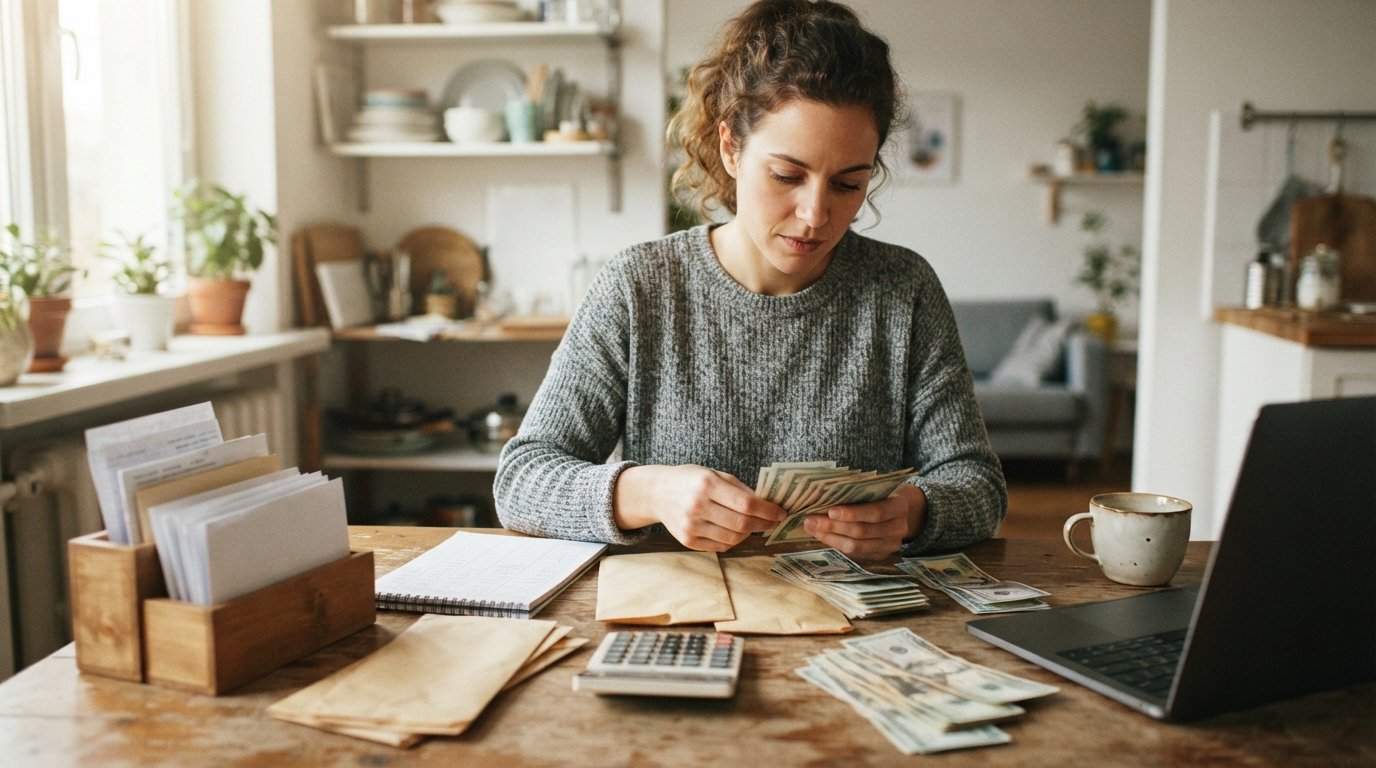
Before you can budget for any loan payment, you need to know exactly where your money goes. Most people underestimate their spending by 10 to 20 percent. On a low income, that margin matters enormously. Grab your bank statements from the last two months, a notebook, and a calculator. List every single source of income: paychecks, side gigs, government benefits, child support, and any irregular earnings. Then list every expense, from rent and utilities to subscriptions and impulse purchases.
This audit serves two purposes. First, it reveals your true discretionary income, which is the money left after essential bills. Second, it exposes spending leaks you can plug immediately. You might discover you are spending $60 monthly on streaming services you rarely use, or $80 on takeout when cooking at home could cut that in half. Those small amounts add up fast and can fund a loan payment.
Once you have your numbers, categorize expenses into three groups: fixed (rent, insurance, loan payments), variable but essential (groceries, utilities, transportation), and discretionary (entertainment, dining out, hobbies). This framework helps you see where you have flexibility. Your loan payment should come from the fixed category, but if you are short, you can temporarily pull from discretionary spending.
For a deeper dive into calculating exactly what your loan will cost each month, including interest and fees, a reliable resource is available. Understanding the math behind your payment helps you negotiate better terms and avoid surprises. You can read our guide on how to calculate loan payments to see the formulas and examples that apply to your situation.
After the audit, create a zero-based budget. This means every dollar gets assigned a job: rent, food, loan payment, savings, and so on. If your income is $2,000 monthly and your expenses total $2,000, you have a balanced budget. If expenses exceed income, you must cut or earn more. There is no third option. This step is non-negotiable for anyone serious about how to budget for a loan payment on a low income.
Determine a Realistic Loan Payment You Can Sustain
Many people make the mistake of agreeing to a loan payment that eats up 30 percent or more of their take-home pay. On a low income, that is a recipe for default. Financial experts generally recommend keeping total debt payments (including your new loan) below 36 percent of gross monthly income. If you earn $2,500 gross monthly, your total debt payments should stay under $900. That includes credit cards, car loans, and personal loans.
But what if your existing debt already exceeds that threshold? Then you need to either reduce other debts first or find a loan with a longer term and lower monthly payment. A longer term means you pay more interest overall, but it can make the difference between affording the payment and missing it. The goal is sustainability, not speed.
Use this simple framework to determine your maximum affordable loan payment:
- Calculate your net monthly income (take-home pay after taxes and deductions).
- Subtract all essential expenses: housing, utilities, food, transportation, insurance, and minimum debt payments.
- Subtract a small buffer for irregular expenses (car repairs, medical copays). Aim for at least $100 monthly.
- The remaining amount is your maximum loan payment. If it is negative, you cannot afford a new loan right now.
Once you know your maximum, do not automatically borrow up to that limit. Leave room for error. Life throws unexpected costs at you constantly. A payment that feels comfortable in a good month might be impossible in a bad month. Aim for a payment that is 10 to 15 percent below your calculated maximum. That cushion protects you when hours get cut or an emergency arises.
If the numbers show you cannot afford any loan payment right now, that is valuable information. It means you should focus on increasing income, reducing expenses, or finding a loan with a longer term that lowers the monthly obligation. It also means you should avoid payday loans with balloon payments that come due all at once. Those products are designed for people who cannot afford them, and they often lead to rollovers and escalating fees.
Build a Payment-First Budget Strategy
Most people budget by paying bills as they come due and hoping something is left for savings and loan payments. That approach fails on a low income because the money runs out before the important stuff gets funded. Instead, flip the script. Treat your loan payment like rent: it is due on a specific day, and you set aside money for it before anything else.
This is called a payment-first budget. As soon as you receive income, immediately allocate the loan payment to a separate account or envelope. If you get paid biweekly, split the payment in half and set aside each half. By the time the due date arrives, the money is already there. You never have to scramble or choose between the loan and groceries.
Here is how to implement this system in five steps:
- Identify your loan due date and the exact payment amount.
- Divide the payment by the number of paychecks you receive before the due date.
- Open a separate savings account or use a cash envelope labeled "Loan Payment."
- Within 24 hours of each paycheck, transfer or deposit the divided amount.
- Pay the loan from that dedicated account on or before the due date.
This method works because it removes emotion and willpower from the equation. You are not deciding each month whether you can afford the payment. You already decided, and the system automates the behavior. Even if you earn minimum wage, setting aside $20 per week is doable if you prioritize it.
Pair this with a bill calendar. Write down every due date for every bill, including your loan. Seeing the full month at a glance helps you anticipate tight weeks. If you notice that rent and your loan payment fall in the same week, consider calling your lender to change the due date. Many lenders allow this once or twice per year at no cost. Aligning due dates with your cash flow reduces the risk of overdrafts and late fees.
Cut Expenses Without Cutting Quality of Life
When money is tight, the instinct is to slash everything enjoyable. That approach backfires because it leads to burnout and rebound spending. Instead, focus on strategic cuts that free up cash without making you miserable. The goal is to find $50 to $200 monthly that you can redirect toward your loan payment or savings buffer.
Start with recurring subscriptions. Audit every automatic charge on your bank statement. Cancel anything you have not used in the past 30 days. Next, negotiate recurring bills. Call your internet provider, cell phone company, and insurance agent. Ask about loyalty discounts, lower-tier plans, or promotional rates. A 15-minute call can save $20 to $40 monthly. That is $240 to $480 per year, enough to cover several loan payments.
Look at your grocery spending. Plan meals around sales, buy store brands, and reduce food waste. The average American household throws away $1,500 in food annually. Cutting that waste in half frees up $60 monthly. Transportation is another area. Can you carpool, use public transit, or combine errands to save gas? Even $30 monthly helps.
Housing is usually the largest expense, but moving is not always practical or cheap. However, you might be able to negotiate rent, take in a roommate, or refinance your mortgage if you own. Utility costs can drop with simple habits: lower the thermostat, use LED bulbs, and unplug electronics when not in use. These changes add up.
Do not cut essentials like health insurance or sufficient food. That creates bigger problems later. Focus on discretionary and semi-discretionary categories. The goal is sustainable frugality, not deprivation.
Communicate With Your Lender Before You Miss a Payment
Many people avoid calling their lender when they realize they cannot make a payment. That is the worst thing you can do. Lenders prefer communication over silence because it gives them options to help you. Most lenders offer hardship programs, temporary forbearance, or modified payment plans. These options are not automatic. You must ask.
Call your lender as soon as you know a payment will be late or short. Explain your situation briefly and ask what options are available. Common solutions include:
- Extending the loan term to lower monthly payments.
- Temporarily reducing or pausing payments for a set period.
- Waiving late fees for one-time hardships.
- Changing the due date to align with your pay schedule.
- Refinancing the loan at a lower interest rate.
Be honest and specific. Instead of saying "I cannot pay," say "I lost 10 hours of work this month and can only pay half. Can we split the payment over two weeks?" Specific requests are easier to approve. Also, get any agreement in writing, including the new due date and amount. Verbal promises mean nothing if the representative leaves the company.
If your lender refuses to work with you, consider a debt management plan through a nonprofit credit counseling agency. These agencies can negotiate lower payments and interest rates on your behalf. They charge small fees, but the savings often outweigh the cost. Avoid for-profit debt settlement companies that promise to erase debt for pennies on the dollar. They often damage your credit and leave you worse off.
Explore Loan Connection Services for Better Terms
If your current loan payment is unaffordable, one solution is to replace it with a better loan. That means finding a lower interest rate, a longer term, or both. Traditional banks often reject applicants with low income or imperfect credit. That is where loan connection services come in. These platforms submit your information to a network of lenders who compete for your business. You receive multiple offers and choose the one with the most manageable payment.
One option worth exploring is FreeQuotes.Loans, an online loan comparison and connection service that helps individuals in the United States find personalized loan offers from a network of third-party lenders. The platform is designed for people seeking payday loans, personal loans, or installment loans, often for urgent needs like medical expenses or car repairs, including those with less-than-perfect credit. Users submit a single request and may receive multiple offers to compare.
When evaluating offers, focus on the monthly payment, not just the interest rate. A loan with a slightly higher rate but a much longer term might have a lower monthly payment, which is what you need on a low income. However, read the fine print. Some loans have prepayment penalties or balloon payments that come due at the end. Avoid those if possible.
Also, check whether the lender reports to credit bureaus. On-time payments can rebuild your credit, which opens doors to better loan terms in the future. If you can afford the payment and the terms are fair, a new loan that replaces an old one can be a smart move. Just avoid taking on additional debt beyond what you need to consolidate or replace.
Increase Income With Side Gigs and Negotiation
Cutting expenses has a floor. You can only reduce so much before you hit essentials. Increasing income has no ceiling. Even an extra $200 monthly can transform your budget and make your loan payment comfortable. On a low income, you likely have skills that others will pay for, even if you do not realize it.
Consider these income-boosting options:
- Freelancing: writing, graphic design, virtual assistance, or tutoring.
- Gig work: rideshare driving, food delivery, or task-based apps.
- Selling unused items: electronics, clothing, furniture, or collectibles.
- Pet sitting or dog walking for neighbors and friends.
- Seasonal or part-time retail, warehouse, or customer service jobs.
Even 5 to 10 hours weekly at $15 per hour adds $300 to $600 monthly. That is enough to cover most loan payments and build an emergency fund. The key is to commit to a set schedule so the extra work does not burn you out. Treat the side gig like a second job with fixed hours.
Also, negotiate your current job. If you have been reliable and taken on extra responsibilities, ask for a raise. Come prepared with data on your contributions and market rates for your role. A $1 per hour raise equals about $160 monthly before taxes. That is a meaningful boost. If a raise is not possible, ask for more hours or a shift differential.
Protect Your Progress With an Emergency Fund
One unplanned expense, a car repair, a medical bill, a broken phone, can derail your entire budget and force you to miss a loan payment. That is why building even a small emergency fund is critical. Aim for $500 to start. That covers most common emergencies and keeps you from using credit cards or payday loans to fill the gap.
Build your fund alongside your loan payments, not after. Even $10 per week adds up to $520 in a year. Put it in a separate savings account that you do not touch for non-emergencies. If you have to use it, replenish it as soon as possible. The peace of mind is worth the small sacrifice.
Once you have $500, aim for one month of essential expenses. That is typically $1,000 to $2,000 on a low income. It sounds daunting, but slow and steady wins. Automate a transfer every payday, even if it is just $5. You will be surprised how quickly it grows when you do not see the money in your checking account.
With an emergency fund in place, you can handle life's surprises without borrowing more or missing payments. That stability improves your credit score and reduces financial stress. It also gives you leverage to negotiate better terms with lenders because you are not desperate.
Putting It All Together
Budgeting for a loan payment on a low income is not about deprivation. It is about intentionality. You start with a clear picture of your income and expenses. You determine a payment you can sustain without sacrificing essentials. You build a system that sets aside money before you can spend it. You cut costs strategically, communicate with lenders proactively, and explore better loan options through connection services. And you protect your progress with an emergency fund.
None of these steps require a high income. They require discipline and a willingness to ask for help when needed. If you are struggling, reach out to your lender, a credit counselor, or a loan connection service. You are not alone, and there are options available. The most important thing is to act before a missed payment turns into a financial crisis.
Remember that short-term loans are not a long-term financial solution. They are a tool for bridging gaps, not for funding a lifestyle. Use them responsibly, pay them off as quickly as your budget allows, and keep building toward a more stable future. With the right plan, you can manage your loan payment and still sleep at night.