
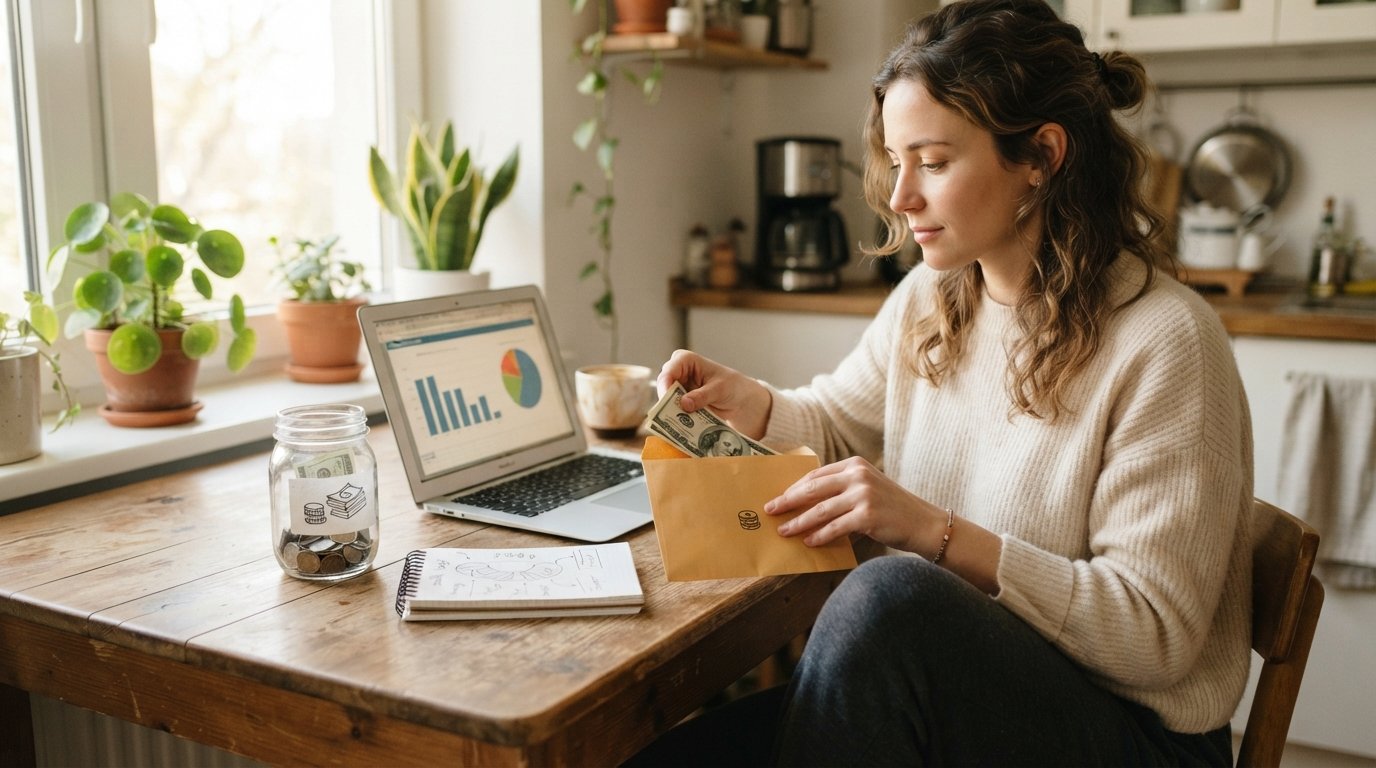
How to Budget for Unexpected Expenses Without a Loan
Master how to budget for unexpected expenses without a loan. Build a buffer, use sinking funds, and triage bills. For loan options, call (833)-501-3363.
By Levi Parker
A surprise car repair, a sudden medical bill, or a broken appliance can wreck even a carefully planned budget. The instinct is often to reach for credit, but there is a better way. Learning how to budget for unexpected expenses without a loan puts you in control, reduces stress, and keeps you out of debt. This guide walks you through building a buffer on a tight income, using sinking funds for irregular costs, triaging a surprise bill when savings fall short, and knowing when a loan connection service might be the practical next step.
Build a Small Buffer Fund on a Tight Income
You do not need a fully funded emergency fund to start. Even $500 can cover many common surprises, like a tire replacement or a urgent dental visit. The key is to start small and stay consistent. Many people feel that saving is impossible when money is already tight. However, small, automated transfers can make a big difference over time. Treat your buffer fund as a non-negotiable bill, just like rent or utilities.
Here is a simple framework to build a buffer on a tight income:
- Set a realistic target. Aim for $500 first, then $1,000. Break it down into weekly or biweekly savings goals. For example, saving $20 per week gets you to $1,040 in a year.
- Automate the savings. Set up an automatic transfer from your checking to a separate savings account on payday. Even $10 or $25 per paycheck adds up.
- Use windfalls wisely. Tax refunds, bonuses, or gifts should go straight to your buffer fund before you spend them elsewhere.
- Trim small expenses temporarily. Cut one subscription or reduce dining out by one meal per week, and direct that money to savings.
This approach works because it does not require a major lifestyle overhaul. It builds a habit and a safety net simultaneously. Once you have a buffer, you can handle small emergencies without borrowing. For larger unexpected expenses, you may need additional strategies, which we cover next.
Use Sinking Funds for Predictable Irregular Costs
Not all unexpected expenses are truly unexpected. Car maintenance, insurance premiums, and holiday gifts are irregular but predictable. A sinking fund is a savings account earmarked for a specific upcoming expense. By setting aside a small amount each month, you spread the cost over time and avoid a financial shock when the bill arrives.
For example, if you know your car insurance is $600 every six months, save $100 per month in a sinking fund. When the bill comes, you have the money ready. Similarly, set aside $50 per month for car maintenance, and you will have $600 for repairs or new tires when needed. This method turns potential emergencies into planned expenses.
Sinking funds are especially helpful for people with tight budgets because they break large costs into manageable chunks. They also reduce reliance on credit cards or loans. To set up a sinking fund, list your irregular expenses for the year, divide each by the number of months until due, and automate transfers to separate savings buckets. Many banks allow you to create multiple sub-accounts for different goals.
Triage a Surprise Bill When Savings Are Not Enough
Even with a buffer and sinking funds, a major unexpected expense can exceed your savings. When that happens, do not panic. Triage the situation by following a step-by-step approach to minimize financial damage.
- Assess the urgency. Determine if the expense is truly urgent or can be delayed. For example, a necessary car repair to get to work is urgent; a discretionary purchase is not.
- Negotiate with the provider. Ask for a payment plan, a discount for paying in full, or a deferred due date. Many medical offices and service providers offer flexible options.
- Use your buffer first. If you have a buffer fund, use it to cover part of the bill. Then replenish it as soon as possible.
- Consider a side gig or temporary income boost. Pick up extra hours, freelance, or sell unused items to cover the gap.
- Explore loan alternatives cautiously. If all else fails, a short-term loan connection service may be an option, but only after exploring other avenues.
Triage is about making deliberate choices rather than reacting out of fear. By prioritizing urgent needs and communicating with creditors, you can often buy time and reduce pressure. Remember that borrowing should be a last resort, not the first response.
When a Short Term Loan Connection Service May Be the Practical Next Step
Despite your best efforts, sometimes you face a genuine emergency that exceeds your available funds and cannot be postponed. In such cases, a short-term loan connection service like LendersCashLoan can help you explore options. LendersCashLoan is not a direct lender; it connects you with a network of third-party lenders who may offer payday loans, installment loans, or personal loans. The process is online, fast, and designed for people with less-than-perfect credit.
Before considering this step, ensure you have exhausted other possibilities: negotiating bills, using savings, borrowing from friends or family, or accessing community resources. If you do decide to seek a loan, use a connection service to compare offers from multiple lenders. You can learn more about how a loan distribution network helps you get funds fast and make an informed decision. Another option is to visit ExpressCash for short-term loan options, but always review terms carefully.
When using a loan connection service, keep these points in mind: understand the APR and fees, borrow only what you need, and have a repayment plan. Short-term loans are not a long-term solution and should be used sparingly. Responsible borrowing means knowing you can repay on time to avoid further financial strain.
Putting It All Together: A Budget That Absorbs Shocks
Budgeting for unexpected expenses without a loan is about building layers of protection. Start with a small buffer fund, then add sinking funds for predictable irregular costs. When a surprise bill hits, triage it systematically. Only consider a loan as a last resort, and use a connection service to find the best terms if needed.
This approach gives you confidence and financial stability. It also reduces reliance on credit and helps you avoid a cycle of debt. Remember that every small step counts: automating $10 per week, negotiating a bill, or setting up a sinking fund can make a significant difference over time.
By following these strategies, you can handle unexpected expenses without a loan and build a more resilient financial future. Start today by reviewing your budget and identifying one action you can take to strengthen your safety net.