
How to Decide if an Emergency Loan Is Right for You
Use a step-by-step framework to decide if an emergency loan is right for you, from urgency checks to comparing no-obligation offers.
By Yara Griffin
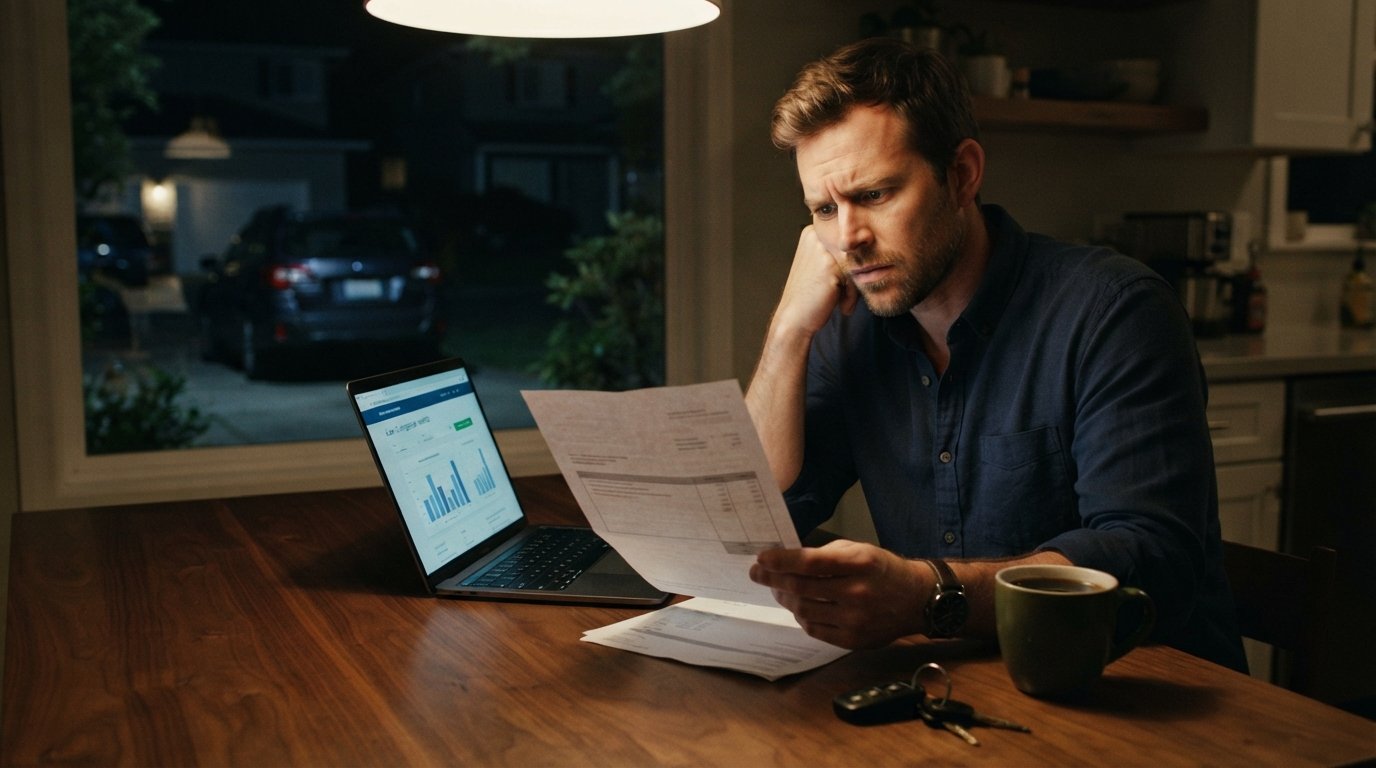
Your car breaks down on a Tuesday morning, and the repair shop quotes you $1,200 by noon. Your rent is due Friday, and your paycheck does not arrive until next week. The pressure to act fast can feel overwhelming. In moments like these, an emergency loan can look like the only lifeline in sight. But signing for fast cash without a clear framework can turn a short-term crunch into a long-term financial burden. Knowing how to decide if an emergency loan is the right choice means separating true urgency from panic, weighing cheaper alternatives, and understanding exactly what you are committing to before you click submit.
This guide walks you through a practical decision process, from the questions you should ask about the expense itself to the alternatives worth exploring first, and finally to the situations where a short-term loan genuinely serves as a reasonable bridge rather than a trap. You will also see how a loan connection service fits into the picture, so you can compare offers with no obligation and make a decision grounded in facts, not fear.
Start With the Expense: Is It Truly Urgent, Temporary, and Unavoidable?
Before you look at a single loan offer, examine the expense itself. Not every bill that feels urgent is actually urgent in the way that justifies borrowing at a high cost. A useful first step is to run the expense through three filters: urgency, duration, and inevitability. If the expense fails any one of these tests, you may have more breathing room than you think.
Urgency asks whether the expense must be handled within days or whether it can wait weeks. A missed rent payment can lead to late fees and eventually eviction proceedings, which makes it urgent. A medical bill, by contrast, often has billing cycles and payment plan options that make it far less time-sensitive than the due date suggests. Duration asks whether the expense is a one-time hit or the start of an ongoing obligation. Replacing a broken water heater is temporary and finite; a new monthly medical treatment is ongoing and may require a different solution than a one-time loan. Inevitability asks whether the expense is truly unavoidable or whether it is a want dressed up as a need. A necessary engine repair is unavoidable; an upgrade to a newer car is not.
Run your situation through a quick checklist to see how many of these statements apply:
- The expense must be paid within the next few days to avoid serious consequences.
- The cost is a one-time event, not a recurring monthly obligation.
- You have no savings, no available credit, and no realistic way to cover it before the deadline.
- Failing to pay would cause harm that costs more than the loan itself (eviction, vehicle repossession, utility shutoff).
If you can check most of these boxes, the expense may justify exploring emergency funding. If you cannot, take a breath and look for alternatives first. Many people rush into borrowing for expenses that could have been handled with a phone call, a payment plan, or a short delay. The goal is not to talk you out of a loan, but to make sure the loan is solving a real problem rather than masking a manageable one.
Weigh the Alternatives Before You Borrow
An emergency loan is one tool among many, and it is rarely the cheapest one. Before you commit to any borrowing, spend a day or two exploring the options that do not involve interest or fees. Even in urgent situations, a few phone calls can uncover solutions that save you hundreds of dollars.
Ask for a payment plan. Hospitals, utility companies, auto repair shops, and even landlords often have flexibility they do not advertise. A direct conversation about your situation can yield a split payment, a deferred due date, or a reduced amount. It costs nothing to ask, and many businesses prefer a payment plan over the risk of nonpayment.
Tap into family and community resources. A short-term loan from a family member or a friend, even one you repay in installments, is almost always cheaper than a commercial loan. Community organizations, religious institutions, and local charities sometimes offer emergency assistance grants for rent, utilities, or medical bills. Local 211 services can connect you with programs in your area.
Use existing credit carefully. If you have a credit card with available balance, a small purchase may be cheaper than a payday loan, provided you can repay it before interest compounds. A credit union personal loan or a small line of credit may also carry a lower annual percentage rate (APR) than short-term alternatives. Just be honest with yourself about whether you can repay the balance quickly.
Negotiate the expense itself. Medical bills are frequently negotiable, especially if you offer a lump-sum payment or ask for a financial assistance review. Auto repair quotes can sometimes be reduced by getting a second opinion or asking for aftermarket parts. Even a modest reduction can shrink the amount you need to borrow.
If none of these alternatives pan out and the deadline is real, then it is time to evaluate emergency loan options with clear eyes. This is where understanding the lending landscape matters, and a resource like Emergency Loans Explained: Fast Cash for Urgent Needs can help you see how the process works before you share any personal information.
When a Short-Term Loan Is a Reasonable Bridge
A short-term loan can be a rational choice when it bridges a genuine, temporary gap between an urgent expense and your next reliable inflow of cash. The key word is temporary. If you know with confidence that you will have the money to repay the loan within a defined window, and the cost of borrowing is less than the cost of not paying the expense, a loan can make financial sense.
Consider a scenario: you need $800 for a necessary car repair, and you are expecting a $1,500 bonus in three weeks. The repair keeps you employed, and the bonus is reliable. A short-term loan that you repay in full on time may cost you a fee or interest, but it preserves your income and avoids the much larger cost of losing your job. In this case, the loan is a bridge, not a habit.
Here is a simple framework for judging whether you are in bridge territory or trap territory:
- You have a specific repayment source. You know exactly where the money will come from and when it will arrive.
- The repayment timeline is short and realistic. You can repay the loan within one or two pay cycles without borrowing again.
- The total cost of borrowing is manageable. You understand the APR, fees, and total repayment amount, and it does not consume money you need for essentials.
- The loan solves the problem permanently. After repayment, the expense is behind you, not rolling into another month.
If you cannot satisfy these conditions, the loan may be a trap. Rolling over a payday loan, borrowing to pay another loan, or using a loan to cover recurring monthly expenses are warning signs. Short-term loans are not designed to solve long-term financial shortfalls, and using them that way can create a cycle that is very hard to escape. Honest self-assessment at this stage is the most important step in the entire decision.
Understand the True Cost and the Risks
The sticker price of a loan is rarely the full story. Before you accept any offer, calculate the total repayment amount, not just the monthly or per-paycheck payment. A loan with a low payment over many months can cost far more than a loan with a higher payment over a short period. Look at the APR, which expresses the cost of credit as a yearly rate, and compare it across offers.
Watch for fees that are easy to overlook: origination fees, late fees, returned payment fees, and prepayment penalties. Read the loan agreement carefully, especially the sections on repayment terms, default, and collection practices. If the lender is not transparent about these details, that is a red flag. Reputable lenders disclose the full cost of the loan before you sign.
Also consider the risk to your credit and your bank account. Missing a payment can damage your credit score, and some lenders require automatic debits that can overdraw your account if funds are not available. A loan that solves one emergency can create another if repayment is not carefully planned. The Consumer Financial Protection Bureau recommends comparing offers and understanding your rights before borrowing, and that advice applies to every loan type, from payday to installment.
If you have less-than-perfect credit, you may face higher rates and fewer options, but you still have choices. A loan connection service like AdvanceCash can help you submit a single request and review offers from multiple lenders, which makes comparison easier than visiting lenders one by one. Just remember that a connection service is not a lender; it does not make credit decisions or fund loans directly. The offers come from third-party lenders, and you are responsible for evaluating them.
Use a No-Obligation Request to Compare Offers
One of the safest ways to explore emergency loan options is to use a service that lets you request offers without committing. LendersCashLoan operates as a digital loan connection service, not a direct lender, and it allows you to submit a single online request to a network of independent third-party lenders. The request typically takes under five minutes, and there is no cost or obligation to review the offers that come back.
This approach has several practical advantages when you are deciding whether an emergency loan is right for you. First, it lets you see real numbers, including APRs, fees, and repayment terms, rather than guessing. Second, it saves time, which matters when a deadline is looming. Third, it keeps you in control: you can compare offers side by side and decline any or all of them without penalty.
Here is how the process generally works:
- You fill out a short online request with basic information about yourself and the amount you need.
- Your request is shared with lenders in the network who may be able to serve you.
- You review any offers that come back, including the terms and costs.
- You choose whether to proceed with an offer, and you are never obligated to accept.
Before you submit a request, gather the documents you will likely need: a valid ID, proof of income, and a bank account for deposits and repayments. Having these ready speeds up the process. Also, be aware that submitting a request may involve a credit check, and the terms of that check should be disclosed to you. LendersCashLoan emphasizes transparency and uses 256-bit SSL encryption to protect your information, but you should still read the disclosures carefully.
Match the Loan Type to Your Situation
Emergency loans come in several forms, and the right one depends on your repayment ability and the size of the expense. A payday loan is typically a small, short-term loan repaid on your next payday. It can be fast, but the APR is often very high, and rolling it over is expensive. An installment loan lets you repay in fixed payments over a longer period, which can make the monthly cost more manageable, though you may pay more interest overall. A personal loan from a bank or credit union may offer lower rates if you qualify, but approval can take longer.
If you need a small amount quickly and you are confident you can repay it on your next payday, a payday loan may be an option, but only if you can avoid rollover. If you need a larger amount and can handle fixed monthly payments, an installment loan may fit better. If you have good credit and a bit more time, a personal loan from a traditional institution may be the cheapest route. The key is to match the loan's structure to your actual cash flow, not to pick the first offer that appears.
LendersCashLoan's network includes lenders who may offer payday loans, personal loans, and installment loans, with amounts typically ranging from $100 to $5,000. The service welcomes applicants with less-than-perfect credit who meet income criteria, which broadens the options for people who might be turned away elsewhere. But again, the service is a connection platform, not a lender, and the final decision rests with the third-party lender and with you.
Know the Warning Signs of a Loan Trap
Even with careful planning, some loans are designed in ways that make repayment difficult. Recognizing the warning signs can protect you from a cycle of debt. Be cautious if the lender pressures you to act immediately, discourages you from reading the agreement, or does not clearly disclose the APR and fees. Be wary of loans that require you to surrender your car title or provide post-dated checks as a condition of borrowing. These arrangements can put your assets at risk.
Another red flag is a repayment schedule that does not match your income. If the loan payment is due before your paycheck arrives, you may be set up for a late fee or a rollover. Similarly, if the only way to repay the loan is to borrow again, you are in a trap. A legitimate lender wants to be repaid, but a predatory lender profits from repeated borrowing. Trust your instincts: if something feels off, walk away.
Finally, remember that short-term loans are not a long-term financial solution. They are a tool for bridging a temporary gap. If you find yourself needing them repeatedly, that is a signal to address the underlying budget issue, whether by increasing income, reducing expenses, or seeking credit counseling. Nonprofit credit counseling agencies can help you build a plan, often at low or no cost.
A Decision Framework You Can Use Today
When you are in the middle of a financial emergency, it helps to have a simple, repeatable process. Here is a step-by-step framework that pulls together the guidance above:
- Pause and assess. Write down the expense, the deadline, and the consequence of not paying. Confirm that it is truly urgent, temporary, and unavoidable.
- Exhaust cheaper alternatives. Call the creditor, ask for a payment plan, reach out to family, check community resources, and consider existing credit.
- Calculate the cost of borrowing. If alternatives fail, gather loan offers and compare APRs, fees, and total repayment amounts.
- Check your repayment plan. Confirm that you have a specific, reliable source of repayment and that the timeline is short and realistic.
- Use a no-obligation request to compare. Submit a request through a connection service like LendersCashLoan to see real offers without committing.
- Read the agreement and decide. Review the terms, watch for red flags, and accept only if the loan is a bridge, not a trap.
This framework is not a guarantee, but it slows down the decision enough to prevent panic borrowing. It also gives you a record of your reasoning, which can be useful if you need to explain the decision to a partner or financial advisor. The goal is to make a choice you will not regret in three months.
Final Thoughts: Borrow With Clarity, Not Fear
Deciding whether an emergency loan is right for you comes down to honesty and preparation. Be honest about whether the expense is truly urgent and whether you can repay the loan on time. Prepare by exploring alternatives, comparing offers, and reading the fine print. A loan can be a useful bridge when it is used for a genuine, temporary gap, but it becomes a trap when it is used to cover ongoing shortfalls or when the terms are not fully understood.
If you do decide to explore emergency loan options, use a no-obligation request to see what is available. LendersCashLoan connects you with third-party lenders who may offer payday, personal, or installment loans, and the process is designed to be fast and transparent. You remain in control of the decision, and you can decline any offer that does not fit your situation. With the right framework and a clear head, you can handle an emergency without letting it turn into a long-term financial problem.