
How to Use a Loan for Unexpected Car Transmission Repair
A failed transmission can cost thousands. Learn how to use a loan for unexpected car transmission repair and protect your budget. Call 8335013363 for guidance.
By Sophie Hayes
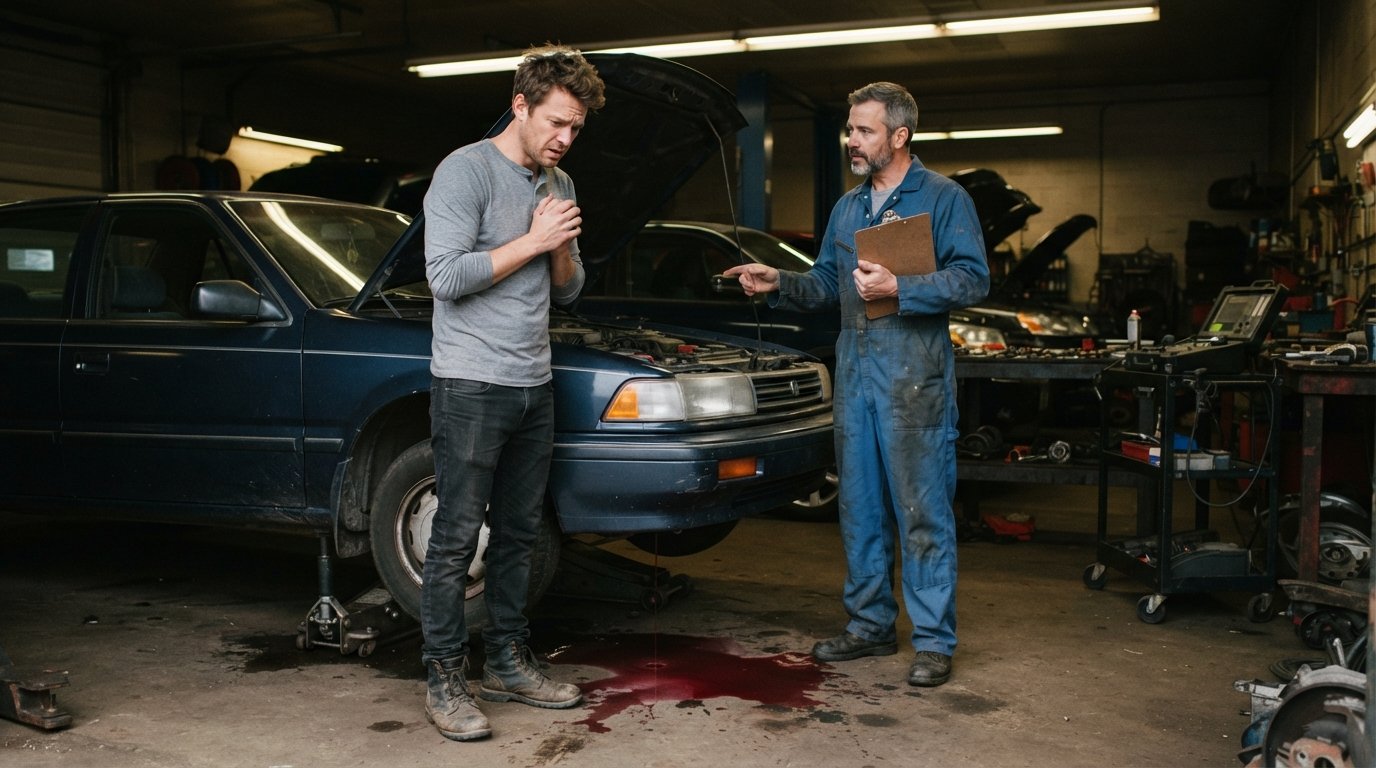
A grinding noise, a sudden loss of power, or a puddle of reddish fluid under your car can turn an ordinary morning into a financial emergency. A transmission repair often costs between $1,800 and $5,000 or more, and it is rarely something you can postpone. You need your vehicle to get to work, take your kids to school, and handle daily errands. When savings fall short, a loan can bridge the gap, but only if you approach it strategically. This guide walks you through how to use a loan for unexpected car transmission repair without creating a bigger financial problem down the road.
Why Transmission Repairs Catch Drivers Off Guard
Transmissions fail with little warning. Unlike brakes, which often squeal before they give out, a transmission can shift smoothly one day and slip the next. The complexity of modern automatic and continuously variable transmissions means that even a minor internal failure can require thousands of dollars in parts and labor. Many drivers have no dedicated repair fund, and insurance typically does not cover mechanical breakdowns.
That combination of high cost and zero warning is what makes transmission repairs one of the most common reasons people seek emergency financing. The question is not whether you should fix the car, because you usually have no choice. The question is how to pay for it without derailing your entire budget.
First Steps: Confirm the Diagnosis and Get Written Estimates
Before you apply for any loan, make sure you know what you are actually paying for. Some symptoms that look like transmission failure, such as rough shifting or a check engine light, can stem from a faulty sensor, low fluid, or a software issue. A second opinion from an independent transmission shop can save you thousands.
Ask each shop for a written estimate that separates parts, labor, taxes, and any diagnostic fees. If a full rebuild is recommended, ask whether a used or remanufactured transmission is a safe alternative. Once you have two or three quotes in hand, you will know your target loan amount. Borrowing more than you need increases interest costs and makes repayment harder.
How to Use a Loan for Unexpected Car Transmission Repair: A Step-by-Step Approach
Using a loan wisely means matching the loan type to your situation, borrowing only what the repair requires, and having a clear repayment plan before you sign. The following steps outline a practical process that works whether you have excellent credit or a less-than-perfect credit history.
- Determine the exact repair cost. Use your written estimates to set a firm number, then add a small buffer of 10 to 15 percent for surprises the mechanic may find once the transmission is opened.
- Choose the right loan type. Personal loans and installment loans offer predictable monthly payments, while payday loans and cash advances provide fast cash but carry much higher fees. Match the loan to how quickly you can repay.
- Check your eligibility and gather documents. Most lenders want proof of income, a valid ID, an active bank account, and sometimes a phone number or email address. Knowing this upfront speeds up the process.
- Compare offers side by side. Look at the APR, origination fees, repayment term, and total cost, not just the monthly payment. A lower monthly payment over a longer term can cost far more overall.
- Pay the shop directly when possible. Some lenders can disburse funds directly to the repair facility, which reduces the risk of spending the money on something else.
Following these steps keeps the process organized and helps you avoid the trap of accepting the first offer that appears. Speed matters when your car is in the shop, but a few extra minutes of comparison can save you hundreds of dollars.
Loan Options for Transmission Repairs
Not all emergency loans are created equal. The right choice depends on your credit profile, income, and how soon you can repay. Here is a breakdown of the most common options drivers use for transmission repairs.
- Personal installment loans: Fixed monthly payments over 6 to 36 months, often with lower APRs than payday products. Best for repairs you can pay off over several months.
- Payday loans and cash advances: Short-term, high-fee loans typically due on your next payday. Useful only if you can repay quickly and in full.
- Credit union or bank personal loans: Competitive rates for members with good credit, but approval can take longer than online options.
- Credit card cash advances: Convenient but expensive, with immediate interest and transaction fees.
- Buy-now-pay-later or shop financing: Some repair chains offer in-house payment plans, though terms vary widely.
If you have bad credit, repossession, or bankruptcy in your past, you may still qualify for an installment loan or a short-term personal loan through a connection service. The key is to focus on the total cost, not just approval. A loan that is easy to get but impossible to repay will only compound the problem.
How Loan Connection Services Simplify the Process
Rather than applying to dozens of lenders one by one, you can submit a single request and receive multiple offers from a network of third-party lenders. This approach saves time and lets you compare rates, terms, and funding speeds in one place. It is especially helpful when your car is undriveable and you need a decision within hours, not days.
One example of this model is FreeQuotes.Loans, an online loan comparison and connection service that helps individuals in the United States find personalized loan offers from a network of third-party lenders. The platform is designed for people seeking payday loans, personal loans, or installment loans, often for urgent needs like medical expenses or car repairs, including those with less-than-perfect credit. Users submit a single request and can receive offers from multiple lenders, which makes it easier to find a repayment plan that fits your budget.
If you are exploring this route, our guide on emergency personal loans for fast cash explains how the request process works and what lenders typically look for. Understanding those details before you apply can improve your chances of getting a usable offer quickly.
Qualifying With Less-Than-Perfect Credit
Many drivers assume that a transmission emergency means they are out of options if their credit score is low. That is not necessarily true. Lenders in the short-term and installment loan space often consider income, employment stability, and banking history alongside credit scores. Some specialize in working with borrowers who have bad credit, past repossessions, or even a bankruptcy discharge.
To strengthen your application, gather recent pay stubs, bank statements, and a valid government ID before you apply. Be honest about your income and existing debts. If a lender asks for a reference or proof of address, provide it promptly. The faster you respond, the faster you can receive funds and get your car back on the road.
Repayment Strategies That Protect Your Budget
The repair is urgent, but the repayment is where most people get into trouble. Before accepting any loan, calculate how much you can realistically pay each month after covering rent, utilities, food, and other essentials. If the monthly payment leaves you with no margin, choose a longer term or a smaller loan amount.
Set up automatic payments if the lender offers them, and mark the due dates on your calendar. If you receive a windfall, such as a tax refund or bonus, consider paying down the loan early to reduce interest. If you cannot make a payment, contact the lender immediately. Many will work with you on a modified schedule rather than sending the account to collections.
Avoiding Common Mistakes
The biggest mistake borrowers make is accepting the first offer without comparing costs. A difference of just a few percentage points in APR can add hundreds of dollars to the total you repay. Another common error is borrowing more than the repair costs and spending the extra on unrelated expenses.
It also helps to read the fine print. Look for prepayment penalties, late fees, and whether the lender reports to credit bureaus. Responsible borrowing now can actually help your credit if you make on-time payments. Reckless borrowing can damage it further and make the next emergency even harder to handle.
When a Loan Makes Sense and When It Does Not
A loan is a reasonable tool when the repair is necessary, the cost is known, and you have a realistic repayment plan. It is a poor choice when the repair is optional, when you are already overwhelmed by debt, or when the only available offers carry APRs that will trap you in a cycle of borrowing.
If your transmission fails and you have no savings, a short-term personal loan or installment loan can be the difference between keeping your job and losing it. The key is to treat the loan as a bridge, not a solution. Once the car is fixed, focus on rebuilding your emergency fund so the next surprise does not require borrowing.
Unexpected car repairs are stressful, but they do not have to be financially devastating. By confirming the diagnosis, comparing offers, and choosing a loan you can actually repay, you can handle a transmission emergency without sacrificing your long-term stability. If you are ready to explore your options, start by checking your eligibility with a trusted connection service and see what offers are available for your situation.