
How to Use a Personal Loan for Moving Costs After Eviction Notice
A personal loan can cover deposits and moving costs after an eviction notice. Call (833)-501-3363 to explore loan options and plan repayment.
By Levi Parker
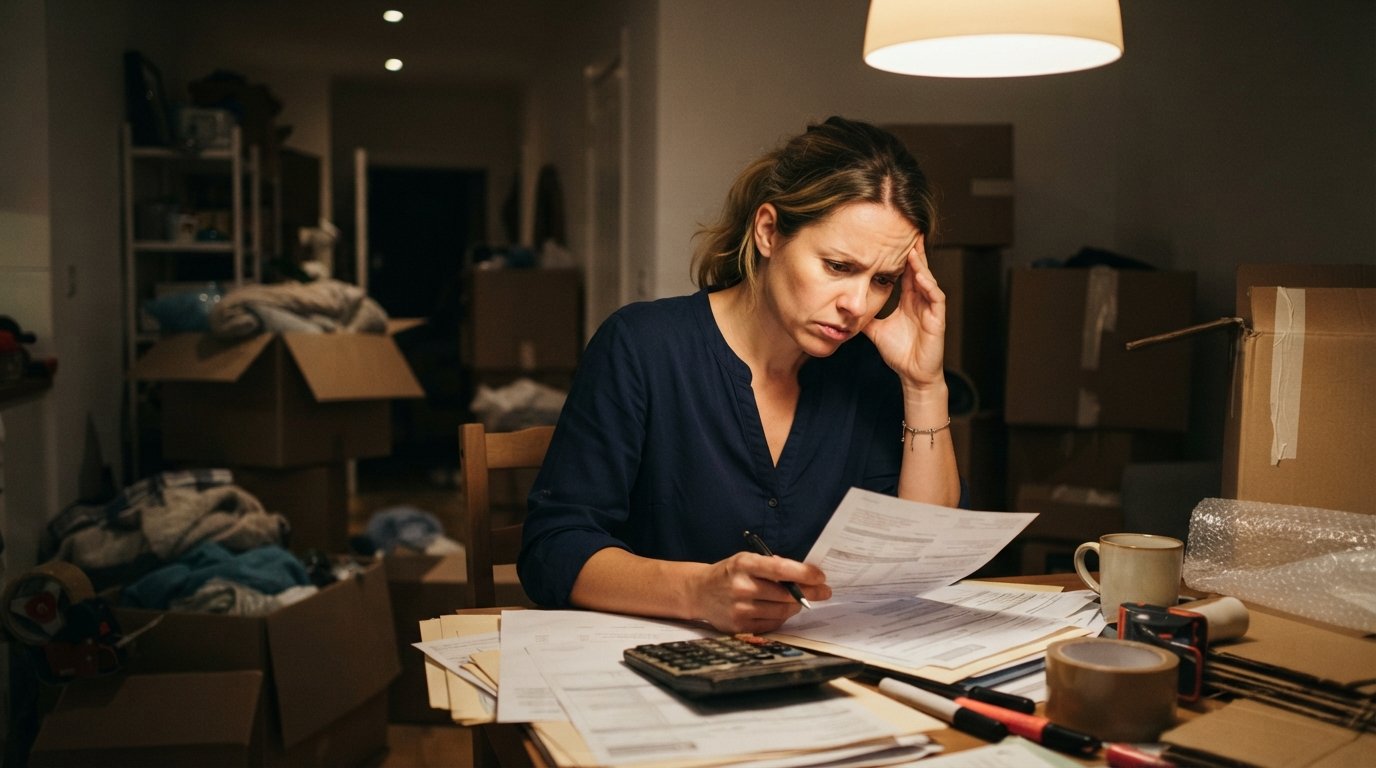
An eviction notice sets a hard deadline that rarely aligns with your savings account. You need first month's rent, a security deposit, moving truck fees, and possibly storage unit costs, all while your current income is already stretched. A personal loan can bridge that gap, but only if you borrow with precision and plan repayment before you sign anything. This guide walks through the practical steps: sizing the loan correctly, preparing documents for a fast request, and protecting your post-move budget from becoming a debt trap.
Understand the Full Cost of an Urgent Move
Before you request a single dollar, list every expense the move will trigger. Eviction-related moves carry hidden costs that a standard relocation budget misses. You are not just paying movers; you are paying to secure new housing quickly, often with less negotiating leverage than a typical renter.
Start with housing-related costs. Most landlords require first month's rent plus a security deposit equal to one month's rent. Some also charge a pet deposit, cleaning fee, or application fee per adult. If your credit is damaged from the eviction, you may face a higher deposit or a last-month-rent requirement. Add utility connection fees, since turning on electricity and water at a new address often requires deposits.
Then add the physical move. A local moving company might charge several hundred to over a thousand dollars depending on distance and volume. A rental truck costs less but requires labor and fuel. If your new lease starts after your eviction date, you need short-term storage and possibly a hotel or motel stay. These bridge costs are easy to overlook and can add hundreds of dollars.
Here is a practical checklist to total your real moving costs:
- First month's rent and security deposit at the new place
- Moving company, truck rental, or van service fees
- Storage unit for the gap between leases
- Utility deposits and connection fees
- Temporary lodging if move-out and move-in dates do not align
- Cleaning supplies and minor repairs required by your old lease
Write down a low and high estimate for each line. The high estimate becomes your borrowing target, not the low one. Underestimating is the most common mistake people make when using a personal loan for moving costs after an eviction notice. A shortfall mid-move forces you to borrow again, often at worse terms.
Decide Whether a Personal Loan Fits Your Situation
A personal loan is an unsecured installment loan, meaning you borrow a fixed sum and repay it in equal monthly payments over a set term. It can be a reasonable tool for a one-time, time-sensitive expense like an eviction move because it gives you predictable payments and a lump sum when you need it. However, it is not free money, and it is not a long-term solution for a housing crisis.
Compare it against alternatives before committing. A credit card cash advance carries high fees and immediate interest. A payday loan is far more expensive over time and can trap you in a cycle of renewals. Borrowing from friends or family avoids interest but can strain relationships. A personal loan sits in the middle: cheaper than payday products for many borrowers, but still a debt you must repay on schedule.
Ask yourself three questions before applying. First, can you afford the monthly payment after you pay the new rent? Second, is your income stable enough to cover that payment for the full loan term? Third, have you addressed the root cause of the eviction, or will the same financial pressure reappear next month? If the answer to the third question is uncertain, borrow the smallest amount possible and build a small emergency buffer into your budget.
If you are also carrying high-interest credit card balances, consider whether consolidating those debts alongside moving costs makes sense. Our guide on how to use a personal loan for debt consolidation safely explains how to avoid replacing one problem with another. For a pure moving-cost loan, keep the purpose narrow so you do not blur wants with necessities.
Borrow a Targeted Amount Without Overcommitting
The goal is to borrow exactly what the move requires, plus a small cushion, and nothing more. Overborrowing increases your monthly payment and the total interest you pay, which is dangerous when your budget is already tight from the eviction. LendersCashLoan connects borrowers with third-party lenders who may offer personal loans and installment loans, typically from $100 to $5,000, so you can request a focused amount rather than a large lump sum.
Use this simple framework to set your loan amount. Add your high estimates for rent, deposit, movers, storage, and utility deposits. Subtract any cash you already have set aside for the move. Add 10 percent as a buffer for surprises. The result is your target loan amount. If that number exceeds what you can comfortably repay over 12 to 24 months, reduce costs first: downsize the moving truck, choose a cheaper storage unit, or negotiate a later move-in date.
Payment sizing matters as much as the loan amount. A common rule is to keep total debt payments below 36 percent of your gross monthly income. After an eviction, your housing costs may already consume a large share of your paycheck. Run the numbers before you apply. If a $3,000 loan over 24 months at a typical rate produces a payment you cannot cover alongside rent and utilities, request $2,000 instead and cut the move budget accordingly.
Also check the loan term. A longer term lowers the monthly payment but increases total interest. A shorter term saves interest but raises the monthly burden. Choose the shortest term you can genuinely afford, not the longest one the lender offers. For fast, no-obligation loan options from a network of lenders, you can compare short-term loan offers through CashLoanFunded and review terms before committing.
Prepare Documents and Income Details for a Fast Request
Speed matters when an eviction deadline is looming. Lenders evaluate risk based on income stability, banking history, and identity verification, so having your documents ready shortens the process. Most online personal loan requests take under five minutes to submit, but missing information can delay a decision by days.
Gather the following before you start your application:
- Government-issued photo ID
- Proof of income, such as recent pay stubs or benefit statements
- Bank account details for verification and funding
- Social Security number for identity and credit checks
- Current contact information and address history
Income details deserve special attention. Lenders want to see that you can repay the loan, so present your most stable income sources. If you receive regular wages, include recent pay stubs. If you have gig income or self-employment, prepare bank statements showing consistent deposits. Alimony, child support, or disability payments can count if they are documented and ongoing.
Be honest about your credit situation. An eviction may have damaged your credit score, and some lenders will decline your request. That does not mean you have no options. LendersCashLoan works with a network of third-party lenders who may consider applicants with less-than-perfect credit, provided they meet income and identity requirements. Submitting one request lets you see multiple potential offers without visiting lender after lender, which saves time you do not have.
Review every offer carefully before accepting. Check the annual percentage rate, origination fees, late payment penalties, and the exact repayment schedule. A fast approval is only helpful if the terms fit your budget. If an offer looks confusing or the payment feels unmanageable, decline it and request a smaller amount or a longer term from another lender in the network.
Plan Repayment Around Your Post-Move Budget
The move itself is a one-time event, but the loan payment follows you into your new home. Before you accept funds, build a post-move monthly budget that includes rent, utilities, groceries, transportation, and the loan payment. If the total exceeds your take-home pay, adjust the loan amount or term now, not after you miss a payment.
Set up automatic payments from your checking account on a date that aligns with your payday. Late payments on a personal loan can damage your credit further and trigger fees, which is the last thing you need while rebuilding stability after an eviction. If your income arrives irregularly, choose a payment date a few days after your most reliable deposit.
Build a small buffer into your first two months after the move. Moving always costs more than expected, whether from a forgotten utility deposit or a needed furniture item. A buffer of a few hundred dollars prevents a minor surprise from turning into a missed loan payment. If you can, set aside part of the loan proceeds specifically for this purpose rather than spending the full amount on moving day.
Finally, treat the loan as a bridge, not a habit. Once you are settled, focus on rebuilding savings so the next unexpected expense does not require borrowing. Track your spending for the first 60 days in the new place, identify one or two areas to cut, and direct that money toward an emergency fund. The eviction was a financial shock, but a clear repayment plan and a lean budget can keep it from repeating.
Using a personal loan for moving costs after an eviction notice is workable when you borrow deliberately: total the real costs, borrow only what you need, prepare your documents for a fast request, and build repayment into your new budget from day one. With the right preparation, the loan becomes a practical tool for getting through a difficult transition rather than a source of new financial pressure.