
How to Use a Short Term Loan for an Urgent Home Repair
An urgent home repair needs fast funding and a clear repayment plan. Call (833)-501-3363 to explore short term loan options that fit your budget.
By Sophie Hayes
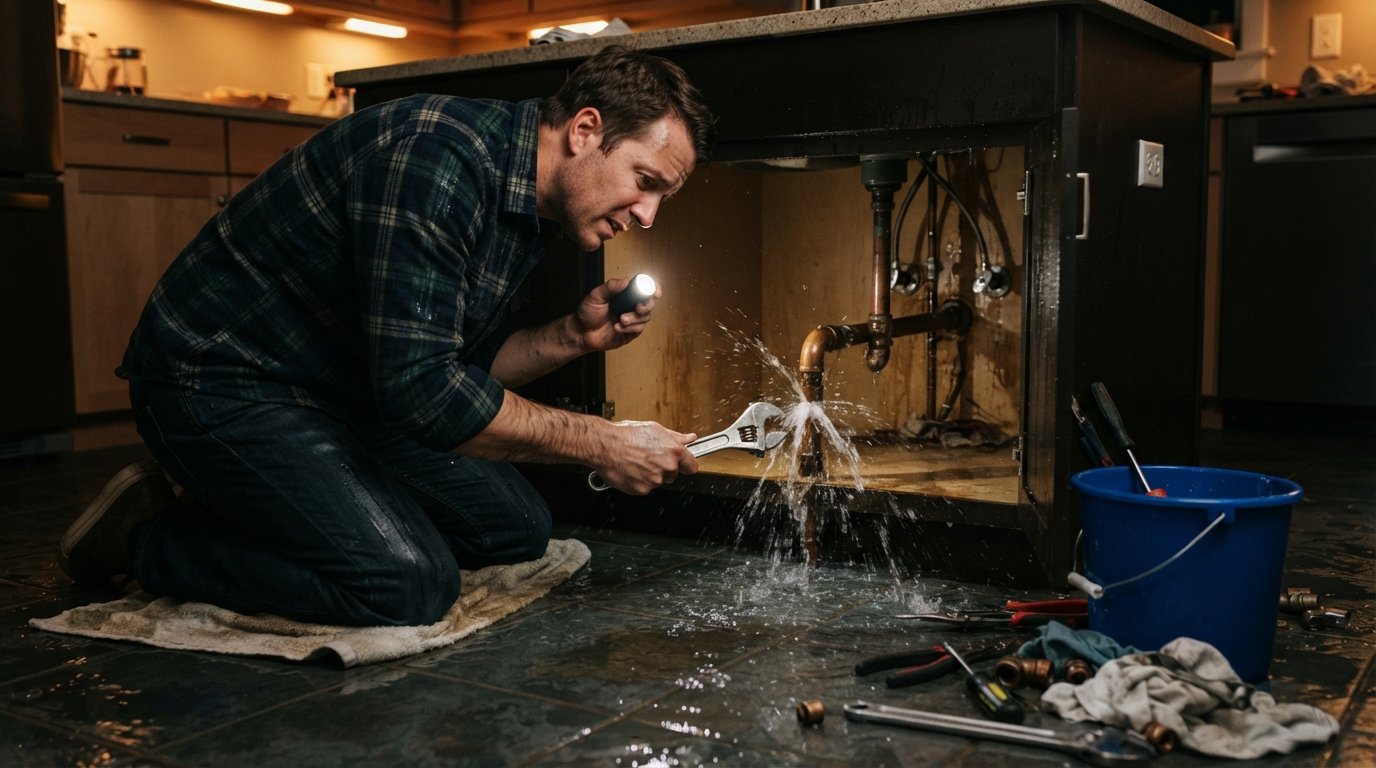
A burst pipe at 2 a.m. A furnace that dies during a cold snap. A roof leak that is spreading across the ceiling with every passing hour. Home emergencies rarely announce themselves, and they almost never arrive at a convenient time. When the repair cannot wait but your savings cannot cover it, a short term loan can bridge the gap between the problem in front of you and the next paycheck. The key is knowing how to use that money wisely so the fix does not turn into a second financial crisis.
This guide walks through the practical steps: deciding which repairs truly cannot wait, getting a solid estimate, comparing offers without damaging your credit, and building a repayment plan that keeps you in control. It also covers how a loan connection service like CashLoanFunded fits into the picture for borrowers who want fast access to multiple lending options.
Which Home Repairs Cannot Wait
Not every home problem deserves emergency funding. A cracked tile or a squeaky door can sit on the to-do list for months. A water leak under the sink, however, can rot cabinetry, warp flooring, and feed mold growth within days. The first step in using a short term loan responsibly is separating genuine emergencies from cosmetic inconveniences, because borrowing for a non-urgent repair adds interest and fees for no good reason.
Repairs that typically justify immediate action fall into a few categories. Anything involving water, heat, electricity, or structural safety tends to get more expensive the longer it sits. A small plumbing leak can turn into a flooded basement. A failed water heater leaves a household without hot water and can leak several gallons onto the floor before anyone notices. A roof puncture after a storm invites interior water damage with every rainfall.
Use this quick checklist to decide whether a repair crosses the emergency threshold:
- Water is actively leaking, pooling, or spraying anywhere in the home
- Heating or cooling has failed during extreme weather, creating a health risk
- Electrical issues pose a fire hazard, such as sparking outlets or burning smells
- Structural damage threatens the safety of the home, including sagging ceilings or cracked foundation walls
- Sewage backup or a broken toilet creates a sanitation problem, especially with children or elderly residents
If the issue matches one of these scenarios, delaying the repair usually costs more than the loan itself. A $400 plumbing fix today can prevent a $4,000 remediation project next month. That math is what makes short term borrowing reasonable for true home emergencies, provided you borrow only what the repair requires.
Get a Written Estimate Before You Borrow
One of the most common mistakes homeowners make during a crisis is borrowing a round number, like $5,000, because it feels safe. That instinct often leads to overborrowing, which means paying interest on money you never needed. Before you fill out any loan request, get at least one written estimate from a licensed contractor, and ideally two or three if time allows.
A written estimate should break down parts, labor, permits, and any contingency for hidden damage. For example, a plumber might quote $350 to replace a failed shutoff valve, but note that opening the wall could reveal additional pipe corrosion. Ask the contractor to give you a range: a likely cost and a worst-case cost. That range becomes your borrowing target.
If the repair is so urgent that you cannot wait for a full estimate (for instance, a burst pipe flooding the kitchen), ask the emergency technician for a verbal ballpark before work begins and a written invoice after. In these situations, it is still better to borrow slightly more than you think you need, because a second loan request days later is more expensive and time-consuming than one slightly larger loan. The goal is accuracy, not minimalism.
Compare Short Term Loan Offers With One Request
Once you know your target amount, the next step is finding a lender. Traditional banks often take days to approve a personal loan, which is too slow when water is dripping through the ceiling. That is where a loan connection service becomes useful. Instead of applying to five different lenders and triggering five separate credit inquiries, you submit one request and receive offers from multiple third-party lenders in the network.
LendersCashLoan operates exactly this way. It is a digital loan connection service, not a direct lender, which means it does not make credit decisions or fund loans itself. A single online request can connect you with independent lenders who may offer payday loans, personal loans, or installment loans ranging from $100 to $5,000. The process typically takes under five minutes, and the service is free to use with no obligation to accept any offer.
When comparing offers, look beyond the monthly payment. Focus on these factors:
- Annual percentage rate (APR), which shows the true cost of borrowing including fees
- Repayment term, because a longer term lowers payments but increases total interest
- Origination fees or prepayment penalties that add to the cost
- Funding speed, since some lenders can deposit funds as soon as the next business day
- Customer reviews and lender licensing in your state
For a deeper look at how these offers work, see our guide on short term lender offers for quick funding, which explains how to evaluate matching services and what to expect during the request process.
It also helps to understand which loan type fits your situation. A payday loan is typically a small, short-term advance due on your next payday, useful for a few hundred dollars. An installment loan spreads repayment over several months, which can be easier to manage for a larger repair like a $3,000 HVAC replacement. A personal loan from an online lender may offer the lowest APR if your credit qualifies. The right choice depends less on the label and more on whether the repayment schedule fits your budget.
Plan Repayment Before You Accept the Money
The repair is fixed, the water is gone, and the stress is over. Then the first payment arrives, and the budget feels tighter than expected. This is the moment where an urgent repair loan can either be a temporary bridge or the start of a debt spiral. The difference comes down to planning repayment before you accept the funds, not after.
Start by calculating your monthly surplus: income minus all essential expenses, including the new loan payment. If the payment consumes more than 10 to 15 percent of your monthly take-home pay, the loan may be too large for your current situation. In that case, consider a longer repayment term with a lower payment, or ask the contractor whether the repair can be phased so you can borrow less now and handle the rest later.
Here is a simple framework for keeping the repair from creating a second emergency:
- Set up automatic payments so you never miss a due date and trigger late fees.
- Build a small buffer into your budget for the first two months, since unexpected expenses rarely arrive alone.
- Avoid taking on additional credit until this loan is paid down, especially high-interest debt.
- If your income is irregular, choose a lender that offers flexible payment dates or biweekly options.
- Contact the lender immediately if a payment will be late, because many offer hardship options that are far cheaper than default.
It also helps to treat the loan as a one-time tool, not a habit. Short term loans are designed for urgent, temporary gaps. Using them repeatedly for routine expenses, or for repairs that insurance should cover, quickly becomes expensive. If the repair was caused by a covered event like a storm or fire, file the insurance claim first and use the loan only to cover the deductible or the gap while the claim processes.
When a Short Term Loan Makes Sense, and When It Does Not
A short term loan is a reasonable choice when three conditions are true: the repair is genuinely urgent, you have a clear repayment plan, and the total cost of borrowing is less than the damage from waiting. A $500 loan with a $75 fee to stop a leak that would otherwise cause $3,000 in mold remediation is a sound financial decision. A $5,000 loan for a cosmetic kitchen upgrade is not.
There are also alternatives worth checking before you borrow. Homeowners insurance may cover sudden damage from storms, burst pipes, or appliance failures. A home warranty plan might cover the water heater or furnace. Some contractors offer financing directly, often at promotional rates. And a small emergency fund, even $500, can handle minor repairs without any borrowing at all. The point is not to avoid short term loans entirely, but to use them as one tool among several.
For homeowners with less-than-perfect credit, the options can feel narrower, but they are not closed. Many lenders in the LendersCashLoan network work with borrowers who have bad credit, bankruptcy, or repossession history, provided they meet basic income and age requirements. The trade-off is usually a higher APR, which makes repayment planning even more important. In these cases, borrowing a smaller amount for a shorter term is often smarter than taking the largest offer available.
Final Thoughts
An urgent home repair is stressful enough without adding financial confusion to the mix. By confirming the repair is truly an emergency, getting a written estimate, comparing offers through a single request, and planning repayment before you accept funds, you can use a short term loan as a practical bridge rather than a long-term burden. The repair gets fixed, the damage stops spreading, and your budget stays intact. That is the outcome worth aiming for.