
How to Use a Small Loan to Cover a Security Deposit
A small loan can cover your security deposit and secure your new home fast. Call 8335013363 for guidance on loan options that fit your budget.
By Levi Parker
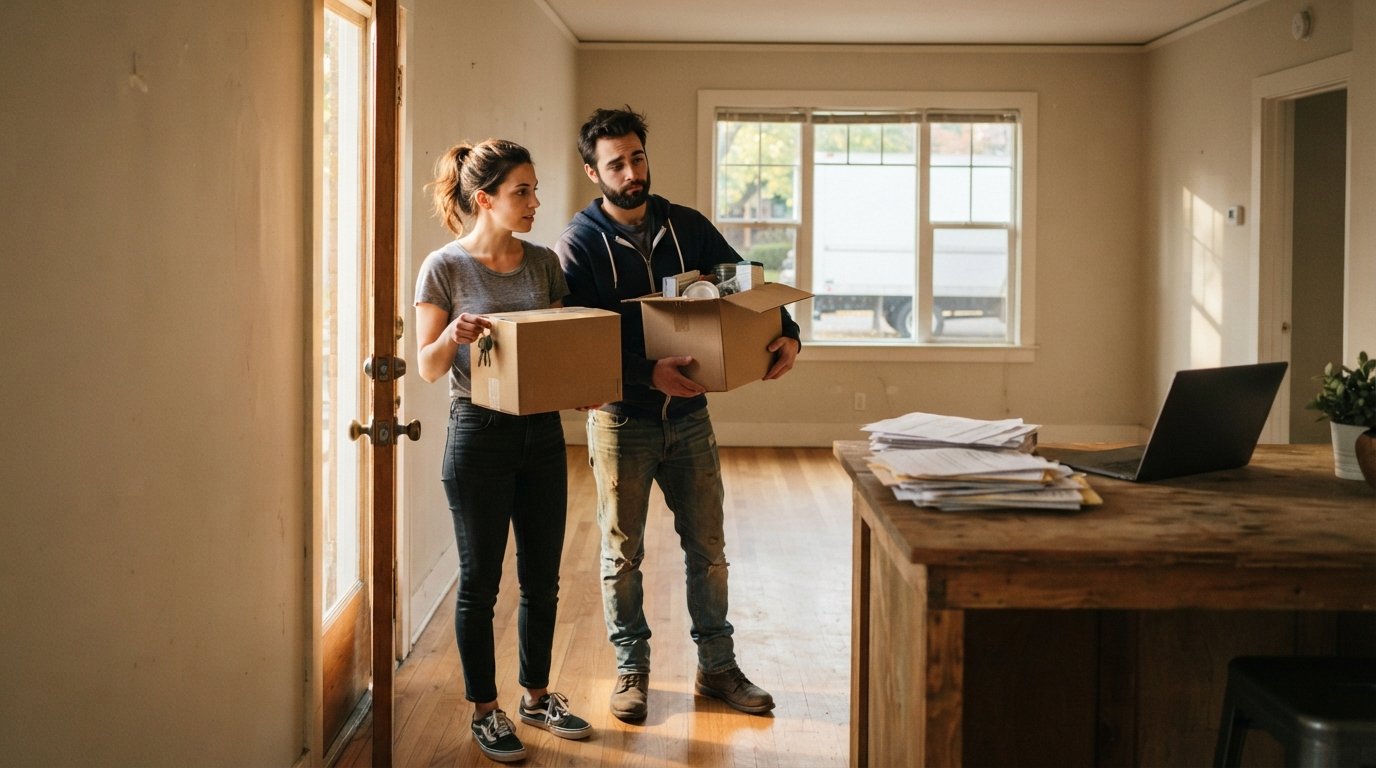
Moving into a new rental home often requires a significant upfront payment that can catch even careful savers off guard. Between first month's rent, moving truck costs, and utility setup fees, a security deposit can feel like an impossible hurdle when your bank account is already stretched thin. A small personal loan can bridge that gap, but using borrowed money for a rental deposit requires careful planning to avoid turning a short-term solution into a long-term financial burden. The key is understanding exactly when a loan makes sense, how to find the right one, and how to repay it without derailing your budget.
Why a Security Deposit Creates a Cash Flow Crisis
Landlords typically ask for one to two months' rent as a security deposit, and in competitive rental markets, that number can climb even higher. For a tenant paying $1,200 per month, a standard deposit means finding $1,200 to $2,400 in cash before the lease begins. That is on top of the first month's rent, which is due at signing, plus application fees, pet deposits, and the cost of physically moving your belongings. The total upfront burden can easily exceed $3,000 or $4,000, an amount most households cannot produce on short notice.
Traditional banks rarely help in this situation. Personal bank loans often require credit scores above 660, weeks of processing time, and extensive documentation that does not align with a fast-moving rental market. Credit cards offer speed but carry interest rates that can exceed 25 percent, making them an expensive way to cover a deposit. This is where a small loan from an alternative lending source becomes a practical option, especially for renters with less-than-perfect credit who still meet basic income requirements.
Understanding how lenders evaluate your application matters here. Factors such as income stability, debt-to-income ratio, and banking history all influence whether you qualify. If you want to understand what goes on behind the scenes, this guide on lender risk assessment explains how lenders weigh your profile before making an offer.
When Using a Small Loan for a Security Deposit Makes Sense
A loan is not automatically the right answer just because you need cash. Borrowing money to secure housing can be smart when the alternative is losing a lease, facing homelessness, or paying significantly more in temporary housing costs. The decision becomes clearer when you weigh the total cost of borrowing against the consequences of not having the deposit at all.
Consider these scenarios where a small loan is a reasonable choice:
- You have a signed job offer or steady income that will cover repayment within a few months.
- The rental market is competitive and waiting means losing the unit to another applicant.
- You have savings arriving soon, such as a tax refund, bonus, or final paycheck from a previous job.
- The cost of temporary housing (hotels, short-term rentals) exceeds the interest you would pay on a loan.
On the other hand, borrowing for a deposit is risky when your income is unstable, when you already carry high-interest debt, or when the loan payment would consume more than 10 to 15 percent of your monthly take-home pay. A security deposit is a one-time expense, but the loan payment recurs every month until the balance is cleared. If you cannot comfortably fit that payment into your budget, a different solution may be better, such as negotiating a payment plan with the landlord or finding a cosigner.
How to Apply for a Small Loan Through a Connection Service
Many borrowers assume they need to visit a bank branch or fill out applications with multiple lenders one by one. In reality, online loan connection services streamline this process by letting you submit a single request that is shared with a network of third-party lenders. LendersCashLoan operates exactly this way: it is not a direct lender and does not make credit decisions, but it connects you with lending partners who may offer short-term personal loans, payday loans, or installment loans ranging from $100 to $5,000.
The application process typically takes less than five minutes and requires basic information such as your name, address, income, and banking details. The platform uses 256-bit SSL encryption to protect your data, and there is no cost to submit a request. After you complete the form, you may receive multiple offers from different lenders, each with its own terms, rates, and repayment schedules. You then choose the offer that fits your situation best.
If you want to compare offers from multiple lending partners in one place, you can start by visiting FreeQuotes.Loans to explore available options.
Steps to Secure Funding for Your Deposit
- Gather your documents: proof of income, government-issued ID, and bank account information.
- Submit a single online request through a connection service like LendersCashLoan.
- Review the offers you receive and compare APRs, fees, and repayment terms.
- Accept the offer that best fits your budget and deposit deadline.
- Receive funds, often as soon as the next business day, and pay your landlord directly.
Comparing Loan Types for Rental Deposits
Not all small loans work the same way, and choosing the wrong type can cost you significantly more in interest and fees. The three most common options for covering a security deposit are payday loans, personal installment loans, and cash advances. Each has distinct characteristics that make it suitable for different situations.
Payday loans are short-term loans typically due on your next payday. They are fast to obtain but carry high fees that can equate to annual percentage rates above 400 percent. These work best only if you can repay the full amount within two to four weeks and have no other option. Installment loans allow you to repay over several months in fixed payments, which makes them easier to fit into a monthly budget. They usually have lower APRs than payday loans and are a better choice for larger deposits. Cash advances from credit cards or apps offer speed but often come with cash advance fees and immediate interest accrual.
When comparing offers, focus on the total cost of borrowing, not just the monthly payment. A loan with a lower monthly payment but a longer term may cost more overall. Use the APR as your primary comparison tool, and always read the lender's terms carefully before accepting an offer.
Managing Repayment Without Straining Your Budget
Once you have the funds and your deposit is paid, the real work begins: repaying the loan on time without falling behind on rent or other bills. The first step is to create a realistic repayment plan before you accept any offer. Calculate how much you can comfortably allocate toward the loan each month after covering rent, utilities, groceries, transportation, and other essentials.
If your loan has a fixed repayment schedule, set up automatic payments from your bank account to avoid missed due dates. Late payments can trigger additional fees, damage your credit score, and lead to collection activity. If you anticipate difficulty making a payment, contact your lender immediately to discuss options such as deferment or a modified payment plan. Most lenders would rather work with you than send your account to collections.
Consider ways to pay off the loan faster than the minimum schedule. Even small extra payments can reduce the total interest you pay and shorten the loan term. If you receive unexpected income, such as a tax refund or side gig payment, apply it directly to the loan balance. Once the loan is repaid, redirect that monthly payment amount into a savings account so you are better prepared for future moving costs or emergencies.
Alternatives to Consider Before Borrowing
A small loan is not the only option for covering a security deposit. Before committing to borrowed money, explore these alternatives:
- Negotiate with your landlord: Some landlords accept a reduced deposit or allow you to pay it in installments over the first few months.
- Ask about deposit insurance: Certain companies offer deposit insurance or surety bonds that replace the upfront cash requirement for a small monthly fee.
- Use a cosigner: A cosigner with good credit may help you qualify for a lower-rate loan or reduce the deposit requirement.
- Look for move-in specials: Some rental properties waive or reduce deposits during slow leasing seasons.
- Tap into community resources: Local housing authorities and nonprofits sometimes offer emergency rental assistance.
Each of these options has trade-offs. Negotiating with a landlord works best in soft rental markets where vacancies are high. Deposit insurance can save you cash upfront but adds a recurring fee. A cosigner helps you qualify but puts someone else's credit at risk if you default. Weigh these factors carefully before deciding whether a loan is truly your best path.
Protecting Your Credit and Financial Health
Taking out a small loan affects your credit profile in several ways. When you apply, the lender performs a credit check, which may result in a hard inquiry that temporarily lowers your score by a few points. Once the loan is active, making on-time payments can actually improve your credit score over time by demonstrating responsible borrowing behavior. Missing payments, however, can cause significant damage that takes years to repair.
Keep your total debt load manageable. Financial experts generally recommend that your debt-to-income ratio stay below 36 percent, meaning your total monthly debt payments should not exceed 36 percent of your gross monthly income. If adding a loan payment pushes you above that threshold, you may be overextending yourself. In that case, consider a smaller loan amount or explore alternatives to borrowing.
Finally, remember that short-term loans are not a long-term financial solution. They are designed to address immediate, temporary cash shortfalls. If you find yourself repeatedly relying on loans to cover recurring expenses, it may be time to review your overall budget and seek guidance from a financial counselor.
Using a small loan to cover a security deposit can be a practical solution when you approach it strategically. Choose the right loan type, borrow only what you need, and commit to a repayment plan you can sustain. With careful planning, you can secure your new home without compromising your financial stability.