
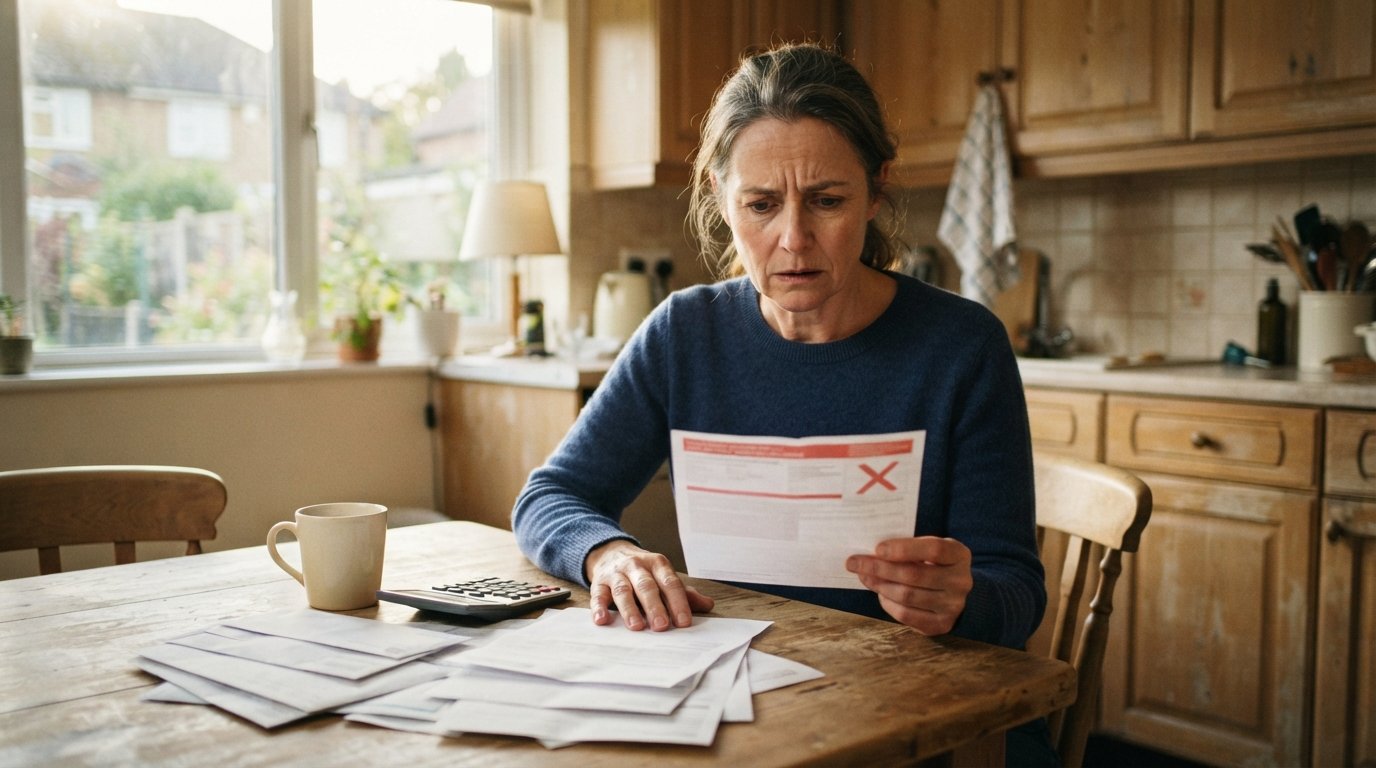
Installment Loan for a Utility Shutoff Notice: Smart Move?
Using an installment loan to pay a large utility shutoff notice can restore service fast, but compare terms and explore assistance first to avoid costly debt.
By Isaac Ellis
A utility shutoff notice is one of the most stressful pieces of mail a household can receive. The threat of losing power, water, or heat within days forces quick decisions, often under financial pressure. When the past-due balance is large, many people wonder whether using an installment loan to pay a large utility shutoff notice is a practical solution or a dangerous trap. The answer depends on the numbers, the terms, and a clear-eyed look at your budget. This guide walks through how to read the notice, compare loan costs to utility payment plans, adjust your budget to avoid future arrears, and recognize when assistance programs should come before borrowing.
Read the Shutoff Notice Carefully Before You Borrow
Utility shutoff notices are not all the same. The exact amount required to stop disconnection is often different from the total past-due balance. Many utilities require the full arrears plus a reconnection fee and sometimes a new deposit before service is restored. Before you consider any financing, locate the reinstatement amount, the shutoff date, and the deadline to act. Call the utility and ask for a breakdown: past-due charges, late fees, reconnection fees, and any deposit required. Write down the total. This figure, not the amount on the envelope, is what you need to cover.
Some notices include an option to enter a payment arrangement. If the utility offers a plan that spreads the balance over several months without interest, that is often cheaper than borrowing. However, if the utility demands a lump sum before the shutoff date, an installment loan may be the only way to keep service on. Understanding the difference between the total balance and the reinstatement amount prevents you from borrowing more than necessary. It also helps you avoid a situation where you pay the loan but still face a reconnection fee you did not budget for.
Timing matters. Most utilities issue shutoff notices with a window of 10 to 30 days before disconnection. If you have time, explore assistance programs first. If the shutoff is imminent, you may need to act faster. In either case, do not ignore the notice. Ignoring it does not make the balance disappear, and reconnection fees and deposits can make the total much higher after service is cut.
How Installment Loans Compare to Utility Payment Arrangements
An installment loan is a lump sum you borrow and repay in fixed monthly payments over a set term, often 3 to 24 months. The interest rate and fees vary widely based on your credit and the lender. A utility payment arrangement, by contrast, is an agreement with the utility to pay off the past-due balance in installments, usually without interest, while you keep current on new bills. The table below summarizes the key differences.
- Cost: Utility arrangements typically carry no interest or fees; installment loans charge interest and possibly origination fees.
- Impact on credit: Utility arrangements usually do not affect credit unless you default; installment loans may help or hurt depending on payment history.
- Speed: Installment loans can fund in one business day; utility arrangements may take a phone call and a signed agreement.
- Risk: Missing loan payments can damage credit and lead to collection; missing arrangement payments can lead to shutoff.
If the utility offers a no-interest arrangement, it is almost always the better financial choice. But not all utilities offer them, and some require a large down payment. If you have already been denied an arrangement or the utility demands a lump sum, an installment loan may be the next best option. Before you sign, compare the total cost of the loan (principal plus interest and fees) to the reinstatement amount. If the loan costs significantly more than the utility balance, consider whether a smaller loan or a different solution could work.
Flexibility in repayment matters. Some installment loans allow early payoff without penalty, while others do not. If you expect a tax refund or bonus in a few months, a loan with no prepayment penalty could save you money. For a deeper look at how repayment plans work, see our guide on how flexible installment loan repayment plans can be. Understanding the terms helps you avoid surprises and choose a loan that fits your cash flow.
Budget Changes to Avoid Future Arrears
Borrowing to pay a shutoff notice solves the immediate crisis, but it does not fix the underlying budget gap. If the same shortfall occurs next month, you may face another notice and another loan. Before you take on debt, review your monthly income and expenses to find areas to cut or adjust. A practical approach is to list all fixed expenses (rent, mortgage, insurance, loan payments) and variable expenses (food, transportation, utilities). Then identify at least three categories where you can reduce spending for the next six months.
Consider a realistic budget framework. Start with your net income, subtract fixed necessities, and allocate a portion to debt repayment. If the installment loan payment pushes your budget into deficit, the loan is not affordable. A common guideline is to keep total debt payments below 36 percent of gross income, though this varies by situation. You may need to temporarily cut discretionary spending, negotiate lower rates on other bills, or increase income through overtime or a side gig. The goal is to build a small buffer so that a future utility bill does not become a crisis.
Energy efficiency also plays a role. Small changes like adjusting the thermostat, sealing drafts, and using LED bulbs can lower monthly bills. Some utilities offer free energy audits or efficiency kits. These steps reduce the size of future bills, making it easier to stay current. If your budget is tight, ask the utility about level billing or budget billing, which averages payments across the year to avoid seasonal spikes.
Reconnection Fees and Deposit Rules
If service has already been disconnected, the cost to restore it is higher than the past-due balance. Most utilities charge a reconnection fee during business hours and a higher fee after hours or on weekends. They may also require a security deposit, especially if you are a new customer or have a history of late payments. The deposit is often equal to one or two months of average usage and may be refundable after a year of on-time payments. Before you borrow, call the utility and ask for the total reinstatement cost, including all fees and deposits. This prevents you from borrowing too little and facing another shutoff.
Some utilities allow you to pay the reconnection fee and deposit in installments, but many require payment in full before service is restored. If you use an installment loan to cover these costs, make sure the loan amount includes the full reinstatement total plus any buffer for the first new bill. Otherwise, you may restore service only to face another notice quickly. Keep receipts and confirmation numbers for all payments. If there is a dispute, documentation helps.
When Assistance Programs Should Come Before Borrowing
Before you take on debt, explore assistance programs. Many states and local agencies offer Low Income Home Energy Assistance Program (LIHEAP) funds, charitable grants, and payment plans for households facing shutoff. These programs can provide grants that do not need to be repaid, which is always better than a loan. Eligibility is usually based on income, household size, and crisis status. Applying takes time, so start as soon as you receive the notice. If the shutoff date is close, ask the utility for a extension while your application is processed.
Community action agencies, churches, and nonprofit organizations may also offer emergency utility assistance. Some utilities have hardship funds for customers in temporary crisis. Dialing 211 can connect you to local resources. If you qualify for assistance, use it first. An installment loan should be a last resort when no grant or arrangement is available and the shutoff is imminent. Even then, borrow only what you need and have a plan to repay.
When you do need to find a loan, consider using a connection service to compare offers from multiple lenders. StartPaydayLoan is a free online service that helps U.S. consumers find short-term and payday loan options by submitting one request form. It is not a lender and does not make credit decisions; any terms come directly from the lender. Using a service like this can save time and help you see a range of options, but always review the loan agreement carefully before signing.
Steps to Take If You Choose an Installment Loan
If you decide that using an installment loan to pay a large utility shutoff notice is the right move, follow a structured process to avoid mistakes. First, confirm the exact reinstatement amount with the utility. Second, check your credit and gather income documentation. Third, request offers from multiple lenders or a connection service. Fourth, compare the APR, fees, term, and monthly payment. Fifth, read the loan agreement and understand the consequences of late payments. Sixth, set up automatic payments if possible to avoid missing a due date. Finally, keep the utility confirmation and loan documents in one place.
Borrow only the amount needed to cover the reinstatement total plus a small buffer for the next bill. Avoid borrowing extra for discretionary spending, as that increases the cost of the loan. If you have bad credit, you may still qualify for an installment loan, but the interest rate may be higher. In that case, consider a shorter term to reduce total interest, but ensure the monthly payment is affordable. A longer term lowers the monthly payment but increases total interest; choose the shortest term you can comfortably afford.
Remember that an installment loan is not a long-term solution to financial problems. It is a tool to bridge a temporary gap. If you find yourself relying on loans to pay utilities month after month, seek budgeting help or credit counseling. Nonprofit credit counselors can help you create a debt management plan and negotiate with creditors. Addressing the root cause is the only way to break the cycle.
Risks and Alternatives to Consider
Installment loans carry risks. Late payments can lead to fees, higher interest rates, and negative credit reporting. If you default, the lender may send the debt to collections or sue. Some lenders require post-dated checks or electronic access to your bank account, which can lead to overdrafts if funds are not available. Before you sign, understand the lender's policies on late payments and collections. If the loan has a prepayment penalty, you may pay more if you pay it off early. Read the fine print.
Alternatives include utility payment plans, assistance programs, borrowing from family or friends, selling unused items, or taking on a temporary side job. Each has trade-offs. Borrowing from family can strain relationships; selling items takes time. But these options may be cheaper than a high-interest loan. If you have a credit card with available credit, compare the interest rate to the installment loan. Credit card rates are often lower, but carrying a balance can lead to long-term debt. A balance transfer to a 0 percent APR card could be an option if you can pay it off before the promotional period ends.
Finally, communicate with your utility. Many utilities are willing to work with customers who call before the shutoff date. Ask for a supervisor if the first representative is not helpful. Explain your situation and propose a payment plan you can afford. Some utilities offer budget billing or due date extensions. These options are often cheaper than borrowing and can provide immediate relief.
Facing a utility shutoff notice is stressful, but you have options. Start by reading the notice carefully and calling the utility for the exact reinstatement amount. Explore assistance programs and payment arrangements before borrowing. If you do use an installment loan, borrow only what you need, compare offers, and have a plan to repay. And take steps to adjust your budget so that the next utility bill does not become another crisis. With careful planning, you can keep the lights on and stay on solid financial ground.