
Loan Options for Unexpected Car Engine Repair
Compare loan options for unexpected car engine repair and get funded fast, even with bad credit, so you can avoid surprise repair bills.
By Henry Sullivan
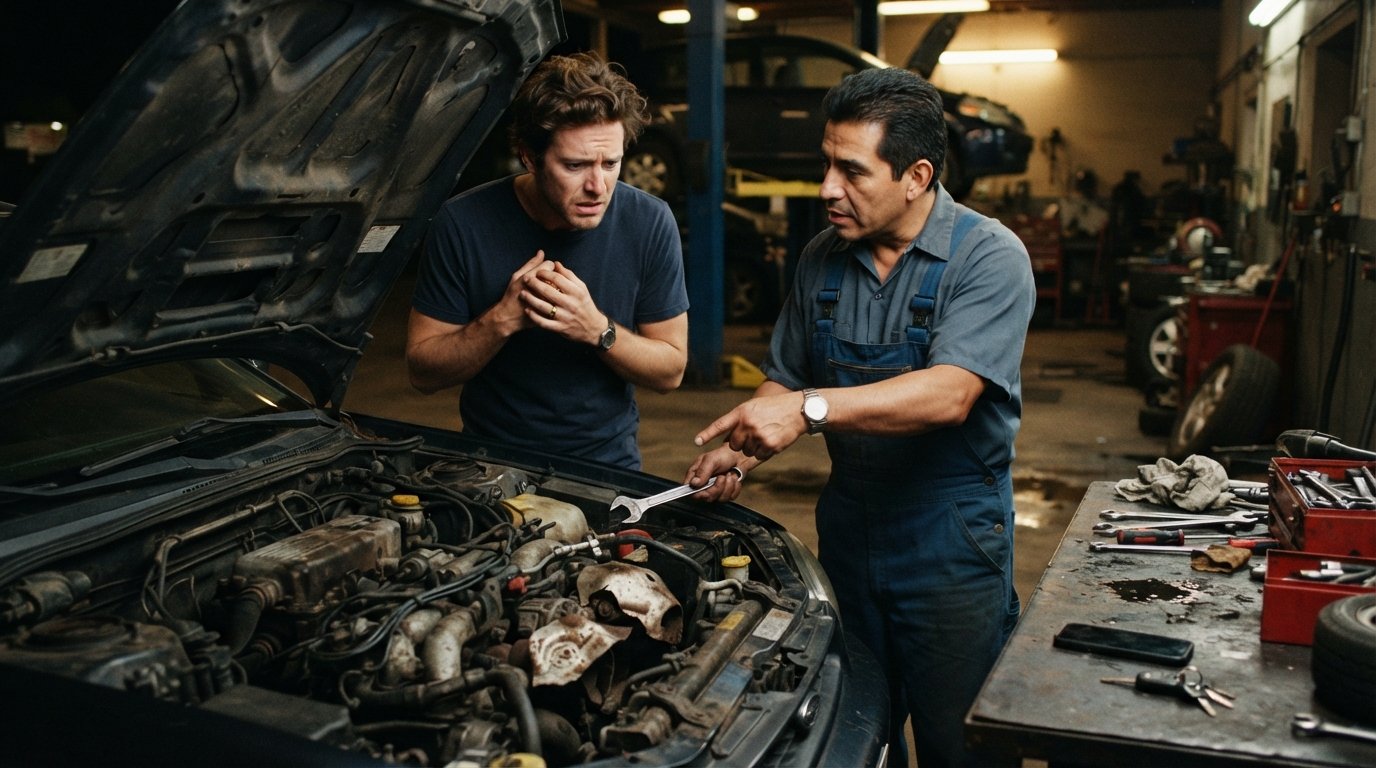
A grinding noise, a sudden cloud of smoke, or a dashboard warning light that will not turn off: an engine failure rarely announces itself at a convenient time. Within minutes, you may be facing a repair estimate in the thousands of dollars, a car that will not start, and a work commute that depends entirely on getting the vehicle back on the road. The pressure is real, and it usually arrives without warning. Fortunately, you have more choices than a single trip to the mechanic might suggest.
This guide walks through practical loan options for unexpected car engine repair, explains how each one works, and shows you how to compare offers without adding unnecessary stress. Whether your credit history is spotless or less than perfect, there is a path forward. The key is understanding what lenders look for, what the money actually costs, and how to move quickly without making a decision you will regret later.
Why an Engine Repair Bill Feels So Overwhelming
Engine repairs sit in a category of their own when it comes to financial shock. A minor fix like a water pump or timing belt can run several hundred dollars, while a full engine replacement or rebuild often climbs past $3,000 to $6,000 depending on the make, model, and labor rates in your area. That range is wide, but the common thread is that most households do not keep that kind of cash sitting idle in a checking account.
At the same time, a non-working car creates a cascade of secondary costs. You may need rideshare trips, a rental car, or time off work. Every day without transportation adds to the total financial hit. That is why waiting and saving for a few months is rarely realistic when the engine is the problem. You need a solution that matches the urgency of the situation.
Before you apply anywhere, it helps to gather a few facts. Knowing these details puts you in a stronger position to compare offers:
- The exact repair estimate, in writing, from a licensed mechanic
- Whether the shop offers a payment plan or accepts a third-party financing partner
- How much you can realistically put toward the bill yourself
- Your current credit score range and monthly income
- How soon you need the car back on the road
With those numbers in hand, you can evaluate loan products with a clear target instead of guessing. A written estimate also protects you from surprise add-ons and gives lenders a specific figure to work with.
The Main Loan Options for Unexpected Car Engine Repair
There is no single best loan for every driver. The right choice depends on your credit profile, how fast you need funds, and how much you can repay each month. The options below cover the most common routes people take when an engine fails.
Personal Installment Loans
An installment loan gives you a lump sum that you repay in fixed monthly payments over a set term, often ranging from a few months to several years. Because the payments are predictable, this option works well when you want to spread the cost of a major repair across a longer period. Interest rates vary widely based on credit history, income, and the lender. Borrowers with strong credit may see single-digit or low double-digit annual percentage rates, while those with damaged credit should expect higher rates.
One advantage of installment loans is that the money is not tied to the vehicle itself. You can use it for the repair, for a rental car during the downtime, or for related expenses. That flexibility matters when an engine failure disrupts your entire routine, not just your bank account.
Payday and Short-Term Loans
Payday loans and similar short-term products are designed for small, urgent expenses and are typically repaid on your next payday or over a few weeks. They are fast and often accessible to people with bad credit, but they come with very high fees and APRs. If you go this route, borrow only what you can repay on time and have a clear plan for doing so.
Short-term loans can bridge a gap when the repair is modest and your next paycheck is close. They are a poor fit for a $5,000 engine replacement, because rolling a large balance into repeated renewals quickly becomes unaffordable. Treat them as a narrow tool, not a long-term solution.
Auto Repair Financing Through the Shop
Many repair chains and independent shops partner with financing companies to offer point-of-sale loans. You apply at the counter or online, and if approved, the shop gets paid directly. These programs often advertise promotional periods with no interest if you pay the balance in full within a set window, such as six or twelve months.
The catch is that if you miss the deadline, deferred interest can retroactively apply to the entire original balance. Read the terms carefully. If you are confident you can clear the balance within the promotional window, this can be an efficient option. If not, a standard installment loan with a fixed rate may cost less overall.
Credit Cards and Lines of Credit
If you have an existing credit card with available credit, using it for the repair is one of the fastest options available. You avoid a new application and can pay over time, though standard card APRs are often high. A personal line of credit from a bank or credit union may offer a lower rate than a card, but approval can take longer and usually depends on solid credit.
Balance transfer cards with introductory zero percent APR offers can be useful if you can repay the balance before the promotional period ends. Otherwise, the regular rate applies, and the math may not work in your favor.
Borrowing From Family or Friends
A loan from a trusted family member or friend can be the cheapest option on paper, but it carries relational risk. If you choose this route, put the agreement in writing: the amount, the repayment schedule, and what happens if you fall behind. A clear document protects the relationship as much as it protects the money.
How to Compare Offers Without Getting Overwhelmed
Once you have a few options in front of you, comparison becomes a numbers game. The goal is to find the lowest total cost that you can comfortably repay. Do not focus only on the monthly payment, because a long term with a small payment can cost far more in interest than a shorter term with a higher payment.
Here is a simple framework for evaluating each offer:
- Calculate the total repayment amount, not just the monthly figure.
- Compare the APR across all offers, since it captures both interest and fees.
- Check for prepayment penalties that would punish you for paying early.
- Confirm the repayment schedule fits your income cycle.
- Read the fine print on late fees and renewal terms.
If you are working with damaged credit, you may want to review strategies for bad credit loan options for fast funding before you submit applications, since some lenders specialize in these profiles and can offer better terms than a generic bank product. Applying to several lenders at once can also help you avoid multiple hard credit pulls, which can temporarily lower your score.
Speed matters, but so does accuracy. A rushed application with incorrect income figures can lead to a denial or a worse offer. Take ten extra minutes to verify your information before you hit submit.
Where a Loan Connection Service Fits In
If you would rather not call lender after lender while your car sits in the shop, a loan connection service can streamline the process. Instead of filling out multiple applications, you submit one request and receive offers from a network of third-party lenders. This approach saves time and lets you compare terms side by side.
Services like FreeQuotes.Loans connect borrowers with lenders who handle payday loans, personal loans, and installment loans, including for urgent needs like car repairs and for applicants with less-than-perfect credit. The platform itself is not a direct lender, so it does not make credit decisions or fund loans. It simply matches your request with lending partners who may be able to help. That distinction matters, because it means your approval and terms come from the lender, not the connection service.
Using a connection service is especially useful when you are short on time and unsure which lenders will work with your credit profile. You get a wider view of the market without the legwork of researching each lender individually.
Qualifying With Bad Credit: What Lenders Actually Look At
A low credit score does not automatically close the door. Many lenders in the short-term and installment space focus on income and stability as much as credit history. If you can show regular income and a bank account in good standing, you may still receive offers, though the rates will likely be higher than what a prime borrower would see.
Common requirements across most short-term lenders include:
- U.S. citizenship or legal residency
- Minimum age of 18
- Regular income, whether from employment, benefits, or self-employment
- An active checking account for deposits and repayments
- Valid contact information and identification
Some lenders also consider factors like how long you have held your job or lived at your address. If your credit is damaged, be prepared to explain any recent issues and show that your income is stable. A short, honest explanation can go a long way.
It also helps to know your credit score before you apply. You can get a free report from major bureaus and check for errors that might be dragging your score down. Fixing a reporting mistake can sometimes improve your standing faster than you expect.
How to Speed Up Approval and Funding
When your car is undrivable, every hour counts. A few practical steps can shorten the timeline from application to funded repair.
- Gather your documents in advance: ID, proof of income, and bank details.
- Apply during business hours when lenders can verify information quickly.
- Choose electronic deposit rather than a paper check.
- Respond promptly to any lender follow-up requests.
Many short-term lenders can deposit funds as soon as the next business day, and some connection services report even faster turnaround for qualified applicants. The single biggest delay is usually incomplete information, so double-check everything before submitting.
If the repair shop offers financing, ask whether you can be approved on the spot. Combining a small shop financing plan with a modest personal loan can sometimes cover the full bill without overextending on any single product.
Repaying the Loan Without Derailing Your Budget
Taking on debt to fix a car is a short-term necessity, not a long-term strategy. Once the repair is done, your focus should shift to repayment. Build the loan payment into your monthly budget before you spend on anything else, and consider paying extra when you can to reduce interest.
If you took a short-term loan, avoid renewing it. Renewal fees add up quickly and can trap you in a cycle that costs more than the original repair. If you cannot repay on time, contact the lender before the due date to discuss options. Many lenders prefer to work out a modified schedule rather than send an account to collections.
Finally, start a small emergency fund for the next surprise. Even $500 set aside can cover a minor repair and reduce the odds that you need to borrow again. Financial resilience is built one small cushion at a time.
An unexpected engine repair is stressful, but it does not have to become a financial crisis. By understanding your loan options, comparing offers carefully, and borrowing only what you can repay, you can get your car back on the road and keep your budget intact.