
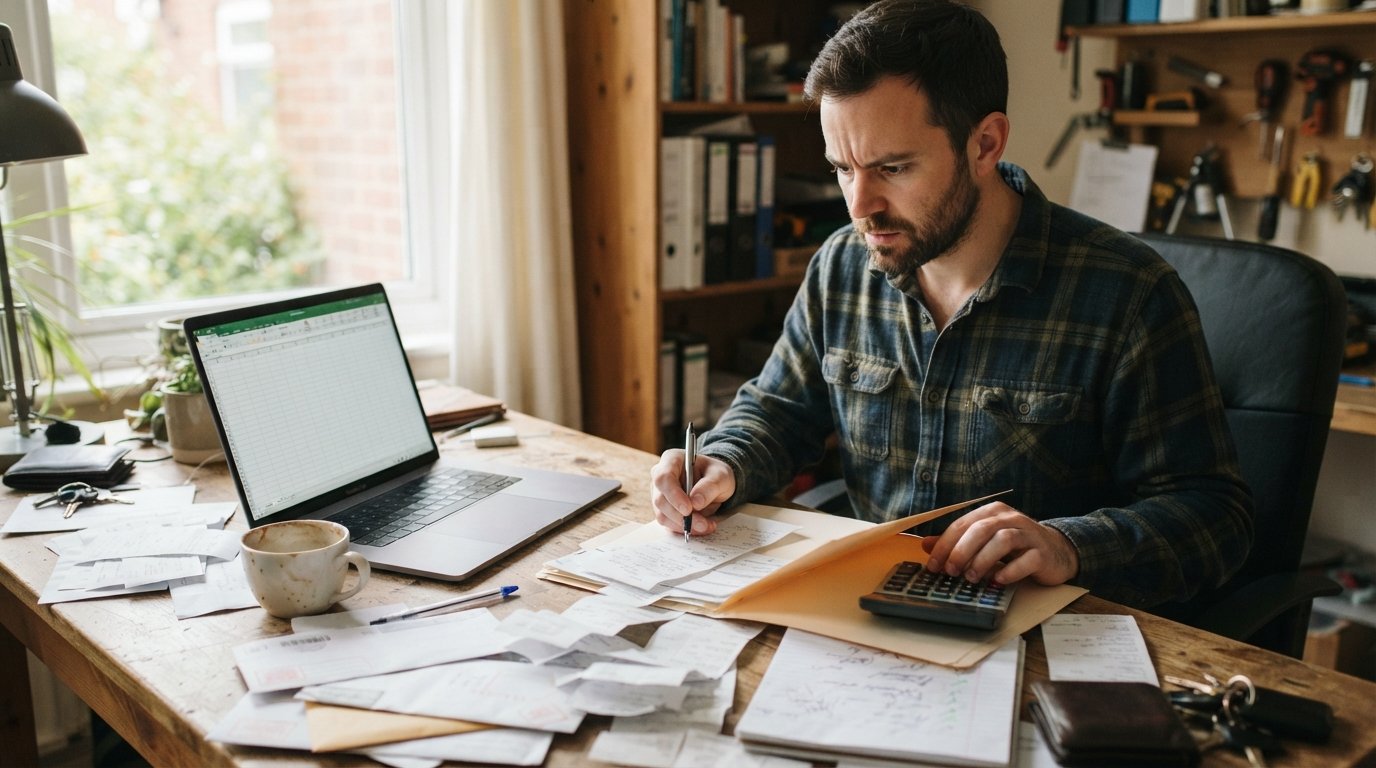
Loan Request When Paid Under the Table: What to Know
Learn how to make a loan request when paid under the table. Discover income verification alternatives and avoid claim mistakes to boost approval odds.
By Yara Griffin
Getting paid in cash under the table can feel like a financial advantage until you need to prove your income for a loan. Whether you are a server, a contractor, a gig worker, or a small business owner who receives cash payments, you may face a frustrating roadblock when applying for a personal loan. Traditional lenders often require pay stubs and W-2 forms, documents that do not exist in your situation. But that does not mean you are out of options. Understanding how lenders verify income and what alternatives exist can help you navigate a loan request when paid under the table without unnecessary stress or rejection.
The reality is that millions of workers earn income outside the formal payroll system. While this can complicate a loan application, many lenders have adapted their verification processes to accommodate non-traditional earners. The key is to approach the process with honesty and preparation. This guide will walk you through how lenders assess income, what documentation you can use as proof, and how to avoid common mistakes that could derail your application. By the end, you will have a clear roadmap for making a successful loan request even when your income is not reported on a standard tax form.
How Lenders Verify Income Without Pay Stubs
When you apply for a loan, lenders want to confirm that you have the ability to repay. For traditional employees, pay stubs and W-2s provide a straightforward snapshot of income. But for those paid under the table, lenders must rely on other signals. Many lenders, especially those offering online personal loans and short-term loans, have developed alternative verification methods. They may look at bank statements, deposit histories, or even conduct manual reviews of your financial situation.
One common approach is to request bank statements from the last few months. Lenders analyze these statements to see regular deposits that correspond to your income. Even if the deposits are cash, consistent patterns can demonstrate that you have a steady flow of funds. Some lenders may also accept letters from employers, clients, or customers confirming your income, especially if you are a freelancer or independent contractor. Additionally, lenders might use third-party verification services that analyze your bank account data to estimate your income based on deposit activity.
It is important to note that not all lenders are equally flexible. Banks and credit unions often adhere to strict documentation requirements, while online lenders and loan connection services may be more accommodating. If you are self-employed, you might find our guide on how to handle a loan request when self-employed particularly useful, as it covers similar challenges with income verification. The key is to communicate openly with the lender about your situation and ask what alternatives they accept.
Bank Statements and Deposit History as Income Proof
Bank statements are often the most accessible form of income verification for under-the-table earners. Lenders typically ask for two to three months of statements to establish a pattern. When reviewing your statements, they look for recurring deposits that align with your stated income. If you deposit cash regularly, those deposits can serve as evidence, especially if they are consistent in amount and timing.
To strengthen your case, consider maintaining a separate bank account for your income and expenses. This makes it easier for lenders to see your cash flow. You should also avoid mixing personal and business funds, as this can muddy the waters. If you receive payments through apps like Venmo or PayPal, those transaction histories can also be used as proof, so keep detailed records. Some lenders may accept screenshots or statements from these platforms.
Here are a few tips to make your bank statements work in your favor:
- Deposit your cash earnings regularly into the same account to create a clear paper trail.
- Avoid large, irregular deposits that might look suspicious or inconsistent.
- Keep a simple ledger or spreadsheet of your income and expenses to supplement your statements.
- Request statements from the last three months to show a stable pattern.
Remember that lenders are not just looking at the total amount; they want to see that your income is reliable. If you have seasonal fluctuations, explain them in a cover letter or during the application process. Transparency builds trust and can improve your chances of approval.
Why Some Independent Lenders Accept Alternative Verification
Independent lenders, including many online lenders and loan connection services, often cater to borrowers with non-traditional income. These lenders recognize that a lack of pay stubs does not necessarily mean a lack of ability to repay. They may use proprietary algorithms or manual underwriting to assess risk based on alternative data, such as bank statements, utility payments, and even rental history. This flexibility is a significant advantage for under-the-table earners.
Loan connection services like FundingCashLoans work with a network of third-party lenders who may offer various loan products, including short-term loans and installment loans. These lenders often have more lenient documentation requirements and may accept bank statements or other alternative proof of income. Because FundingCashLoans is not a lender itself, it does not make credit decisions, but it can connect you with lenders who are more likely to work with your situation. This can be a valuable resource when you are struggling to find a traditional lender.
It is also worth noting that some lenders specialize in serving gig workers, freelancers, and cash-based businesses. These lenders understand the unique challenges of informal income and have tailored their verification processes accordingly. When you submit a loan request, be upfront about your income source. Hiding it or misrepresenting it can lead to denial or even accusations of fraud. Instead, focus on presenting your financial picture as clearly as possible.
What to Avoid Claiming on a Request Form
When filling out a loan request form, honesty is paramount. Some applicants are tempted to inflate their income or claim a traditional job to appear more creditworthy. This is a dangerous strategy. Lenders have ways of verifying information, and discrepancies can result in immediate rejection or legal consequences. For example, if you claim a salary but cannot provide pay stubs, your application will likely be flagged. Similarly, overstating your income on the form, even if you can back it up with bank statements, can be seen as misrepresentation.
You should also avoid leaving out important information, such as existing debts or other financial obligations. Lenders consider your debt-to-income ratio when making decisions, and omitting debts can be considered fraudulent. Instead, be transparent about your entire financial situation. If you have irregular income, explain it. If you have bad credit, acknowledge it. Many lenders are willing to work with borrowers who have less-than-perfect credit, especially if they can demonstrate a stable income through alternative means.
Another common mistake is using a friend's or relative's address or bank account to appear more stable. This is not only unethical but can also be illegal. Lenders cross-reference information, and inconsistencies can raise red flags. Always use your own information and documents. If you need help understanding what lenders look for, consider consulting a financial advisor or using resources like those offered by LendersCashLoan, which provides educational guides on borrowing and budgeting.
Alternatives If No Documentation Exists
If you have no documentation at all, you may still have options, though they may come with higher costs or different terms. Here are some alternatives to consider:
- Secured Loans: If you have collateral, such as a car or savings account, you may be able to get a secured loan. These loans are backed by the asset, so lenders are more willing to overlook documentation gaps.
- Co-Signer or Guarantor: Having someone with good credit and verifiable income co-sign your loan can significantly improve your chances. The co-signer takes on responsibility if you default, so this should be discussed carefully.
- Payday and Title Loans: These short-term loans often require less documentation, but they come with high fees and interest rates. They should be used with caution and only as a last resort.
- Borrow from Friends or Family: While not a formal loan, this can be a quick way to get funds. However, it is important to put the agreement in writing to avoid misunderstandings.
- Credit Union or Community Bank: Some smaller financial institutions may be more flexible with documentation if you have an established relationship with them. It is worth asking.
Each of these options has trade-offs. Secured loans require collateral, co-signers put someone else at risk, and payday loans can trap you in a cycle of debt. Before choosing any alternative, carefully review the terms and consider whether you can realistically repay the loan. Remember that short-term loans are not a long-term financial solution and should be used responsibly.
Additionally, building a formal financial record can help you in the future. Consider opening a dedicated bank account for your income, paying taxes on your earnings, and keeping detailed records. This may increase your taxable income, but it also creates a verifiable financial history that lenders can use. Over time, you can transition to a position where you have the documentation needed for traditional loans.
In conclusion, a loan request when paid under the table is challenging but not impossible. By understanding how lenders verify income and using alternative documentation, you can improve your chances of approval. Always be honest and transparent, and explore all your options before committing to a loan. With the right approach, you can access the funds you need without compromising your financial integrity.