
Online Loan Request vs Traditional Bank Loan Speed Comparison
Compare online loan request vs traditional bank loan speed comparison: see typical timelines, funding speeds, and when each option fits your urgency.
By Isaac Ellis
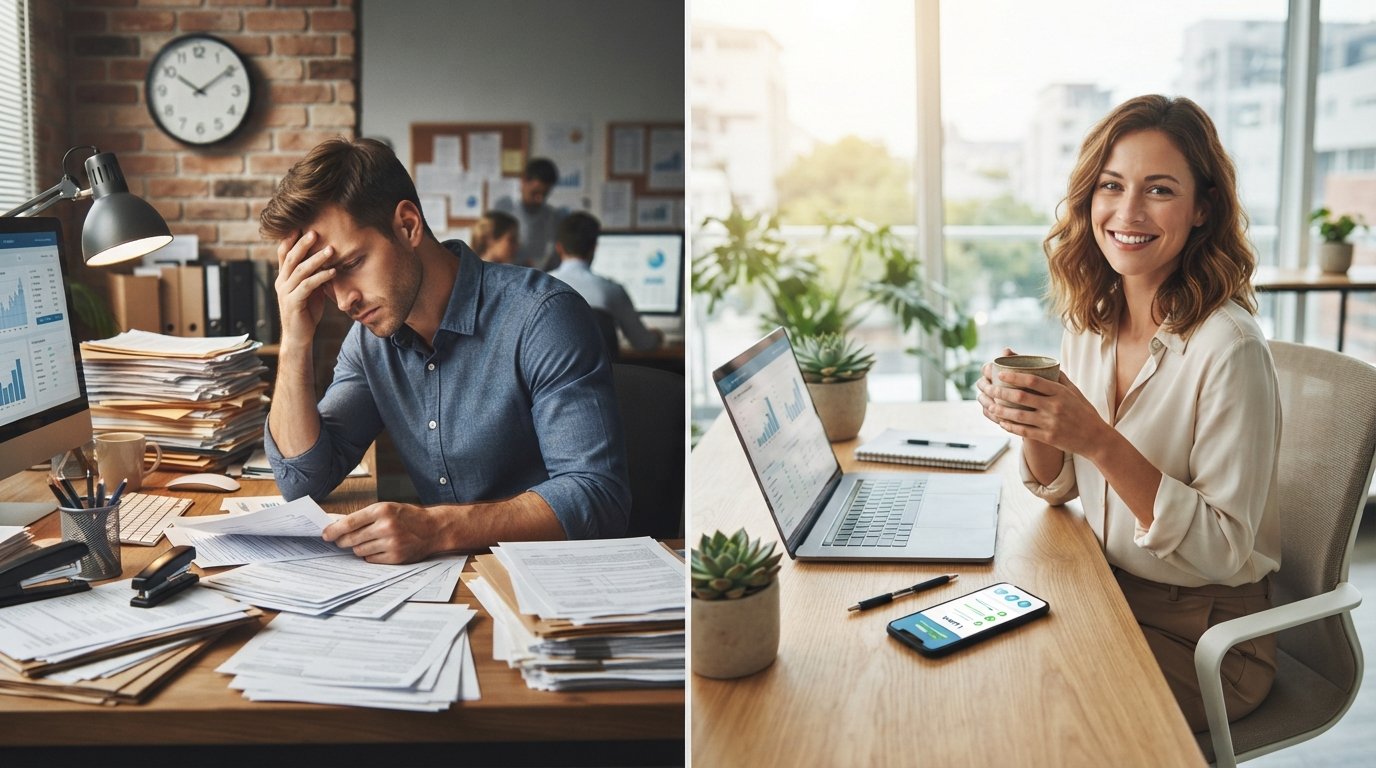
When you need cash fast, the difference between waiting days for a bank approval and submitting a single online request can feel like the difference between solving your problem and watching it grow. A traditional bank loan often involves branch visits, paper forms, and underwriting queues that stretch across business days. An online loan request through a connection service compresses that timeline into minutes, matching you with lenders who can fund as soon as the next business day. This speed comparison breaks down exactly where the time goes in each path, so you can choose the option that fits your urgency without sacrificing clarity.
The Real-Time Cost of Traditional Bank Loan Applications
Traditional bank loans are not slow by accident. They are built around risk controls, regulatory checks, and layered approvals that have developed over decades. When you walk into a branch or start a bank application online, you are entering a process designed for thoroughness, not velocity. The first bottleneck is often the paperwork itself: proof of income, tax returns, bank statements, identification documents, and sometimes collateral documentation. Gathering these items can take hours or days depending on how organized your records are.
Once submitted, your application enters an underwriting queue. A loan officer reviews your credit history, debt-to-income ratio, employment stability, and the bank's internal lending criteria. For personal loans, this review can take one to five business days, and that is before final approval and funding. If the loan requires collateral, such as an auto loan or home equity product, add appraisal or title work to the timeline. Branch hours also constrain the process: if you miss a call or need to sign a document in person, you may lose another day.
The speed of a traditional bank loan depends heavily on the loan type and the institution. Small personal loans under $5,000 may move faster at community banks, sometimes funding within two to three business days. Larger loans or those requiring manual underwriting can stretch to a week or more. The trade-off is predictability: banks follow clear, documented processes, and your loan officer can explain exactly where your file stands. But when the need is urgent, that predictability can feel like delay.
How an Online Loan Request Compresses the Timeline
An online loan request through a connection service works differently. Instead of applying to one lender and waiting for that lender's decision, you submit a single request that is shared with a network of independent third-party lenders. These lenders compete for your business by reviewing your information and presenting offers that fit their criteria. The entire request typically takes under five minutes to complete, and you can do it from your phone at any hour, including nights and weekends.
The speed advantage comes from three factors. First, the request form is short: basic personal information, income details, and banking information for direct deposit. Second, the matching process is automated, so lenders receive your request almost instantly. Third, lenders in these networks are accustomed to working with borrowers who have less-than-perfect credit, so they have streamlined their own review processes to deliver decisions quickly. You are not waiting for a committee; you are waiting for a lender's algorithm and a quick human check.
For a realistic comparison, consider the steps involved in each path. The table below summarizes the typical timeline from start to funds in hand, based on common experiences with bank personal loans and online connection services.
- Traditional bank loan: Gather documents (1 to 3 days), submit application (30 to 60 minutes), underwriting review (1 to 5 business days), approval and signing (1 day), funding (1 to 2 business days). Total: often 3 to 8 business days.
- Online loan request via connection service: Complete request (under 5 minutes), receive offers (minutes to a few hours), review and accept offer (15 to 30 minutes), lender verification (same day), funding (as soon as next business day). Total: often 1 to 2 business days.
These timelines are not guarantees, and they vary by lender, loan amount, and your financial profile. But the pattern is consistent: the online request removes the branch visit, the paper shuffle, and the multi-day underwriting queue. It replaces them with a single digital form and a network of lenders who are motivated to respond quickly. For borrowers facing an unexpected car repair or a medical bill due tomorrow, that difference is not just convenience; it is the difference between resolving the emergency and watching it compound.
Inside LendersCashLoan's Three-Step Request Process
LendersCashLoan is a digital loan connection service, not a direct lender. That distinction matters for speed because the platform is designed to move your request to multiple lenders at once rather than processing it through a single institution's pipeline. The process is intentionally simple and can be completed in three steps, typically in under five minutes.
- Submit your request: You provide basic information about yourself, your income, and your banking details. The form is secure and uses 256-bit SSL encryption, and there is no cost to submit a request.
- Review offers from lenders: Your request is shared with a network of independent third-party lenders. If a lender is interested, they present an offer with terms, including the amount, repayment schedule, and fees. You are under no obligation to accept any offer.
- Accept and receive funds: If you choose an offer, you complete the lender's verification steps and sign the agreement electronically. Once approved, funds are typically deposited directly into your bank account, often as soon as the next business day.
This three-step structure is the core of the speed advantage. There is no branch appointment, no faxing of documents, and no waiting for a single loan officer to return from lunch. The platform is built for people who need to act quickly, including those with bad credit, repossession, or bankruptcy in their past, as long as they meet basic income and age requirements. The service is free to use, and the request does not affect your credit score in the way a formal bank application might, because it is a request for offers, not a direct loan application with one lender.
It is important to understand that LendersCashLoan does not make lending decisions or fund loans directly. The speed you experience after accepting an offer depends on the lender you choose. Some lenders can verify and fund within hours; others may take a full business day. But the request phase, which is where traditional banks lose the most time, is compressed to minutes. For a deeper look at how lenders evaluate requests, see our guide on lender risk assessment for borrowers, which explains what happens behind the scenes when a lender reviews your information.
Why Funding Can Arrive as Soon as the Next Business Day
The phrase "as soon as the next business day" is common in online lending, and it is worth understanding what makes it possible. Traditional banks often batch their funding runs at the end of the day, and ACH transfers can take one to two business days to settle. Online lenders in connection networks have optimized for speed because they compete on it. They use automated verification systems, direct deposit integration, and real-time decision engines that can approve a loan and initiate a transfer within the same day.
Several factors determine whether you actually receive funds the next business day. The time of day you accept the offer matters: lenders often have cutoff times for same-day funding initiation, typically in the afternoon. Your bank's deposit policies also play a role; some banks post ACH credits faster than others. Weekends and holidays can add a day because traditional banking systems do not process transfers on those days. Finally, the lender's own verification requirements can affect timing. If your information matches easily and no additional documents are needed, funding moves quickly. If the lender needs to verify employment or income manually, it may take an extra day.
For borrowers with urgent needs, this speed is the primary reason to consider an online loan request over a bank loan. A payday loan or installment loan through a connection service can bridge a gap that a bank cannot close in time. However, speed should not be the only consideration. Short-term loans often carry higher annual percentage rates than bank personal loans, and they are not a long-term financial solution. The key is to use the speed for its intended purpose: covering a genuine, temporary emergency, and then repaying according to the agreed schedule.
When a Traditional Bank Loan Still Makes Sense
Despite the speed advantage of online requests, traditional bank loans remain the better choice in several situations. If you have strong credit, a stable income, and time to wait, a bank personal loan will almost always offer a lower interest rate and more favorable repayment terms. Banks also provide access to larger loan amounts, secured products like home equity lines of credit, and the ability to build a long-term relationship that can benefit you in the future. For debt consolidation with a significant balance, a bank loan's lower APR can save hundreds or thousands of dollars over the life of the loan.
Bank loans also offer a level of consumer protection and transparency that some online lenders may not match. You can sit down with a loan officer, ask questions, and review the full contract before signing. If you are planning a major purchase, such as a home renovation or a vehicle, and you do not need the money immediately, the bank's slower pace is a feature, not a bug. It gives you time to compare offers, negotiate terms, and make a deliberate decision.
Another situation where banks win is when you need a secured loan or a loan with a co-signer. These products are less common in online connection networks, which tend to focus on unsecured short-term loans. If you have collateral or a creditworthy co-borrower, a bank can often structure a better deal. The choice between an online loan request and a traditional bank loan is not about which is universally better; it is about matching the tool to the timeline and the cost.
When a Connection Service Fits Better
An online loan request through a service like LendersCashLoan fits best when speed and accessibility are the top priorities. If you are facing an unexpected expense that cannot wait, such as a car repair, a medical bill, or a utility shutoff notice, the multi-day timeline of a bank loan may not work. A connection service lets you submit one request and see offers from multiple lenders, which can be faster than applying to several banks individually. It also welcomes applicants with less-than-perfect credit, who might be declined by a traditional bank's strict criteria.
The service is also useful if you are unsure which lender will approve you. Instead of guessing and filling out multiple applications, you submit one request and let lenders come to you. This reduces the number of hard credit inquiries and saves time. For borrowers who need a small amount, typically $100 to $5,000, the connection model is well suited because many lenders in these networks specialize in that range. You can learn more about the process and responsible borrowing practices at 4Payday, which offers educational resources and connects consumers with short-term loan options.
It is important to approach any short-term loan with clear eyes. These products are designed for temporary cash flow gaps, not for long-term financing. Before accepting an offer, review the APR, the repayment schedule, and any fees. Make sure you can repay the loan on time without borrowing again. If you are using the loan to consolidate debt, consider whether a lower-interest bank loan or a nonprofit credit counselor might be a better fit. Speed is valuable, but it should not come at the cost of your financial stability.
Key Takeaways for Choosing Your Path
The speed comparison between an online loan request and a traditional bank loan comes down to a few practical differences. Banks are built for thoroughness and lower rates; online connection services are built for speed and accessibility. Neither is inherently better, but one will fit your situation more closely. Use the following list as a quick reference when deciding.
- Choose a bank loan if: you have good credit, can wait several business days, want the lowest possible APR, need a large amount, or prefer a secured product with collateral.
- Choose an online loan request if: you need funds urgently, have less-than-perfect credit, want to compare multiple offers quickly, need a small amount, or cannot visit a branch during business hours.
- Always compare the total cost: a faster loan with a higher APR can cost more than a slower loan with a lower rate. Calculate the total repayment amount, not just the monthly payment.
- Read the terms before accepting: whether you choose a bank or an online lender, understand the fees, repayment schedule, and consequences of late payment.
For borrowers who decide that speed matters most, LendersCashLoan provides a streamlined path to request offers from a network of independent lenders. The process is free, takes under five minutes, and is designed to connect you with lenders who can fund as soon as the next business day. You can start the request process and see what offers are available without obligation. Just remember that short-term loans are a tool for emergencies, not a permanent solution, and responsible borrowing means borrowing only what you can repay.
The right choice depends on your timeline, your credit profile, and your ability to repay. A traditional bank loan rewards patience with lower costs. An online loan request rewards urgency with speed. By understanding where the time goes in each process, you can make a decision that solves your immediate problem without creating a larger one later.