
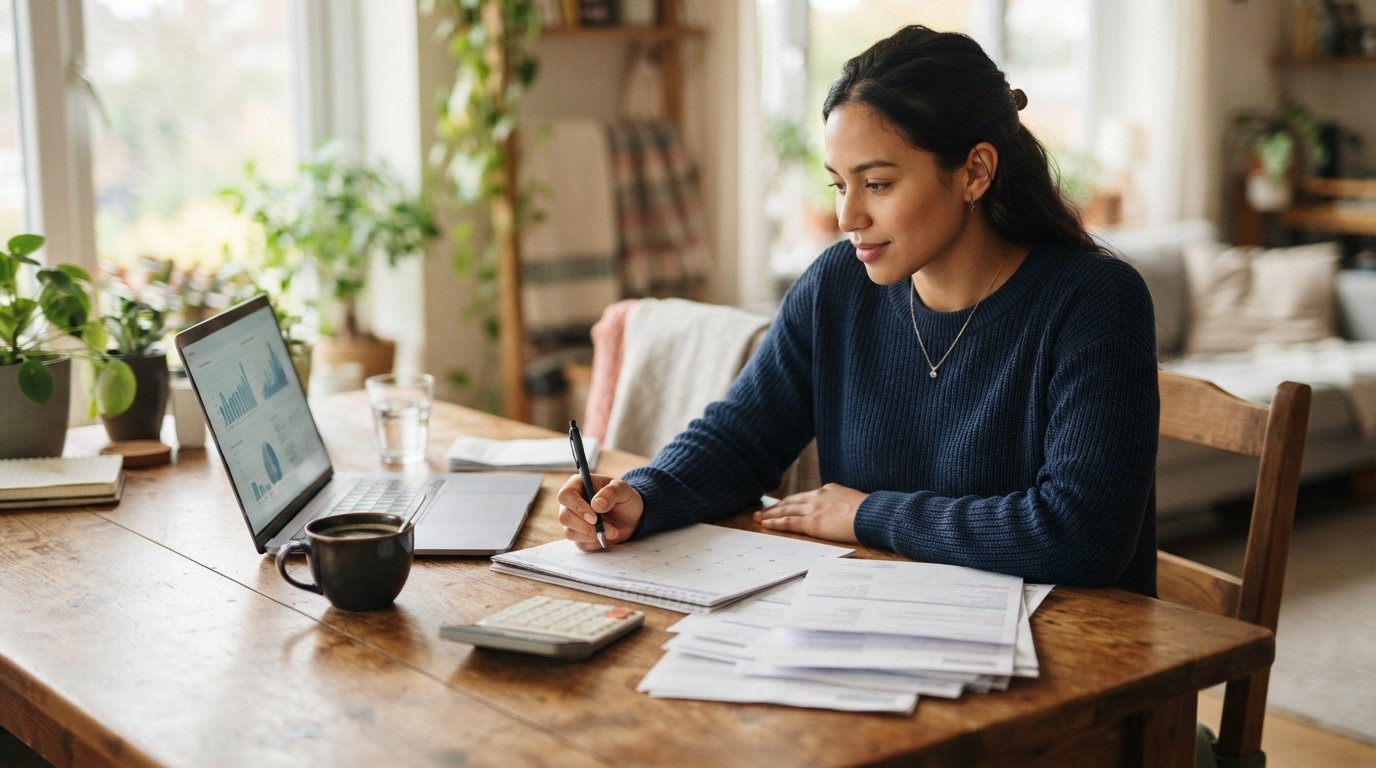
Plan Your Loan Repayment Strategy Before You Accept
Plan your loan repayment strategy before accepting any offer to avoid surprises and save money. Call (833)-501-3363 for guidance.
By Liam Torres
You have just received a loan offer, and the money could be in your account as soon as tomorrow. Before you click accept, pause. The difference between a loan that helps you and one that traps you often comes down to a single step: planning your repayment strategy before you sign. A repayment strategy is not just a schedule of payments; it is a realistic map of how you will fit those payments into your life without derailing your other financial obligations. In this guide, you will learn how to plan a repayment strategy before accepting a loan offer, so you can borrow with confidence and avoid surprises.
Start With Your Income and Due Dates
The first step in any repayment plan is to align your loan due dates with your income cycle. Most lenders set fixed due dates, often monthly or biweekly, but they may not match your pay schedule. If you get paid on the 1st and the 15th, a due date on the 10th could force you to juggle bills or risk a late payment. Before accepting an offer, pull up your calendar and bank statements. List every income source and the dates you receive them. Then, map the loan's due dates onto those income dates. If the due date falls before your next paycheck, you will need to set aside money from the previous check or negotiate a different date. Many lenders allow you to choose your due date when you accept the offer, so take advantage of that flexibility.
Once you have the dates aligned, calculate the exact amount you need to set aside from each paycheck. For example, if your loan payment is $200 per month and you get paid twice a month, you might set aside $100 from each check. This approach prevents the lump-sum shock of a single large payment. It also helps you avoid dipping into funds earmarked for rent, groceries, or utilities. Remember that LendersCashLoan is not a lender; it connects you with third-party lenders who set their own terms. So when you receive offers through our service, review the due dates carefully and choose the one that fits your income rhythm.
Review All Loan Terms Before You Commit
Before you accept any loan offer, read every line of the agreement. The annual percentage rate (APR), finance charges, late fees, prepayment penalties, and the total cost of credit are not just fine print; they determine how much the loan truly costs you. A low monthly payment can hide a high APR, especially with short-term loans. For instance, a payday loan might charge $15 per $100 borrowed, which sounds small until you realize the APR can exceed 400%. Installment loans may have lower APRs but longer terms, meaning you pay more interest over time. Understanding these numbers is essential to planning a repayment strategy that does not bleed you dry.
Also, check for any conditions that could change your repayment plan. Some lenders require automatic withdrawals, which means you must ensure sufficient funds in your account on the due date. Others may offer a grace period, but missing it triggers late fees. Look for prepayment penalties: if you plan to pay off the loan early, you do not want to be charged for it. Finally, confirm whether the lender reports to credit bureaus. On-time payments can help your credit, but late payments can hurt it. Knowing these details upfront allows you to build a repayment strategy that accounts for all possible costs and avoids unpleasant surprises.
Adjust Your Budget to Accommodate the Loan Payment
Once you know the loan amount, APR, and due dates, it is time to adjust your budget. Start by listing your essential expenses: housing, utilities, food, transportation, insurance, and minimum debt payments. Subtract these from your income to see what is left. If the loan payment fits comfortably within that leftover amount, you are in good shape. If not, you need to decide what to cut or pause while the loan is outstanding. This might mean reducing dining out, pausing subscription services, or delaying non-essential purchases. The goal is to protect your essential expenses and avoid borrowing again to cover them.
Consider creating a separate category in your budget for the loan payment. Treat it as a non-negotiable bill, just like rent. If you use budgeting apps, set up a recurring reminder or automatic transfer to a savings account earmarked for the loan. This approach ensures the money is there when the payment is due. Also, think about irregular expenses that might pop up during the loan term, such as car repairs or medical bills. Having a small cushion can prevent you from missing a loan payment when an unexpected cost arises. Remember, short-term loans are not a long-term financial solution; they should be used strategically, and your budget should reflect that.
Build a Cushion for the Final Payment
Many borrowers focus on making the monthly payments but forget about the final payment. For installment loans, the last payment might be the same as the others, or it could be a balloon payment that is significantly larger. If it is a balloon payment, you need to plan for it from day one. Even if it is not, having a cushion for the final payment can give you peace of mind and flexibility. For example, you might set aside an extra $20 or $50 each month in a savings account. By the time the final payment is due, you will have a buffer that covers any shortfall or allows you to pay off the loan early without stress.
This cushion also serves as an emergency fund. If you lose your job or face an unexpected expense, you can use the cushion to keep up with loan payments and avoid default. Building a cushion is especially important for short-term loans, which often have high stakes and tight deadlines. By planning ahead, you turn a potential crisis into a manageable situation. And if you pay off the loan early, the cushion can be redirected to other financial goals, such as saving for a home or paying down other debts.
Evaluate the Total Cost and Explore Alternatives
Before you accept a loan offer, calculate the total cost of credit: the sum of all payments over the life of the loan. Compare that to the amount you are borrowing. If the total cost seems high, consider alternatives. Could you borrow a smaller amount? Could you extend the term to lower monthly payments, even if it means paying more interest overall? Or could you find a loan with a lower APR? Sometimes, a credit card cash advance or a personal loan from a bank might be cheaper, but those options depend on your credit score and may not be available quickly. As a loan connection service, LendersCashLoan can help you compare offers from multiple lenders, but the decision is yours. Use our loan payoff calculator to see how different payment amounts affect your payoff timeline and total interest.
Another alternative is to negotiate with the lender. Some lenders are willing to adjust due dates or lower fees if you explain your situation. It never hurts to ask. Also, consider whether you can increase your income temporarily through overtime or a side gig to cover the loan payments without cutting essentials. The key is to explore all options before committing, so you do not feel trapped by the first offer you receive.
Create a Written Repayment Plan and Stick to It
Writing down your repayment plan makes it real and holds you accountable. Include the following elements:
- The loan amount, APR, and total cost of credit
- The due dates and payment amounts
- The income sources you will use to make payments
- The budget adjustments you will make
- Your cushion amount and where you will keep it
- A plan for what you will do if you miss a payment or face a financial emergency
Review this plan weekly or monthly to ensure you are on track. If you see that you are falling behind, take action immediately: contact the lender, adjust your budget, or use your cushion. Do not wait until the due date to realize you do not have the funds. Communication with your lender is crucial; many are willing to work with you if you reach out before you miss a payment. And remember, LendersCashLoan is here to help you connect with lenders, but we do not make lending decisions. Our role is to facilitate the connection, so you can focus on choosing the right offer and planning your repayment.
Finally, consider setting up automatic payments if the lender allows it. Automation reduces the risk of forgetting a payment and helps you stay consistent. Just make sure you have enough money in your account before the withdrawal date. If you prefer manual payments, set reminders on your phone or calendar. The goal is to make repayment as effortless as possible, so you can focus on your financial goals.
Consider the Impact on Your Credit and Future Borrowing
Your repayment behavior on this loan will affect your credit score and your ability to borrow in the future. On-time payments can improve your credit, while late payments or defaults can damage it for years. Before accepting an offer, ask yourself: can I realistically make every payment on time? If the answer is uncertain, you may want to reconsider the loan amount or term. A smaller loan with a longer term might have higher total interest, but it could be more manageable and less risky for your credit.
Also, think about how this loan fits into your overall financial picture. If you already have multiple debts, adding another loan could increase your debt-to-income ratio and make it harder to qualify for future loans. In that case, you might benefit from a debt consolidation loan, which combines multiple debts into one payment, potentially lowering your monthly obligations. However, consolidation loans come with their own risks, such as extending your repayment period and paying more interest overall. Weigh the pros and cons carefully, and consider seeking advice from a financial counselor if you are unsure.
When you use a loan connection service like LendersCashLoan, you can submit one request and receive offers from multiple lenders. This saves time and allows you to compare terms side by side. But remember, we are not a lender and do not make credit decisions. We simply connect you with lenders who may offer you a loan. It is your responsibility to review the terms and choose the best option for your situation. For additional resources and to compare offers, you can visit FreeQuotes.Loans to explore personalized loan options from a network of third-party lenders.
Final Steps Before You Accept
You have mapped your income, reviewed the terms, adjusted your budget, built a cushion, and written your plan. Now, take a moment to double-check everything. Confirm the loan amount, APR, and total cost. Verify the due dates and payment amounts. Ensure you have a clear plan for each payment and a backup plan for emergencies. If anything feels off, ask the lender for clarification. It is better to ask questions now than to face surprises later. Once you are satisfied, you can accept the offer with confidence, knowing you have a solid repayment strategy in place. And if you need help finding offers, LendersCashLoan is here to connect you with trusted lending partners quickly and securely.
Planning your repayment strategy before accepting a loan offer is a powerful habit that can save you money, reduce stress, and protect your credit. By following these steps, you take control of your financial future and make borrowing a tool for progress, not a source of anxiety. Start today, and make your next loan a smart one.