
Saving Strategies to Avoid Needing an Emergency Loan Again
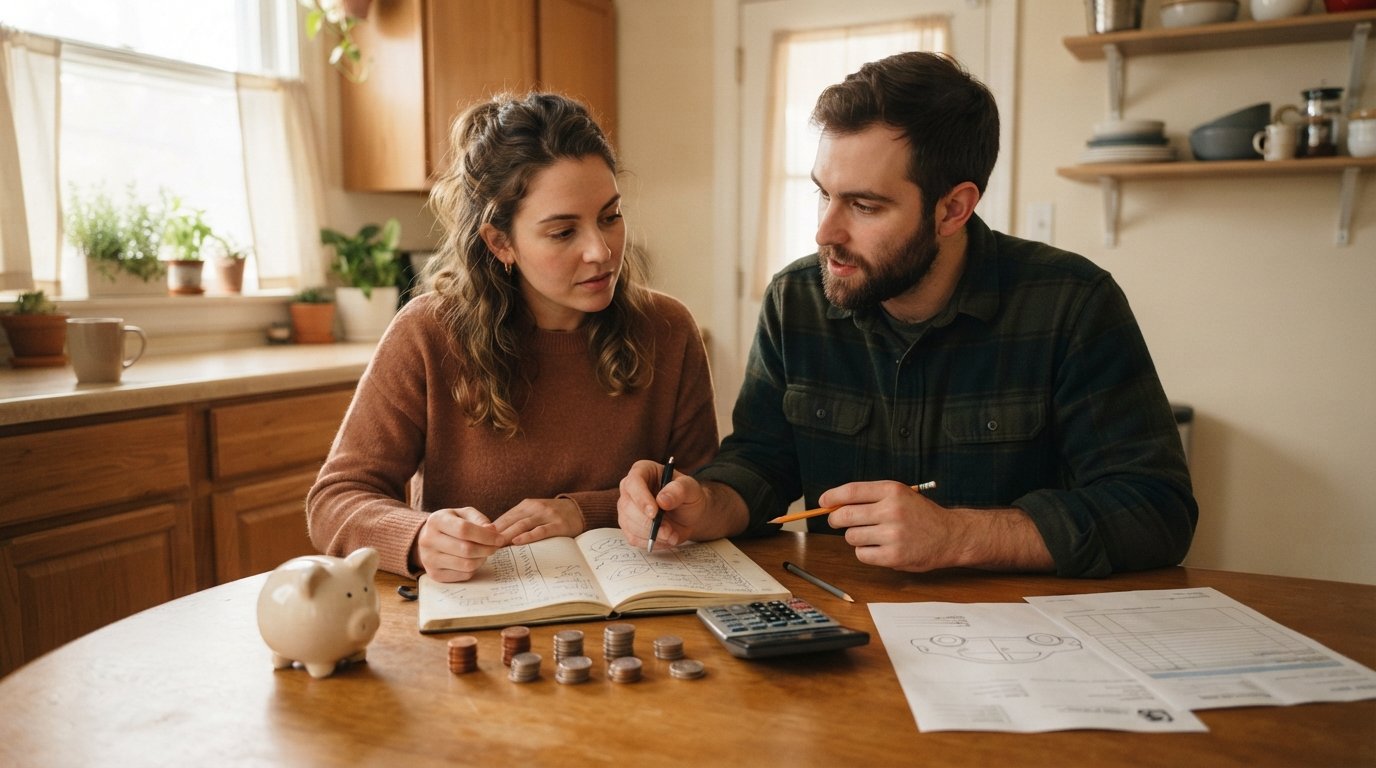
Small automatic transfers, sinking funds, and spending reviews build a buffer that keeps you from needing an emergency loan again.
You said you would never do it again. Yet here you are, staring at a car repair estimate or a medical bill, wondering how you ended up applying for another emergency loan. If that cycle feels familiar, the problem is not your willpower. It is the absence of a system built for real life, one that expects surprises and prepares for them. The good news is that you do not need a six-figure salary or a perfect credit score to stop relying on emergency borrowing. What you need is a set of saving strategies to avoid needing an emergency loan again, strategies that work even when money is tight and motivation is low. This guide walks you through practical, repeatable steps that turn small, consistent actions into a financial buffer strong enough to absorb the next shock without a loan application.
Why You Needed an Emergency Loan in the First Place
Most people who take out a short-term loan are not reckless. They are simply unprepared for a timing mismatch: a bill arrives before the paycheck does, or three expenses land in the same week. Research and common experience suggest that a large share of adults could not cover a $400 emergency without borrowing or selling something. That is not a character flaw; it is a liquidity gap. Understanding this distinction matters because it reframes the solution. You are not trying to become a different person overnight. You are trying to close a specific gap with a repeatable process.
There is also a behavioral side. Many borrowers recognize, in hindsight, that their past loan was triggered by a predictable event they could have seen coming: car registration, insurance premiums, school supplies, or holiday spending. Others notice a spending pattern, such as a weekend of convenience purchases that slowly erodes the cushion they meant to build. Identifying your personal trigger is the first real step. Once you know what tends to knock you off balance, you can design savings around it instead of hoping next month will be different.
Finally, there is the emotional angle. Emergency loans often feel like the only option because they are fast and require little paperwork. But speed comes at a cost, and the relief is temporary. Building a modest savings habit does not deliver the same instant gratification, yet it delivers something far more valuable: the ability to say no to expensive credit because you already have the cash. If you want a deeper look at how fast-cash lending works and what it truly costs, our guide on emergency personal loans for fast cash walks through the mechanics. The goal here is to make sure you need that option less often.
Start Small: The Automatic Transfer That Fits a Tight Income
The biggest mistake people make when trying to build savings is aiming too high too soon. They commit to $200 a month, miss the first transfer, feel defeated, and give up. A better approach is to start with an amount so small it barely registers, then let consistency do the heavy lifting. Even $10 or $15 per week adds up faster than most people expect, and the habit matters more than the number in the early months.
Automation is the key. A manual transfer requires a decision every single time, and decisions are vulnerable to temptation and forgetfulness. Set up an automatic transfer from your checking account to a separate savings account on the day after payday. Choose an amount you are confident you can leave alone. If your income is irregular, schedule the transfer for the day you typically receive funds, or split it into two smaller transfers per month. The point is to make saving the default rather than a monthly negotiation with yourself.
Here is a simple framework for choosing your starting amount and scaling it over time:
- Calculate your smallest comfortable cushion: look at last month and identify the amount you could have set aside without missing a bill. That number, even if it is $20, is your starting point.
- Open a separate high-yield savings account and name it after your goal (for example, "Car Repair Fund") so you are less tempted to raid it.
- Set the automatic transfer for the day after your paycheck clears, and treat it like a bill you cannot skip.
- Every three months, increase the transfer by a small increment, such as $5 or 1 percent of your income, until you reach a comfortable ceiling.
This approach works because it respects the reality of a tight budget while still building momentum. You are not trying to save your way to wealth in a month. You are trying to create a floor beneath your finances so that a single unexpected expense does not send you back to a lender. Over a year, a $15 weekly transfer becomes roughly $780, which covers many common emergencies on its own. Combine that with even modest expense cuts, and the buffer grows faster than you might think.
Sinking Funds: Preparing for Costs You Know Are Coming
Not every emergency is truly unexpected. Car registration, insurance deductibles, back-to-school costs, and holiday gifts arrive on a predictable schedule, yet they often catch people off guard because the money was never set aside. A sinking fund solves this by breaking a large, irregular expense into smaller monthly contributions. It is one of the most effective saving strategies to avoid needing an emergency loan again because it removes the element of surprise from your budget.
To set up a sinking fund, list the irregular expenses you know you will face in the next twelve months. Estimate the total cost for each one, divide by the number of months until it is due, and set aside that amount each month. For example, if your car registration and insurance together cost $900 and are due in nine months, you would save $100 per month in a dedicated account. When the bill arrives, the money is already there, and you never have to choose between paying it and covering groceries.
Here are the categories where sinking funds tend to deliver the biggest relief:
- Vehicle costs: registration, inspections, tires, and routine maintenance.
- Insurance: deductibles and premiums that fall outside your monthly budget.
- Annual or seasonal expenses: holidays, birthdays, school supplies, and travel.
- Home and appliance repairs, which are inevitable even if the timing is unknown.
- Medical and dental costs that are not fully covered by insurance.
Once these funds are in place, you will notice a shift in how you experience those bills. They stop feeling like emergencies and start feeling like planned events. That psychological shift is just as important as the cash itself, because it reduces the panic that often leads to rushed borrowing decisions.
Turn Your Paid-Off Loan Payment Into a Savings Deposit
If you have recently paid off a loan, you are in a powerful position. You have already proven you can live without that money each month. The mistake many people make is absorbing the freed-up cash into general spending, where it quietly disappears. A smarter move is to redirect the entire payment into your savings account the very next month. You will not feel the difference in your lifestyle, but your emergency fund will grow quickly.
This strategy works best when you automate it immediately. The day your final payment clears, log into your bank and set up a recurring transfer for the same amount and the same date. Treat it as a non-negotiable expense, just as you treated the loan payment. If the payment was $150 every two weeks, you have just built a $300-per-month savings habit without changing your day-to-day spending at all. Within six months, you could have $1,800 set aside, which covers a wide range of emergencies.
There is an important caveat here. If you are still carrying other high-interest debt, you may need to balance saving with debt repayment. A common approach is to split the freed-up payment: direct part of it to savings and part to the next debt. The exact ratio matters less than the consistency. What you want to avoid is letting the money vanish into everyday expenses, because that leaves you exposed the next time an unexpected bill arrives.
Recognize the Spending Patterns That Triggered Past Borrowing
Savings strategies only work if they survive contact with real life. That means understanding the behaviors that drained your money in the past. For many people, the trigger is not a single large purchase but a series of small, convenient ones: food delivery, impulse buys, subscriptions that renew unnoticed. These expenses rarely feel significant in the moment, yet together they can consume the very cushion you are trying to build.
Start by reviewing two or three months of bank and card statements. Look for recurring charges you no longer use, categories where spending spikes predictably, and moments when your balance dipped dangerously low. You are not looking for reasons to feel guilty. You are looking for patterns you can interrupt with a rule or a small system. For example, if you notice that your account tends to run low the week before payday, you can schedule your automatic savings transfer for the day after payday and set a weekly cash limit for discretionary spending.
Another powerful tactic is the 24-hour rule for non-essential purchases. When you feel the urge to buy something outside your budget, write it down and wait a day. Many purchases lose their appeal overnight, and the money stays in your account. Pair this with a weekly review of your spending, perhaps ten minutes every Sunday, to catch drift before it becomes a crisis. Over time, these small behavioral adjustments free up more cash than most people expect, and that cash becomes the foundation of your emergency fund.
Build a Buffer That Makes Emergency Loans Unnecessary
The ultimate goal is not just to save a little money but to create a buffer large enough that ordinary emergencies no longer derail you. Financial experts often recommend an emergency fund covering three to six months of essential expenses, but that target can feel overwhelming when you are starting from zero. A more realistic milestone is a starter buffer of $500 to $1,000, which covers the majority of common emergencies such as a car repair, a medical copay, or a sudden travel expense. Once you hit that milestone, you can aim higher with confidence.
Keep your emergency fund in a separate, easily accessible account, ideally one that earns a modest amount of interest. The separation matters because it reduces the temptation to spend the money on non-emergencies. Define in advance what counts as an emergency: a necessary repair, a medical need, or a sudden loss of income, not a sale or a spontaneous trip. Having a clear definition helps you protect the fund when your resolve is tested.
If you do find yourself facing a gap despite your best efforts, it helps to know your options before you are in crisis. Services like StartCashLoan connect consumers with third-party lenders through a simple online request, and they also publish plain-language guides on borrowing and budgeting. Understanding how these services work, and what they cost, can help you make a calmer decision if a true emergency arises. But the ideal outcome is that your savings buffer handles the situation first, and borrowing becomes a last resort rather than a reflex.
Building that buffer takes time, and progress may feel slow at first. That is normal. The important thing is to keep the system running: automate your transfers, maintain your sinking funds, redirect paid-off loan payments, and review your spending regularly. Each of these saving strategies to avoid needing an emergency loan again reinforces the others, and together they create a financial cushion that grows month after month. You may not eliminate every surprise, but you can make sure the next one does not send you back to the lender.
The cycle of emergency borrowing is breakable, and it starts with a single automated transfer, a small sinking fund, and a willingness to look honestly at your spending. None of these steps require a perfect credit score or a sudden windfall. They require consistency and a plan that accounts for real life. Start with one step this week, then add another next month. Before long, you will have something more valuable than a quick loan: the quiet confidence of knowing you can handle what comes next.