
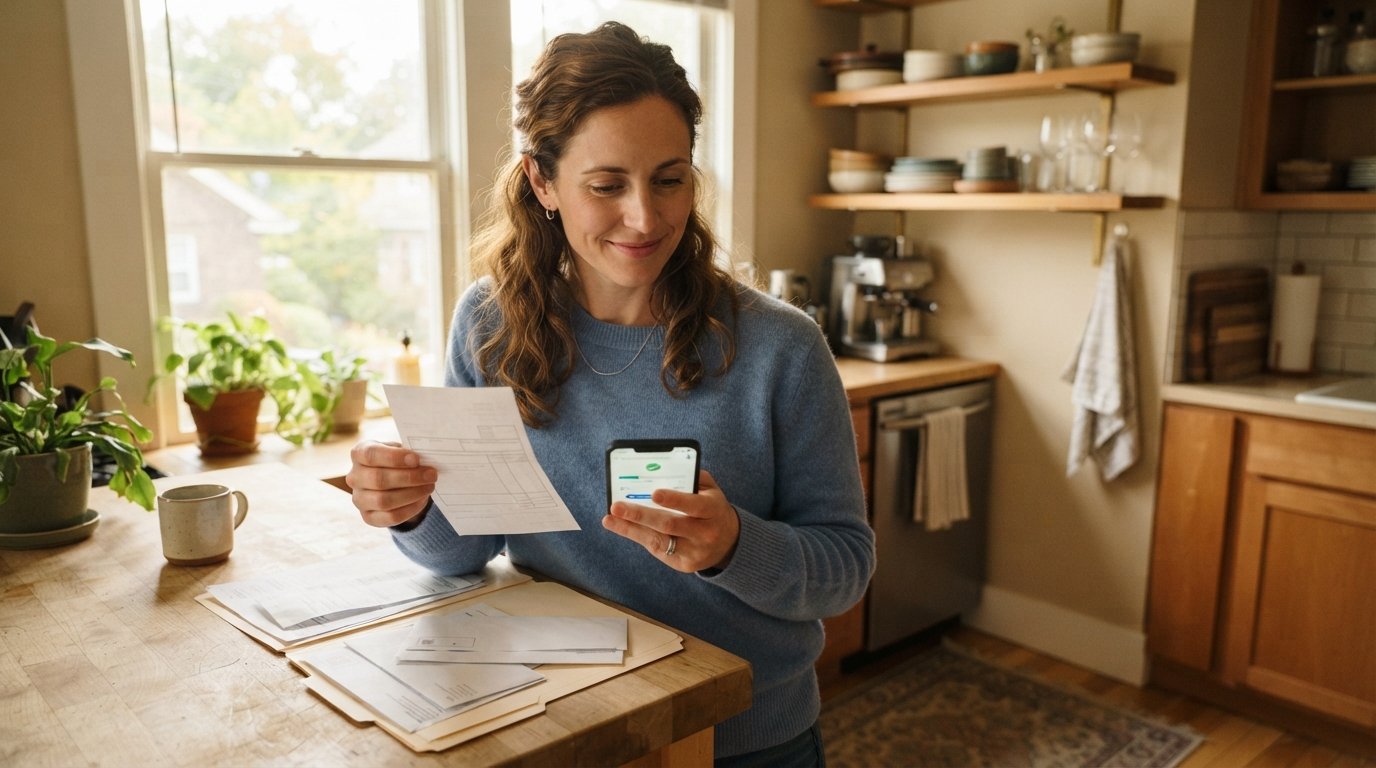
How Rent Payment Data Helps Bad Credit Loan Approval
Rent payments and other alternative data can help lenders see beyond a low credit score, potentially improving your chances of loan approval.
By Liam Torres
Your rent check clears every month like clockwork. Your utilities are paid on time. Your phone bill never goes overdue. Yet when you apply for a loan, your credit score tells a different story, one shaped by a past bankruptcy, a repossession, or a few missed payments years ago. That gap between how you handle money today and what your credit report shows is exactly why alternative data matters. Lenders are increasingly looking beyond traditional credit scores, and rent payments are one of the most powerful pieces of evidence you can bring to the table. Understanding how alternative data like rent payments helps bad credit loan approval can change the way you approach your next loan request.
Why Traditional Credit Scores Miss Good Borrowers
Credit scoring models like FICO and VantageScore rely on information reported to the three major credit bureaus: Equifax, Experian, and TransUnion. Your payment history on credit cards, auto loans, mortgages, and student loans makes up the largest portion of your score. But here is the problem: rent payments, utility bills, and phone bills are not automatically reported to those bureaus. If you have always paid your rent on time but never used credit, or if you have a damaged credit history from years ago, your score may not reflect your current financial reliability at all.
This creates a blind spot for lenders. A single mother who has rented the same apartment for eight years and never missed a payment might have a 580 credit score simply because she never opened a credit card. A man who went through a bankruptcy three years ago but has since paid every bill on time may still carry a score in the low 600s. Traditional credit scores are backward-looking and narrow, and they often punish people for past mistakes long after they have changed their financial habits.
That is where alternative data comes in. Lenders who want a fuller picture of your financial behavior are starting to use rent payment records, utility payment histories, and even bank transaction data to evaluate risk. For borrowers with bad credit, this is a significant opportunity. It means your current behavior can count, not just your past.
How Rent Payments Function as Alternative Credit Data
Rent is typically the largest recurring expense a household faces. When you pay rent on time every month, you are demonstrating exactly the kind of behavior lenders care about: consistent, predictable payments over a long period. Some property management companies and rent payment services report your payment history to the credit bureaus, which can directly boost your score. But even when they do not, you can still use your rental history as evidence of creditworthiness when applying for a loan through a connection service.
Here is how it works in practice. When you submit a loan request through a platform like LendersCashLoan, you are not applying to a single lender. You are submitting one request that may be shared with a network of third-party lenders. Some of those lenders use alternative data in their underwriting process. They may ask for proof of rent payments, bank statements showing consistent rent withdrawals, or access to bank transaction data through a secure verification tool. If your rent payments are on time and your income is stable, those lenders may view you as a lower risk than your credit score alone would suggest.
The key is that alternative data does not replace your credit score. It supplements it. Lenders still look at your credit report, but they also consider the evidence you provide about your current financial responsibility. For someone with a bankruptcy or repossession in their past, this can be the difference between a denial and an approval.
What Documents and Data Can Support Your Loan Request
If you want to use rent payments and other alternative data to strengthen your loan application, you need to be prepared. Not every lender will ask for the same information, but having the following documents ready can speed up the process and improve your chances. Before you submit a request, gather the items that paint the clearest picture of your financial reliability.
- Rent payment receipts or bank statements: Show at least 12 months of consistent rent payments. Bank statements that display automatic rent withdrawals are often the most credible evidence.
- Utility and phone bills: Paid receipts for electricity, water, gas, and mobile phone service demonstrate that you manage recurring obligations responsibly.
- Proof of income: Pay stubs, direct deposit records, or tax returns confirm that you have the means to repay a loan.
- Bank transaction history: Some lenders use secure tools to verify your income and spending patterns directly from your bank account.
- Rental history letter: A signed letter from your landlord confirming your payment history can be helpful, especially if your rent is not reported to the credit bureaus.
Having these documents organized before you apply makes a strong impression. It shows lenders that you are serious and that you have nothing to hide. It also reduces the risk of delays or requests for additional information later in the process.
How Alternative Data Changes Eligibility for Borrowers with Bankruptcy or Repossession
Bankruptcy and repossession are two of the most damaging events that can appear on a credit report. They can linger for seven to ten years and make it difficult to qualify for traditional loans. But they do not tell the whole story. A bankruptcy may have been caused by a medical emergency or a job loss, not by irresponsible spending. A repossession may have happened during a divorce or a period of unemployment. Lenders who rely solely on credit scores cannot see the context, but lenders who use alternative data can.
When you provide evidence of consistent rent payments, utility payments, and stable income, you are showing that the events on your credit report do not reflect your current financial behavior. Some lenders in a connection network specialize in working with borrowers who have less-than-perfect credit. They may weigh your recent payment history more heavily than your past credit problems. This does not mean you will automatically qualify, but it does mean you have a fair chance to make your case.
It is important to be honest about your credit history. Do not try to hide a bankruptcy or repossession. Instead, be ready to explain what happened and what you have done since then to stabilize your finances. Lenders appreciate transparency, and a straightforward explanation combined with strong alternative data can go a long way.
How LendersCashLoan Connects You with Lenders Who Value Alternative Data
LendersCashLoan is not a direct lender. It is a free online connection service that helps U.S. consumers find short-term and payday loan options. When you complete a single request form on the site, your information may be shared with a network of third-party lenders who can evaluate your request. Some of those lenders use alternative data like rent payments in their decision process, while others may rely more on traditional credit criteria. Because you submit one request and potentially receive multiple offers, you can compare options and choose the one that fits your situation.
The process is designed to be simple and fast. You fill out a short form with basic information about yourself, your income, and your banking details. The request typically takes less than five minutes. Once submitted, you may be matched with lenders who are interested in your profile. If a lender extends an offer, you will see the terms, including the interest rate, fees, and repayment schedule. You are under no obligation to accept any offer.
For borrowers with bad credit, this approach has a clear advantage. Instead of applying to one lender at a time and risking multiple hard credit inquiries, you can submit one request and let lenders compete for your business. And because some lenders in the network consider alternative data, your rent payment history may help you qualify for an offer even if your credit score is low. To learn more about how the connection process works and how your data is protected, you can read this guide on short term loans and personal data protection.
It is also worth noting that LendersCashLoan does not make credit decisions. Each lender in the network has its own criteria and underwriting process. The site simply connects you with lenders who may be interested in your request. You should always review the terms of any offer carefully before accepting.
Steps to Strengthen Your Loan Request with Rent Payment Evidence
If you are ready to use alternative data to improve your chances of loan approval, follow a structured approach. The steps below will help you present your rent payment history in the most favorable light and avoid common mistakes.
- Gather your payment records. Collect at least 12 months of rent receipts, bank statements showing rent withdrawals, and paid utility bills. Organize them digitally so you can upload or share them quickly.
- Check your credit report for errors. Before you apply, review your credit reports from all three bureaus. Dispute any inaccurate information that could be dragging down your score.
- Prepare a brief explanation of your credit history. If you have a bankruptcy or repossession, write a short statement explaining the circumstances and what you have done to improve your finances since then.
- Submit a request through a connection service. Use a platform like LendersCashLoan to submit one request and potentially receive multiple offers from lenders, some of whom may consider alternative data.
- Compare offers carefully. Review the APR, fees, repayment terms, and any other costs before accepting an offer. Do not accept the first offer without comparing it to others.
Following these steps does not guarantee approval, but it puts you in the best possible position. Lenders are more likely to work with borrowers who are organized, transparent, and proactive about demonstrating their reliability.
Limits of Alternative Data and Responsible Borrowing
Alternative data is a powerful tool, but it is not a magic solution. Not every lender uses it, and even lenders who do may still decline your request if your income is insufficient or if other risk factors are too high. It is also important to understand that short-term loans and payday loans are not long-term financial solutions. They are designed for temporary cash flow gaps, not for ongoing expenses or debt consolidation.
Before you borrow, take a close look at your budget. Can you afford the repayment? Will the loan payment fit comfortably within your monthly income? If the answer is no, consider other options first. You might be able to negotiate a payment plan with a creditor, access a small emergency fund, or seek help from a nonprofit credit counseling agency. Borrowing money you cannot repay can make a difficult situation worse.
If you do decide to proceed, borrow only what you need and repay it as quickly as possible. Use the loan as a bridge, not as a permanent crutch. And remember that your rent payment history is valuable beyond this one loan request. Every on-time payment builds a stronger financial foundation for the future.
Building a Stronger Financial Profile for Future Loan Requests
Using rent payments to support a loan request is just one step in a longer journey. If you want to improve your access to credit over time, focus on the habits that lenders value. Continue paying your rent and utilities on time. Consider asking your landlord to report your payments to the credit bureaus if they do not already. Open a secured credit card and use it responsibly to build a positive credit history. Keep your credit utilization low and avoid applying for multiple loans in a short period.
For borrowers with bad credit, the path to better loan options is not about erasing the past. It is about demonstrating that your present behavior is different. Alternative data like rent payments gives you a way to do that. When you pair that evidence with a clear explanation of your circumstances and a realistic budget, you give lenders a reason to say yes.
As you prepare to submit your next loan request, remember that you are not defined by your credit score. Your rent payment history, your utility payments, and your steady income tell a story that a three-digit number cannot capture. Use that story to your advantage. If you are ready to explore your options, FundingCashLoans offers a free connection service that can match you with lenders who may consider alternative data. It is a simple, no-obligation way to see what is available and take control of your financial next step.