
How to Manage Multiple Loan Payments in One Budget
A clear system to manage multiple loan payments in one budget, from listing debts to automating due dates. Call (833)-501-3363 for guidance today.
By Wesley Owens
Juggling three or four loan payments every month can feel like spinning plates on a tightrope. One due date slips, a late fee hits, and suddenly your entire budget is off balance. The good news is that managing multiple loan payments in one budget is not about earning more money or finding a magical debt cure. It is about building a single, organized system that tells every dollar where to go before the month begins. Whether you are handling a car loan, a personal installment loan, a credit card balance, and a short-term payday loan all at once, the right framework can turn chaos into a predictable routine. This guide walks through a practical, step-by-step approach you can set up this week, even if your income is modest or your credit history is less than perfect.
Start by Seeing Every Debt on One Page
You cannot manage what you cannot see. The first step in how to manage multiple loan payments in one budget is creating a complete inventory of every debt you owe. Most people carry a rough mental list, but mental lists leave out small balances, forgotten store cards, or that buy-now-pay-later plan from last holiday season. Pull your latest statements, log into each lender portal, and write down four pieces of information for every account: the current balance, the minimum monthly payment, the interest rate (APR), and the due date.
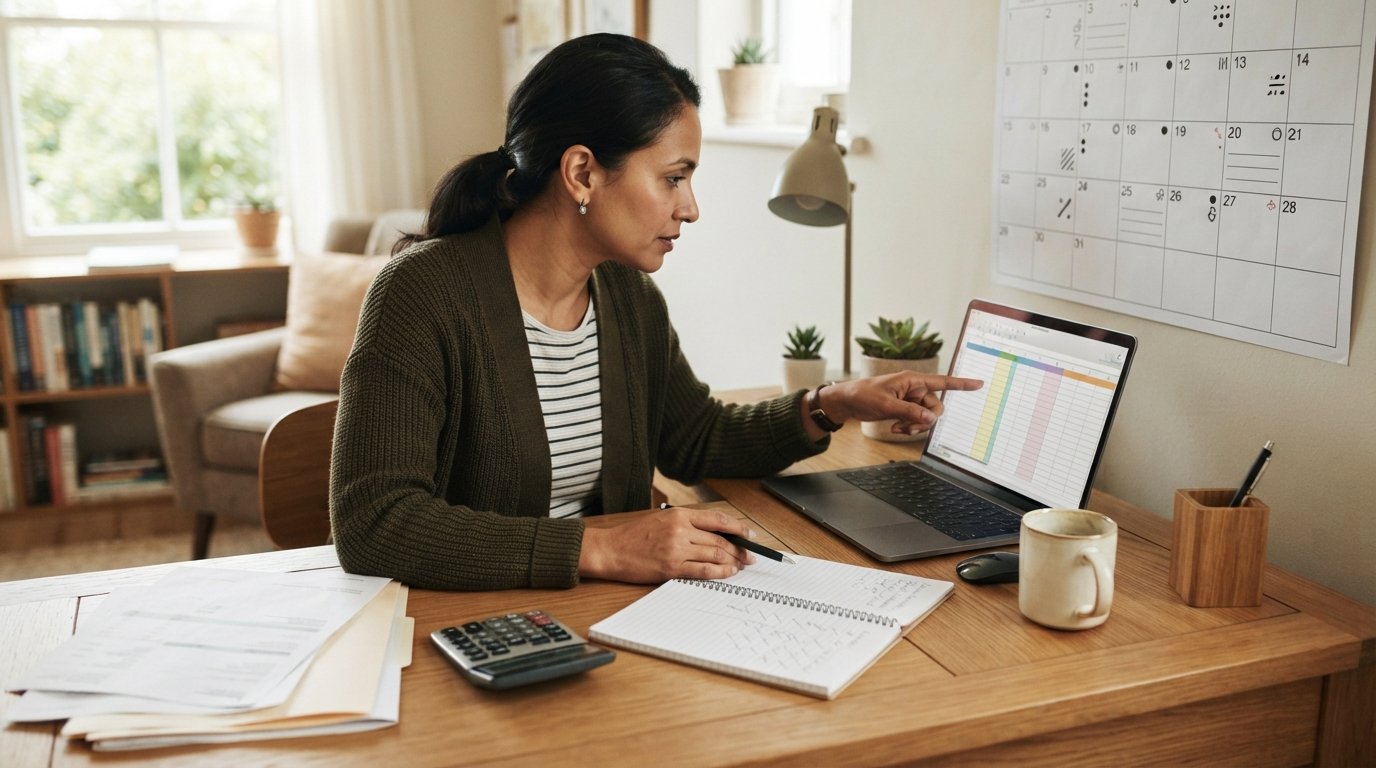
Once you have that list, organize it into a simple table or spreadsheet. If spreadsheets are not your strength, a notebook works just as well. The format matters far less than consistency. What you are building is a single source of truth that replaces scattered emails, paper bills, and half-remembered due dates. This is also the moment to check your credit report for any accounts you may have forgotten, because missed or unknown debts are often the hidden reason a budget never quite works.
After listing every debt, add up the total minimum payments. That number is your baseline obligation, the amount you must cover each month before groceries, gas, or savings. Seeing the total in one place can be sobering, but it is also freeing. A clear number is something you can plan around. A vague sense of being overwhelmed is not.
Build a Budget With Debt Payments as Fixed Lines
Most budgeting advice treats debt payments as an afterthought, something you pay with whatever is left over. That approach fails when you have multiple loans because there is rarely anything left over. Instead, treat every loan payment as a fixed expense, exactly like rent or electricity. It comes out first, not last.
A simple framework is the 50/30/20 model adapted for debt-heavy households. In a standard version, 50 percent of income covers needs, 30 percent covers wants, and 20 percent goes to savings and debt payoff. If your minimum loan payments already exceed 20 percent of your take-home pay, shift the ratios: reduce wants to 10 percent and direct that 20 percent entirely toward debt. The goal is not perfection. The goal is a written plan where every loan payment has a designated home.
If your income is low or irregular, the math gets tighter but the principle stays the same. Our guide on how to budget for a loan payment on a low income walks through strategies like zero-based budgeting, biweekly payment splitting, and prioritizing essential bills when every dollar is already committed. Combining those tactics with a multi-loan payoff plan gives you a realistic path forward.
Here is a quick checklist for setting up your budget with loan payments included:
- List your net monthly income from all sources, using the lowest reliable month as your baseline.
- Subtract fixed essentials: housing, utilities, food, transportation, insurance, and minimum loan payments.
- Assign the remaining money to variable categories like groceries, personal care, and entertainment.
- Direct any surplus toward either an emergency fund or an extra payment on your highest-priority debt.
That last bullet is where most budgets stall. People either spend the surplus without noticing or throw it at the wrong debt. The next section explains how to choose the right target.
Choose a Payoff Strategy: Snowball or Avalanche
When you have multiple loans, paying only the minimums keeps you afloat but rarely moves you forward. To make real progress, you need a payoff strategy that tells you which loan gets extra money each month. Two proven methods dominate the conversation, and both work. The best one is the one you will actually stick with.
The debt snowball method ranks your debts from smallest balance to largest. You pay minimums on everything, then throw every extra dollar at the smallest debt until it is gone. Once that balance is cleared, you roll its payment into the next smallest debt, creating a growing snowball. The appeal is psychological: quick wins build momentum and reduce the number of due dates you have to track.
The debt avalanche method ranks debts from highest interest rate to lowest. You pay minimums on everything, then attack the most expensive debt first. Mathematically, this saves the most money on interest over time. It is especially valuable when you carry high-APR debt such as payday loans or cash advances, where interest can compound quickly.
Neither method is wrong. If you need motivation, choose the snowball. If you want the lowest total cost, choose the avalanche. What matters is that you pick one, write it down, and apply extra payments consistently rather than scattering them randomly across accounts.
Automate and Consolidate Due Dates
Human memory is a terrible payment system. The single most effective upgrade to any multi-loan budget is automation. Set up autopay for every account that offers it, scheduling payments for a few days after your paycheck lands. This eliminates late fees, protects your credit score, and removes the mental load of remembering five different due dates.
If autopay is not available or you prefer manual control, consolidate your due dates instead. Call each lender and ask to move your payment date to the same week. Many lenders will accommodate this request, especially if you have a history of on-time payments. Aligning due dates means one weekly or biweekly money session can handle every obligation at once.
Another option is to open a dedicated bill-paying account. Each payday, transfer the total of your loan payments into that account. The money sits there until each autopay drafts, and you never risk spending it on something else. This simple separation turns your budget from a hopeful plan into a functional system.
If your current loan terms are unworkable, a consolidation loan may help. A single installment loan used to pay off several smaller debts can replace multiple payments with one, often at a lower rate. Platforms like FreeQuotes.Loans let you compare offers from multiple lenders with a single request, which is useful when you want to see whether consolidation would actually reduce your monthly burden before committing.
Handle High-Interest and Short-Term Debt First
Not all loans deserve equal priority in your budget. Short-term products like payday loans and cash advances often carry APRs that dwarf credit cards, sometimes exceeding 300 percent when annualized. If you have one of these in your mix, it belongs at the top of your payoff list regardless of balance size. Letting a high-APR loan roll over month after month is the fastest way to destroy a budget.
If you cannot pay a short-term loan in full by its due date, contact the lender before the deadline. Many lenders offer extensions, partial payment plans, or refinancing options, but only if you ask before you miss a payment. Ignoring the problem leads to late fees, additional interest, and potential collection activity. Proactive communication is almost always cheaper.
For persistent cash-flow gaps, a loan connection service can help you explore options. LendersCashLoan is a digital loan connection service, not a direct lender, that lets you submit one online request and potentially receive offers from a network of third-party lenders. Loan amounts typically range from $100 to $5,000, and the service welcomes applicants with less-than-perfect credit who meet basic income criteria. It is free to use and does not obligate you to accept any offer. You can learn more on the how it works page.
That said, short-term loans are not a long-term financial solution. Use them to bridge a genuine emergency, not to patch a recurring budget shortfall. If you find yourself relying on them monthly, the real fix is either increasing income, reducing expenses, or restructuring your debt through a longer-term consolidation plan.
Build a Small Emergency Buffer to Protect the Plan
Even the best multi-loan budget breaks when an unexpected expense appears. A car repair, a medical bill, or a sudden loss of hours can push you back to credit cards or payday loans, undoing months of progress. The antidote is a small emergency fund, even $500 to $1,000, kept in a separate savings account.
Fund it slowly while paying down debt. Split any extra money between the two goals rather than choosing one exclusively. A modest buffer reduces the chance that a single surprise derails your entire repayment plan, and it gives you the confidence to say no to high-cost borrowing when the next emergency hits.
Review your budget monthly. Income changes, due dates shift, and interest rates move. A 15-minute check-in at the start of each month keeps your plan accurate and prevents small problems from becoming large ones. Adjust the numbers, celebrate progress, and keep going.
Managing multiple loan payments in one budget is ultimately about control: knowing what you owe, when it is due, and which payment gets extra attention this month. Build the list, automate what you can, choose a payoff strategy, and protect the plan with a small buffer. Do that consistently, and the plates stop spinning. They simply stay in place.