
How to Use a Short Term Loan for a Tuition Deadline
Learn how to use a short term loan to cover a school tuition deadline by matching the loan to the past due amount and choosing a repayment term that fits your academic calendar.
By Sophie Hayes
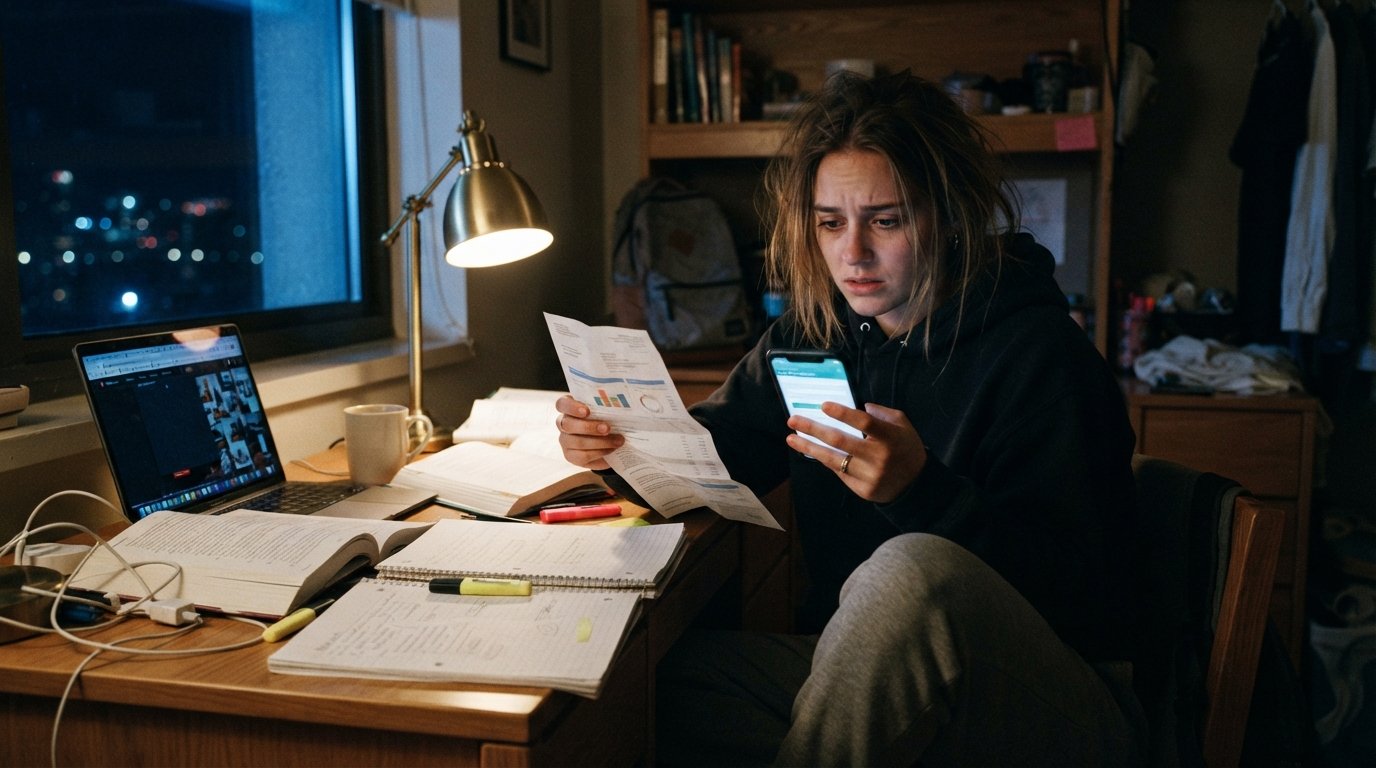
The tuition due date is looming, your bank account is short, and the bursar's office does not offer grace periods. Missing a tuition deadline can mean late fees, a hold on your account, or even being dropped from classes. In that moment of pressure, a short term loan can be a practical bridge to cover the gap. But using one wisely requires more than just applying fast; it means matching the loan amount precisely, choosing a repayment term that aligns with your academic calendar, and knowing what alternatives might reduce the cost. This guide walks you through how to use a short term loan to cover a school tuition deadline without creating a bigger financial headache.
Why a Short Term Loan Can Fit a Tuition Deadline
Tuition deadlines are fixed and often unforgiving. They do not care that your paycheck arrives three days later or that your financial aid disbursement is stuck in processing. A short term loan, typically ranging from $100 to $5,000, can provide the exact amount you need to satisfy the bursar before the penalty kicks in. Unlike long term financing, these loans are designed to be repaid quickly, often within a few weeks or months, which makes them suitable for a one time cash flow gap rather than an ongoing expense.
One key advantage of using a short term loan for a tuition deadline is speed. Many online loan connection services, including LendersCashLoan, allow you to submit a single request and potentially receive offers from multiple lenders within minutes. The application process is straightforward: you provide basic information such as your age, income, and banking details, and the service matches you with third party lenders who may offer you a loan. This can be far faster than waiting for a traditional bank loan or a financial aid appeal to be processed.
However, speed should not come at the expense of understanding. Before you borrow, you need to know exactly how much you owe, when the deadline is, and how you will repay the loan. A short term loan is a tool, not a solution to a long term funding problem. Used correctly, it can protect your enrollment and your credit; used carelessly, it can lead to a cycle of debt. The following sections break down the process into actionable steps.
Step 1: Determine the Exact Past Due Amount
The first and most important step is to find out precisely how much you need to borrow. Do not guess or round up. Log into your student portal or call the bursar's office to get the exact past due balance. If you have a payment plan, calculate the amount that is currently due, not the full semester total. Borrowing more than necessary increases your interest costs and the size of your repayment, which can strain your budget later.
For example, suppose your total tuition is $4,000, but you have already paid $2,500 and the remaining $1,500 is due on Friday. You should borrow only the $1,500, not the full $4,000. If you qualify for a small emergency grant or can pay $200 from your next paycheck, borrow only $1,300. Every dollar you avoid borrowing saves you interest and fees.
Also, confirm whether the school accepts partial payments to avoid penalties. Some institutions will remove a late fee if you pay a portion by the deadline and the rest within a short window. Ask the bursar if there is any flexibility. If not, then you know the full past due amount is your target loan size. Keep a record of the conversation and any reference numbers in case of discrepancies.
Step 2: Choose a Repayment Term That Fits Your Academic Calendar
Short term loans come with different repayment structures. Some are lump sum loans due on your next payday, while others are installment loans repaid over several months. The right choice depends on when you expect to have the money to repay. If you are expecting a financial aid refund or a paycheck within two weeks, a payday style loan might be appropriate, but you must be confident about the incoming funds. If your next disbursement is two months away, an installment loan with smaller monthly payments may be safer.
Align the repayment schedule with your academic calendar. For instance, if you know your scholarship check arrives at the end of the month, choose a loan due after that date. Avoid taking a loan that comes due during a period when you have no income, such as a summer break or a semester with reduced work hours. Many lenders offer flexible repayment options, but you must ask for them explicitly. When comparing offers, look at the total cost of credit, not just the monthly payment. A longer term lowers monthly payments but increases total interest.
Consider your budget realistically. If you work part time and have other expenses, a large lump sum repayment could force you to borrow again. A short term installment loan with three or four payments might be more manageable. The key is to have a clear plan for where the repayment money will come from before you accept the loan.
Step 3: Compare Loan Offers from Multiple Lenders
Once you know the amount and the ideal repayment timeline, it is time to gather offers. A loan connection service like LendersCashLoan can streamline this step by letting you submit one request and receive potential offers from a network of third party lenders. This saves you from visiting multiple lender websites and filling out repetitive forms. The service is free to use and does not obligate you to accept any offer.
When reviewing offers, pay attention to the annual percentage rate (APR), origination fees, late payment penalties, and the exact repayment schedule. A lower APR is generally better, but a slightly higher APR with a more convenient repayment date might be worth considering if it prevents a late payment. Also, check whether the lender reports to credit bureaus; on time payments can help build your credit, while late payments can hurt it.
Do not accept the first offer you receive. Even though time is tight, a few minutes of comparison can save you significant money. Use a simple table to list each offer's key terms. If you are using LendersCashLoan, you can review the offers side by side and choose the one that best fits your needs. Remember that LendersCashLoan is not a lender and does not make credit decisions; the loan terms are set by the lender you choose.
Step 4: Submit Your Application and Review the Contract
After selecting an offer, you will complete the lender's application and provide any required documentation. This may include proof of income, a bank statement, and identification. The process is typically quick, but accuracy is crucial. Double check your bank account number and routing number to avoid funding delays. Once approved, the lender will send you a contract. Read it carefully, paying special attention to the repayment date, the total amount you will owe, and any fees for early repayment or late payment.
If any part of the contract is unclear, contact the lender directly to ask questions. Do not sign until you understand the terms. Some lenders may offer a cooling off period during which you can cancel the loan without penalty. Ask about this. Also, confirm how the funds will be delivered: some lenders send money via direct deposit within one business day, while others may take longer. If your tuition deadline is very close, ask about expedited funding options.
Keep a copy of the contract and set a reminder for the repayment date. Missing a payment can result in fees and damage to your credit score. If you anticipate difficulty repaying, contact the lender before the due date to discuss options. Many lenders are willing to work with borrowers who communicate proactively.
Step 5: Use the Funds Specifically for Tuition
It may sound obvious, but once the money hits your account, use it only for the tuition payment. It is tempting to divert some funds to other pressing bills, but doing so could leave you short when the bursar processes your payment. Pay the school directly using the method they prefer (online portal, wire transfer, or in person) and keep the receipt. Confirm with the bursar's office that your payment has been applied and that your account is clear. This step protects you from any administrative errors.
If you borrowed slightly more than the exact tuition amount to cover transaction fees, use the surplus only for that purpose. Do not spend it on discretionary items. The goal is to resolve the deadline with minimal borrowing. After the payment clears, update your budget to account for the upcoming loan repayment.
Alternatives to Consider Alongside a Short Term Loan
Before committing to a loan, explore whether any of these alternatives can reduce the amount you need to borrow or eliminate the need altogether. Combining a small loan with one of these options can lower your overall cost.
- Institutional payment plans: Many schools offer tuition installment plans that split the balance into smaller monthly payments. While there may be an enrollment fee, it is often much lower than loan interest. Ask the bursar if you can set up a plan for the past due amount.
- Emergency aid from the school: Some colleges have emergency funds or hardship grants for students facing temporary financial crises. These funds do not require repayment. Check with the financial aid office.
- Payment deadline extension: In rare cases, the bursar may grant a short extension if you can demonstrate that funds are in transit. This is not guaranteed, but it costs nothing to ask.
- Family or friends: A short term loan from a trusted person can be interest free, but it is important to put the agreement in writing to avoid misunderstandings.
These alternatives are not always available, but they are worth a few phone calls. If you do need a loan, consider using a smaller loan to cover only the portion that cannot be addressed through these other means. For more information on finding quick funding, see our guide on short term lender offers for quick funding.
Understanding the Risks and Responsible Borrowing
A short term loan is a serious financial commitment. Late payments can lead to additional fees, higher interest rates, and negative marks on your credit report. If you are already struggling with debt, adding another loan may worsen your situation. Before you borrow, create a simple budget that accounts for the loan repayment alongside your regular expenses. If the numbers do not work, consider whether a smaller loan or an alternative solution is possible.
Also, be aware that short term loans are not a long term financial solution. They are designed to bridge a one time gap. If you find yourself repeatedly using short term loans to cover recurring expenses, seek help from a financial counselor or a nonprofit credit counseling agency. Many schools offer free financial literacy resources for students.
When you use a loan connection service, remember that the service does not lend money. It connects you with lenders. You should review the lender's terms and conditions, including privacy policies and consent for credit checks. LendersCashLoan provides a free, no obligation way to explore your options, but the final decision and responsibility rest with you.
How LendersCashLoan Can Help You Meet the Deadline
If you have decided that a short term loan is the right bridge for your tuition deadline, LendersCashLoan can simplify the process of finding a lender. The platform allows you to submit one request and get matched with third party lenders who may offer you a loan. The request form takes only a few minutes to complete, and you can indicate the amount you need and your preferred repayment timeline. The service is free, secure, and does not obligate you to accept any offer.
LendersCashLoan welcomes applicants with less than perfect credit, as long as they meet basic income and age requirements. The network includes lenders who offer payday loans, personal loans, and installment loans, so you can compare different types of credit. After you submit your request, you may receive multiple offers; review them carefully and choose the one that fits your budget. For more details on how the process works, visit StartPaydayLoan.
Remember that LendersCashLoan is not a lender and does not make credit decisions. The loan terms, including APR and repayment schedule, are determined by the lender you select. Always read the loan agreement before signing. By following the steps in this guide and using a connection service responsibly, you can cover your tuition deadline without derailing your financial health.