
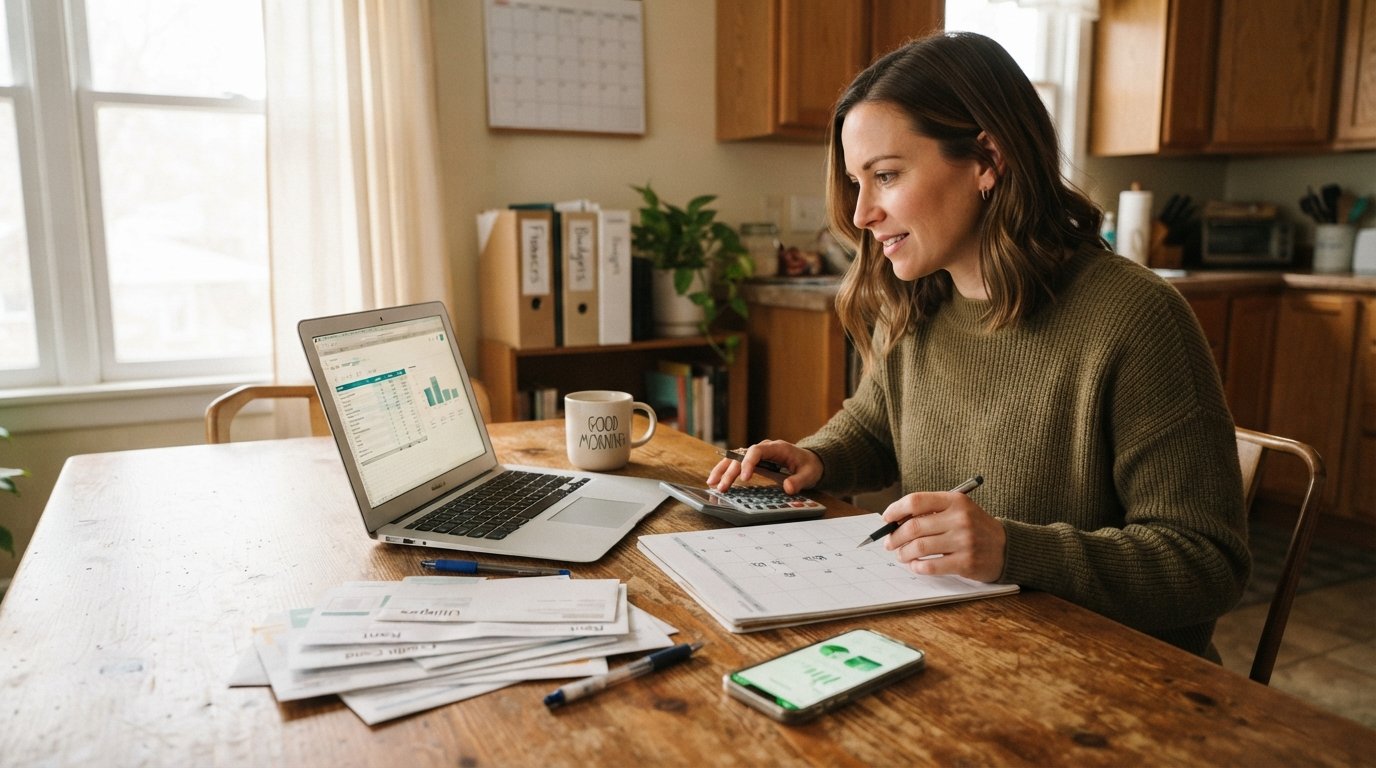
Installment Loan With Biweekly Payments: How It Works
An installment loan with biweekly payments can cut interest and match your paycheck. See how to confirm terms, align due dates, and save money.
By Wesley Owens
When an unexpected expense hits, like a car repair or a medical bill, a lump-sum repayment can feel impossible on a tight budget. That is where an installment loan with biweekly payments can offer a more manageable path. Instead of facing one large monthly bill, you split the cost into smaller, more frequent payments that align with your paycheck. This structure can reduce financial stress and even save you money on interest if the lender applies payments correctly. But how exactly does it work, and is it the right choice for you? This guide breaks down the mechanics, the potential savings, and what to check before you sign.
What Is an Installment Loan With Biweekly Payments?
An installment loan is a type of closed-end credit that you repay in fixed installments over a set period, typically ranging from a few months to several years. Each payment goes toward both principal and interest, and once the loan is paid off, the account closes. A biweekly payment schedule simply means you make a payment every two weeks instead of once a month. That translates to 26 payments per year rather than 12, which can accelerate your repayment and reduce the total interest you pay.
Lenders offer biweekly payments for various loan types, including personal installment loans, auto loans, and even some payday alternatives. The key is that the lender must agree to accept payments on this schedule and apply them correctly. Some lenders automatically set up biweekly debits from your bank account, while others require you to make manual payments each period. Understanding the difference is crucial because the timing of when your payment is posted can affect how much interest accrues.
If you are new to installment loans, our guide on installment loans explained: how they work and benefits provides a solid foundation. It covers the basics of fixed payments, terms, and how interest is calculated, which will help you see why biweekly payments can be advantageous.
How Biweekly Payments Reduce Total Interest
The main financial benefit of biweekly payments is interest savings. Interest on installment loans is typically calculated based on your outstanding principal balance. When you pay more frequently, you reduce the principal balance faster, which means less interest accrues over the life of the loan. Even though each biweekly payment is roughly half of what a monthly payment would be, the extra two payments per year add up to one additional full monthly payment annually. That extra amount goes directly toward principal, shortening your loan term.
For example, imagine a $5,000 loan with a 12% annual percentage rate (APR) and a 24-month term. A standard monthly payment would be around $235. If you switch to biweekly payments of about $118, you would make 52 payments over two years instead of 24. The extra payments reduce the principal faster, and you could pay off the loan several months early, saving a meaningful amount in interest. The exact savings depend on the APR and terms, but the principle holds: more frequent payments generally mean less interest paid.
However, not all lenders apply biweekly payments in a way that maximizes savings. Some simply hold your payments until the end of the month before applying them, which defeats the purpose. To ensure you benefit, confirm that the lender applies each payment to your balance immediately upon receipt. This detail is often buried in the loan agreement, so read carefully or ask the lender directly.
Matching Payments to Your Paycheck Cycle
One of the biggest advantages of biweekly payments is that they can align with a biweekly or weekly paycheck. If you get paid every two weeks, scheduling loan payments for the same day or the day after can make budgeting simpler. You know exactly when money is coming in and when it is going out, reducing the risk of missed payments. For those paid weekly, a biweekly payment might still work, but you may need to set aside half of the payment each week to ensure the full amount is available when due.
Aligning payments with your income also helps you avoid overdraft fees and late charges. Many lenders allow you to choose your payment due date, so you can pick a day that coincides with your payday. If your pay schedule is irregular, consider a weekly payment plan instead, which spreads the cost even further. The goal is to create a rhythm that feels sustainable, so you are not scrambling to cover a large lump sum each month.
Here are a few tips to match your payments to your paycheck:
- Identify your pay frequency and the exact dates you receive funds.
- Ask the lender if you can set your due date to match your payday.
- Use automatic transfers to avoid forgetting payments, but ensure funds are available.
- If paid weekly, divide your biweekly payment by two and set aside that amount each week.
By synchronizing your loan payments with your income, you create a more predictable financial routine. This can be especially helpful for people with variable incomes or those who struggle with monthly budgeting.
What to Confirm in the Lender Agreement
Before committing to a biweekly payment plan, you need to verify several details in the lender agreement. Not all lenders offer true biweekly payment options, and some may impose fees or restrictions. Key items to confirm include:
- Payment application method: Does the lender apply each payment immediately to principal and interest, or do they hold payments until the end of the month?
- Prepayment penalties: Are there any fees for paying off the loan early? Biweekly payments often lead to early payoff, so you want to avoid penalties.
- Automatic payment setup: Is there a fee for setting up biweekly auto-debits? Some lenders charge for this convenience.
- Late payment policy: What happens if a payment is a day late? Are there grace periods?
Additionally, confirm that the lender reports biweekly payments to credit bureaus. Consistent, on-time payments can help build your credit history, but only if they are reported. If you have less-than-perfect credit, demonstrating reliable payments can be a step toward improving your score.
It is also wise to ask about customer service support for biweekly plans. Some lenders have dedicated teams to help you manage the schedule, while others may not be as flexible. Clear communication upfront can prevent misunderstandings later.
Pros and Cons of Biweekly Installment Loans
Like any financial product, biweekly installment loans come with trade-offs. On the positive side, they can reduce total interest, shorten your loan term, and align with your pay cycle. They also encourage disciplined repayment, as you are making payments more frequently. For borrowers who struggle with large monthly bills, the smaller, more frequent payments can feel less overwhelming.
On the downside, biweekly payments require more frequent monitoring if they are not automated. You might need to adjust your budget to account for 26 payments per year instead of 12, which can be a mental shift. Some lenders may not offer true biweekly plans, and those that do might charge setup fees. Additionally, if you have irregular income, keeping up with biweekly payments could be challenging.
Weighing these pros and cons against your personal financial situation is essential. If you have a steady paycheck and can automate payments, biweekly can be a smart strategy. If your income fluctuates, you might prefer a more flexible repayment schedule.
How to Get Started With a Biweekly Installment Loan
Finding a lender that offers biweekly installment loans can take some research. Many online lenders and credit unions provide this option, but you need to compare terms, APRs, and fees. Start by checking with lenders you already have a relationship with, as they may offer preferential terms. Then, expand your search to online platforms that specialize in connecting borrowers with lenders.
One such platform is StartPaydayLoan, a free online connection service that helps U.S. consumers find short-term and payday loan options. Visitors complete one simple request form and may be matched with third-party lenders in our network. StartPaydayLoan is not a lender and does not make credit decisions; any loan terms come directly from the lender. The site also publishes plain-language guides on borrowing, budgeting, and responsible lending, which can help you make informed choices. While the name suggests payday loans, the network may include installment loans with biweekly payment options, so it is worth exploring if you are seeking multiple offers from different lenders.
When you apply, be prepared to provide basic information such as your income, employment status, and banking details. The application typically takes just a few minutes, and you may receive offers from multiple lenders. Review each offer carefully, paying attention to the APR, fees, and repayment terms. Look specifically for lenders that explicitly offer biweekly payments and confirm how they apply payments.
Alternatives to Biweekly Installment Loans
If a biweekly installment loan does not fit your needs, consider other options. A traditional monthly installment loan might be simpler if you prefer one payment per month. A line of credit offers flexibility to draw funds as needed and repay on your own schedule. For those with good credit, a 0% APR credit card can provide an interest-free period if you can pay off the balance quickly. For urgent cash needs, a payday loan or cash advance might be an option, but these come with high fees and short repayment terms, so use them cautiously.
It is also worth exploring credit counseling or debt management programs if you are struggling with multiple debts. These services can help you consolidate payments and negotiate lower interest rates with creditors. However, they may not provide the fast cash you need for an emergency.
Ultimately, the best choice depends on your financial situation, your ability to repay, and your preference for payment frequency. Biweekly installment loans are a valuable tool for many borrowers, but they are not a one-size-fits-all solution.
Final Thoughts
An installment loan with biweekly payments can be a practical way to manage a loan while aligning with your paycheck and potentially saving on interest. By understanding how payments are applied, confirming key terms in the lender agreement, and choosing a schedule that fits your income, you can make this repayment strategy work for you. Remember that short-term loans are not a long-term financial solution, and borrowing should be done responsibly. If you are ready to explore offers, consider using a connection service like LendersCashLoan to compare options from multiple lenders and find a plan that suits your needs.